Federal Reserve Chair Kevin Warsh on Wednesday presided over the first US interest rate increase since 2023, and rate hikes are generally a package deal, as the aphorism goes. Versions of that folk wisdom circulated ahead of the decision, delivered by the likes of former president of the Federal Reserve Bank of St. Louis Jim Bullard and one-time Fed Vice Chair Richard Clarida. Their conviction is reflected in market pricing, with swaps traders anticipating around three more increases by late 2027.
The heuristic has a reasonable basis in financial market mechanics: Under most circumstances, a single quarter-point rate adjustment rarely does much to sway the broader bond market, financial conditions or the economy. But there is a clear exception to the rule — Alan Greenspan’s mid-cycle one-and-done rate move in March 1997. It’s an excellent analog to the present moment, and shows that some economies cry out for subtle, even trivial-seeming tinkering.
In a survey of policymakers released with the decision, the median participant thought the Fed would probably lift rates once more by the end of 2026. The poll covered 18 Federal Reserve bank presidents and Federal Reserve Board members, but not the chair. The vast majority of respondents, though, also acknowledged heightened uncertainty around their inflation forecasts. When asked during the post-decision press conference for his view on what’s next, Warsh was tight-lipped: “I’m not going to prejudge any future decisions we make,” he said. So are multiple rate hikes really baked in?
Let’s begin with the basics. In the modern history of the Fed1, nearly all hiking cycles have started with rates ultra low once an economic recovery from recession was in place, so policymakers had a lot of ground to cover. The sole exceptions were 1997 and today2, with rates having moved to 3.75%-4%.
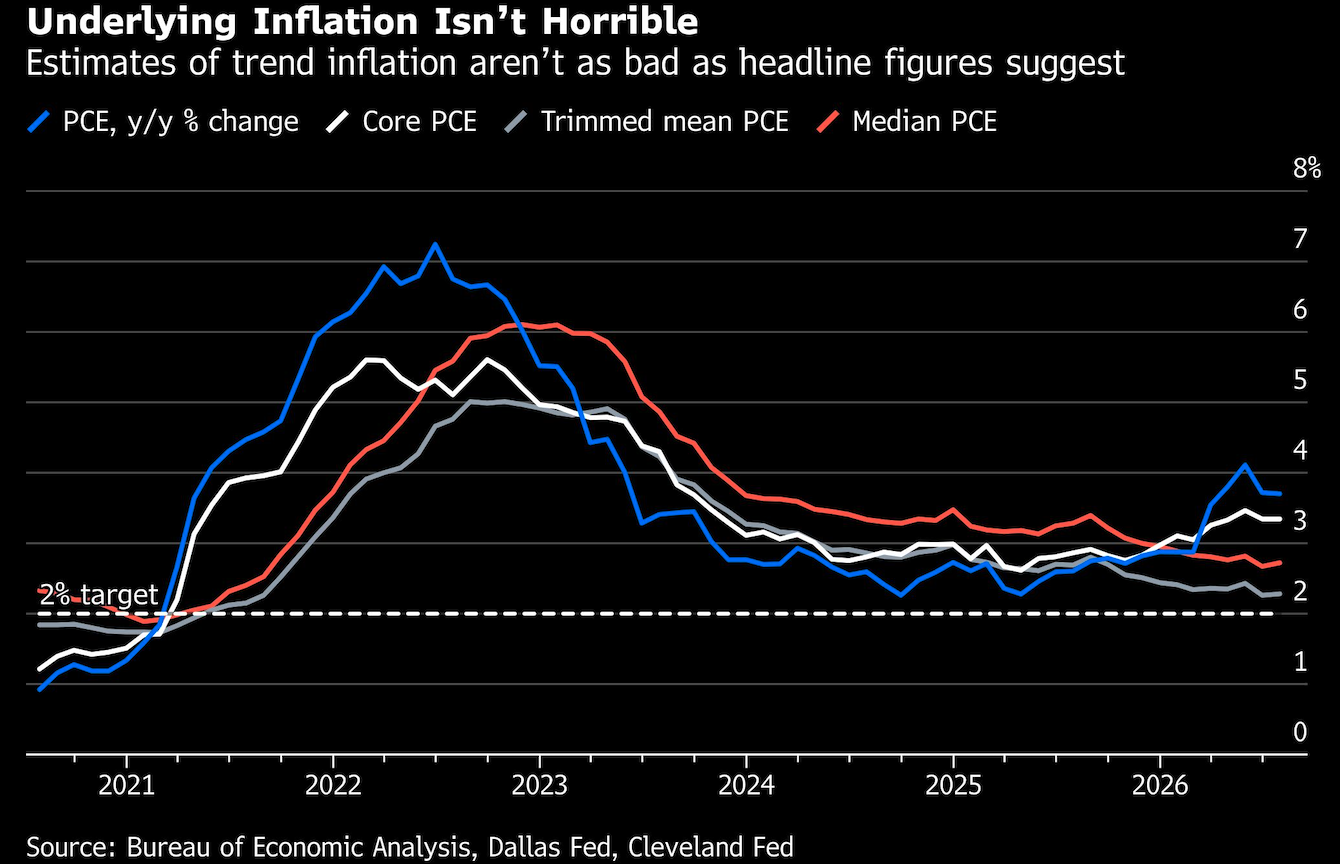
Like Greenspan, who was known as the “Maestro,” rookie Chair Warsh finds himself in fine-tuning mode. Squint past the noise of volatile oil prices and other temporary factors, and underlying inflation may be as low as 2.3%-2.7% — above the 2% objective, but hardly an inferno. Warsh’s problem is that it’s been above target for five and a half years and is no longer cooling, and it probably needs a nudge to resume its 2022-2024 disinflationary trend.
Greenspan’s calibration challenge was similarly nuanced: Economic growth was strong and unemployment had fallen sharply. Policymakers wondered if the economy was at risk of overheating, triggering inflation down the road. Though it was still under control at the time of the hike, the Fed’s internal models forecast that the core consumer price index would rise modestly by about 3.2% in 1998 due to labor market tightness.

See more: Fed Watch: Finally, ‘Walkin’ the Walk’
Another similarity: Warsh finds himself adjusting to a potential technological jolt from artificial intelligence that could drive up productivity and growth, and change assumptions about how interest rates work. Greenspan was contending with the start of the internet revolution.
When the ground shifts under them, policymakers can’t be sure what constitutes a “restrictive,” “neutral” or “accommodative” stance of policy rates. They’re feeling around in the dark, as evidenced by the latest rise in their estimates of the neutral rate — the theoretical equilibrium level that neither restrains nor stimulates the economy — to 3.2%, the highest in a decade. The internal Fed survey also signaled that policymakers may take their time bringing rates back down from the peak to that perceived neutral level. In reality, productivity-led growth is somewhat unpredictable for rates, potentially limiting inflation but also raising demand for borrowing.
In 1997 too, the rate-setting committee openly debated the implications of a surreptitiously rising neutral rate: “If monetary policy failed to recognize the changes in the equilibrium situation and did not adjust nominal interest rates higher, then effectively, to use the language we normally employ, we would have eased monetary policy even if we maintained the same level of nominal interest rates,” Federal Reserve Bank of Richmond President J. Alfred Broaddus told Greenspan at the time, according to a transcript of the meeting — a sentence that could just as well have been written in September 2026.
Finally, the Fed’s actions Wednesday buttress its credibility. Appointed by President Donald Trump, the biggest monetary policy interventionist to hold the presidency in recent history, Warsh began his tenure with questions already swirling about his independence, deservedly or not. Trump has publicly demanded cuts in recent weeks, as the rate hike became a consensus expectation in markets. A failure to act would have looked as if Warsh was cowed by the president ahead of midterm elections in November.
Greenspan’s Fed understood the importance of credibility too, since the committee hadn’t flexed its hiking muscles since the tightening of 1994 to 1995. “My reading of the economy supports the conclusion that we are at risk of losing the hard-won credibility of our commitment to hold inflation,” Thomas C. Melzer, the president of the Fed Bank of St. Louis, told the committee at the meeting.
Greenspan has received significant praise, including from Warsh himself, for his prescient prediction that inflation would remain contained, and his refusal to stamp out a strong economy. Yet he also got somewhat lucky, helped by a global collapse in energy prices, a strong dollar that made imports cheap and a hard-won institutional reputation burnished by Greenspan’s predecessor Paul Volcker. Also worth noting: Greenspan and his colleagues didn’t explicitly intend for 1997 to be one-and-done from the outset. But he developed a thesis about productivity keeping a lid on inflation over subsequent meetings, and by 1998, a Russian default and the collapse of hedge fund Long-Term Capital Management put the Fed back in cutting mode.
So what’s the point of a tiny adjustment? Having taken action to protect Fed credibility, Warsh has bought himself cheap optionality. If the economy ends up needing more, he can still deliver it down the road. But he’s probably not too far from his final destination. And with some Greenspanian luck, he might already be there.
1. I count from 1994, when the Fed started publicly and contemporaneously announcing policy rate decisions.
2. There is potentially one other exception: December 2015, when the Fed hiked once and then waited another year to get on with further rate increases. It's a judgement call, but I lump that together with the 2016-2018 hikes as part of a broader series.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
Read more articles by Jonathan Levin