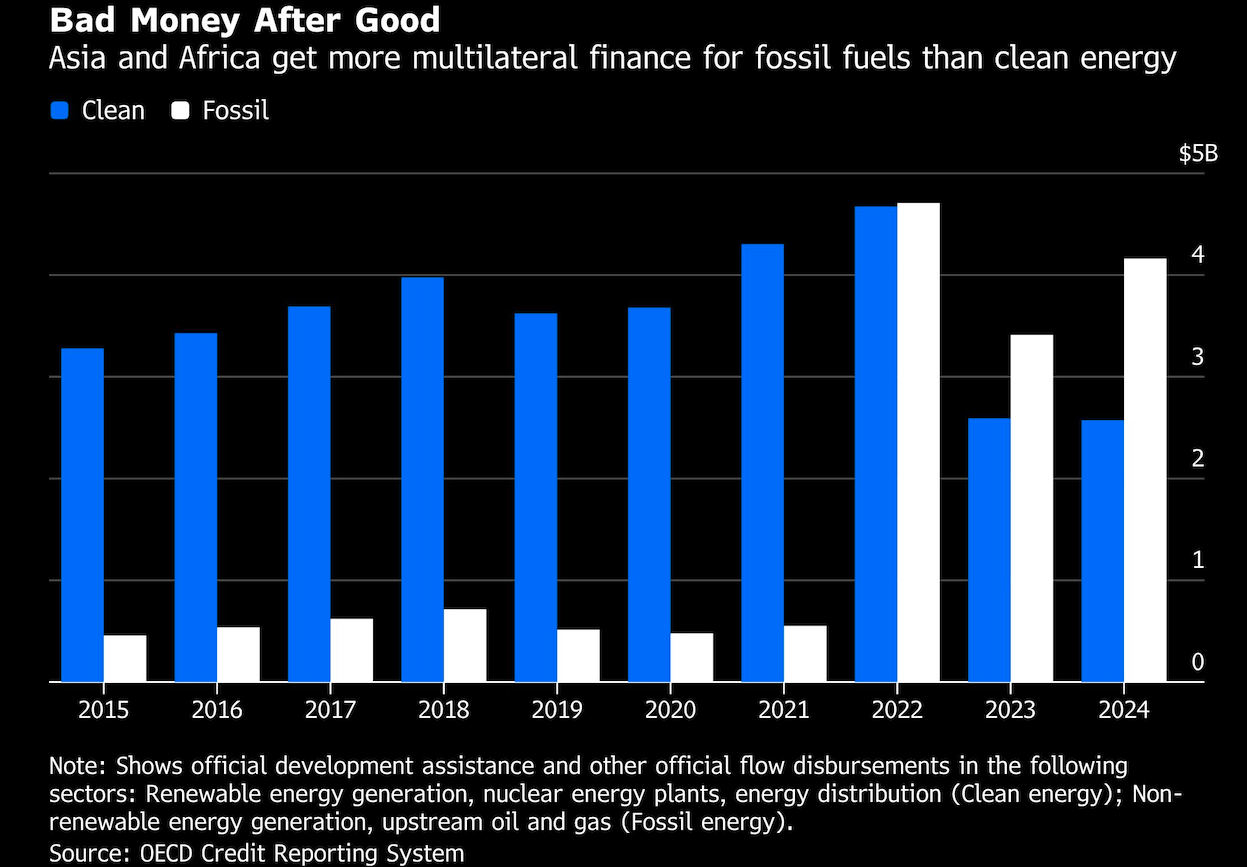
With Brent crude above $100 a barrel for most of the past month and diesel prices more than twice as high, you might imagine that the world’s poorest fossil fuel importers would be hitting crisis conditions right now.
That they’re not quite there is down to one of the fastest-growing trends in development finance — helping oil and gas users pay for fuel they can’t afford.
Take the $3.3 billion emergency energy package agreed by Bangladesh’s government last week. Some $200 million from the Asian Development Bank will go toward a five-year program repairing the crumbling electricity grid on the fast-urbanizing fringes of the capital Dhaka, where power cuts lasting 12 hours or more have provoked protests and blockades. The lion’s share of the money, though — some $3.1 billion — will pay for oil and gas imports in just the current fiscal year.
That money, in turn, depends heavily on the cash and expertise of one of the world’s fastest-growing multilateral banks, the International Islamic Trade Finance Corp., or ITFC.
Unlike conventional multilaterals such as the World Bank and Asian Development Bank, the ITFC isn’t primarily in the business of providing cheap financing for infrastructure to aid economic development. Instead, most of the $78 billion it has disbursed since it was founded in 2008 has gone to transactions similar to the Bangladeshi loan: Semi-commercial lending to help cash-strapped countries pay for their imports of petroleum. That’s a win for the OPEC members who are the ITFC’s main shareholders.
The hunger for such finance has been enough to turn the ITFC into one of the world’s major multilateral lenders in recent years. Between 2020 and 2024, total disbursements came to $29 billion, putting it in the same league as conventional institutions such as the African Development Bank and European Bank for Reconstruction and Development. This year alone, it has signed framework agreements worth $1.5 billion apiece for the Maldives and Egypt, plus $2.9 billion for Burkina Faso, Cote d’Ivoire and Djibouti, $1 billion for Mauritania and $706 million for Senegal.
See more: The ESG Trust Gap That Doesn't Show Up in Performance Reports
There’s nothing nefarious about this. As anyone in Havana, Karachi or Manila these days would appreciate, being starved of fuel imports can be as devastating as going through a currency crisis. By supporting recipients through such emergencies, the ITFC is meeting the immediate needs of desperate people, as the International Monetary Fund does when foreign-exchange reserves dry up. A slice of its lending goes to non-petroleum needs, too: About 16% of cumulative disbursements through 2024 went to food and agriculture, compared with 67% going direct to non-renewable energy.
It still looks like a bad deal for recipients. The world’s poorest nations, including many members of the Organization of Islamic Cooperation that the ITFC was set up to serve, struggle to grow because they’re short of capital. Repeatedly borrowing money to finance fuel imports doesn’t solve that underlying problem — it merely defers it to a later date, when the same issues of depleted foreign-exchange reserves and government debt may well recur.

Worse, it encourages recipients to pay richer countries for fuel that will all be burned in a matter of months, when their fundamental problem is a shortage of assets that could support decades of growth. A billion dollars’-worth of solar farms will provide roughly 10 times as much electricity over their lifetimes as the same amount of money spent on liquefied natural gas. Cheap financing for the latter, however, is readily available, whereas the former must struggle through the interminable approval processes at major development banks.
The outcome of all this is to keep developing countries hooked on fossil fuels when better alternatives are already available. Bangladesh’s underscores this absurdity: One of the countries most at risk of flooding, heatwaves and cyclones as climate change intensifies is borrowing money from oil exporters to buy petroleum. That fuel, in turn, is too expensive for its own citizens to buy without further government subsidies. Meanwhile, the same government cultivates a thicket of regulations to choke the growth of cheaper clean energy.
The answer to this isn’t to get mad, but to get even. Conventional development banks have been too slow and cumbersome in financing clean power on the scale required. If the energy transition is to avoid being outspent by by the fossil-fuel economy, its lenders will have to step up their game.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
More Innovative ETFs Topics >