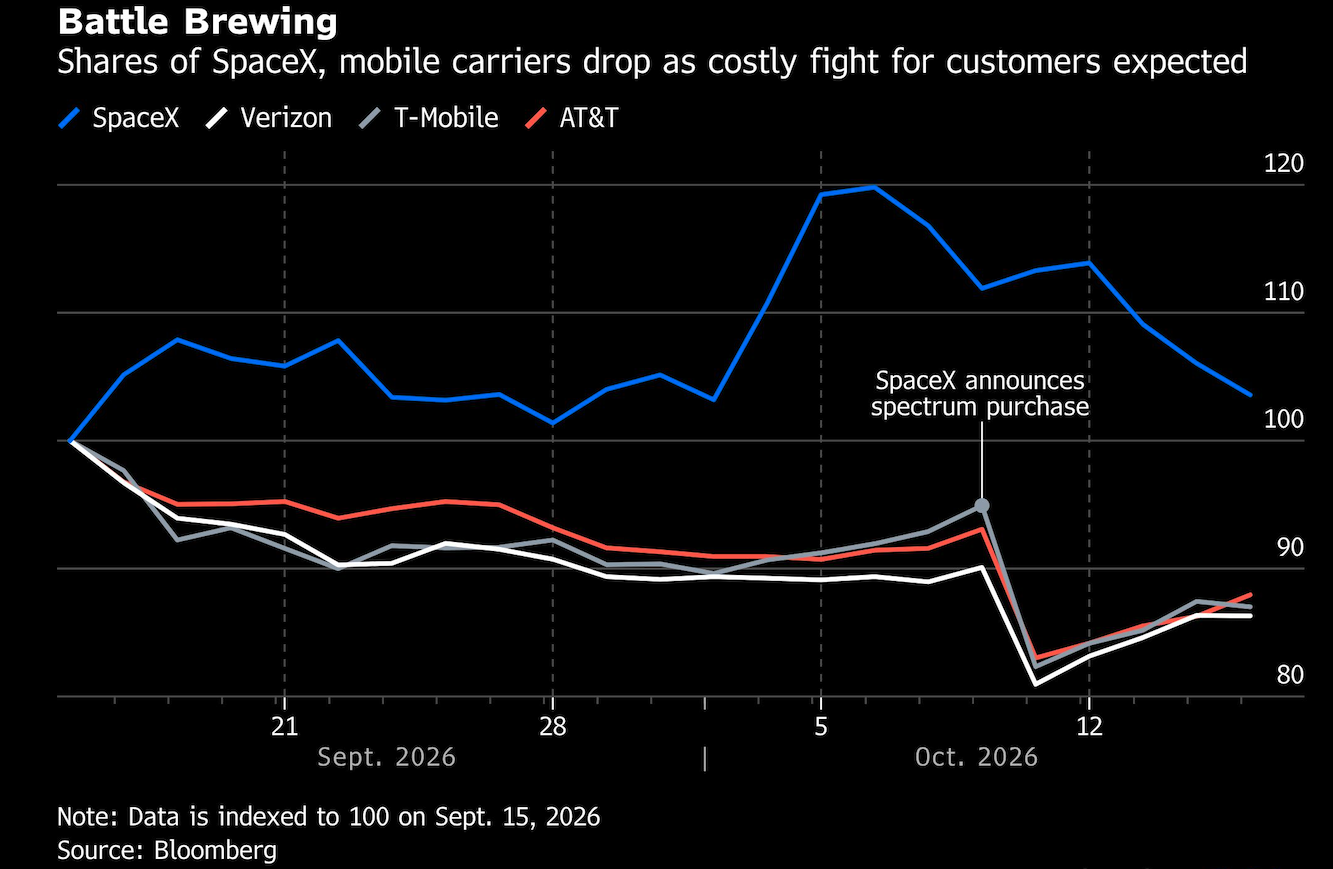
Elon Musk’s decision to wade into US mobile-phone services sets up a challenge distinct from anything he’s previously pursued. This is not a new market or an added twist that fills an industry gap such as his innovations with electric vehicles, broadband from low-earth orbit or an online payment system — the areas where Musk made his riches.
This is a dogfight with three entrenched players. It’s likely to benefit wireless customers, but for SpaceX investors, it will be expensive and risky, and comes with an uncertain payoff.
The $240 billion US mobile services market is dominated by AT&T Inc., Verizon Communications Inc. and T-Mobile US Inc., all of which spend heavily on the latest technology for their networks to keep ahead of each other and feed consumers’ insatiable demand for bandwidth. It will cost tens of billions of dollars to build Musk’s vision of a hybrid network with 15,000 satellites dedicated to direct-to-device and the ground infrastructure required to compete with the legacy carriers in urban areas. SpaceX’s satellite capacity will broaden coverage to rural and remote areas, but that isn’t where the people or the profits are concentrated.
This leaves many unanswered questions about the potential return on investment and the time it will take to build the network. You can bet AT&T, Verizon and T-Mobile will fight back. All three saw their stocks plummet the day after Musk made firm his intention to become a fourth large mobile service provider. SpaceX has dropped about 9% this week.

Musk is planning a major push into a market with little or no subscriber growth because most people already have a phone. Investors need more details on SpaceX’s strategy and the potential returns, especially when the company is already spending so heavily on other projects. There are investments in a data-centers-in-space network and plans to reportedly borrow $40 billion to purchase Nvidia Corp. computer chips for its xAI venture. Many of Musk’s ambitions hinge on the ability to launch Starship frequently and to capture both stages of this massive rocket, which would drive down launch costs.
See more: Economic Desiderata
The opportunity for SpaceX lies with operating margins of more than 20% for Verizon and T-Mobile in 2025 and close to that level for AT&T. If SpaceX is able to offer comparable service at a lower price, it could potentially carve out market share. The incumbents will compete on price, too — a win-win for consumers. If SpaceX’s offering is mostly around extended coverage and zero dead zones, then its appeal will be limited to those customers who live or venture to remote areas — a small addressable market.
Musk advanced his plans last week with the purchase of 14 megahertz of paired low-band spectrum — a premium asset in wireless telephony — and Federal Communications Commission approval to build out his direct-to-device satellite network. SpaceX last year agreed to pay $17 billion for EchoStar Corp.’s medium-band spectrum. Even with these two spectrum purchases, the company is far behind the big three’s capacity and will need to snap up more spectrum in auctions or private deals. Expect the legacy carriers to also gobble up more spectrum to keep their lead.
The investment needed to build out a ground network is hard to nail down. The macro base stations at cell towers can cost as much as $250,000 each, depending on the area, according to Richard Haas, a spectrum expert with LS Telcom in the UK. SpaceX may need around 50,000 of these sites, which would put the investment at $12 billion at the upper range, he wrote. That doesn’t seem onerous.
Another indication of the cost of building out the network comes from the bankruptcy filing by Dish DBS Corp., a unit of EchoStar, which attempted to become a fourth carrier with the help of subscribers it picked up as part of an acquisition. EchoStar ended up spending $30 billion on spectrum and $16 billion on wireless infrastructure. The network wasn’t fully completed and subscribers had shrunk to about 7.4 million by the June bankruptcy filing from 8.5 million in 2021.
SpaceX is a much more formidable competitor with unique satellite technology and deep pockets, but it is also playing catchup in a mature market, where it will have to wrestle customers away from legacy players. Investors know that whether SpaceX gains traction or not, the battle will first bruise everyone.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
More Asian/European Markets Topics >