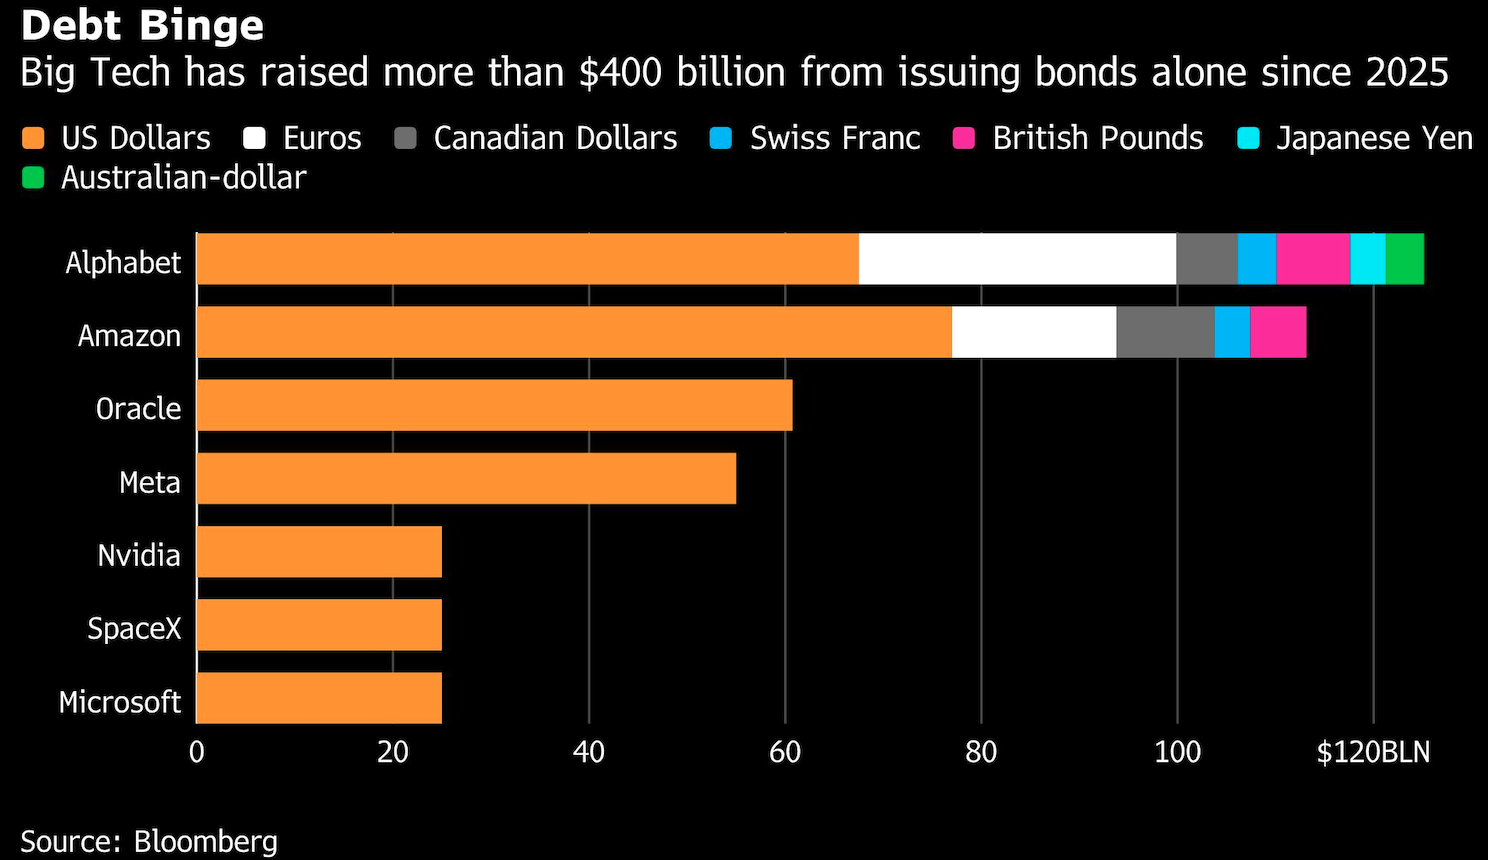
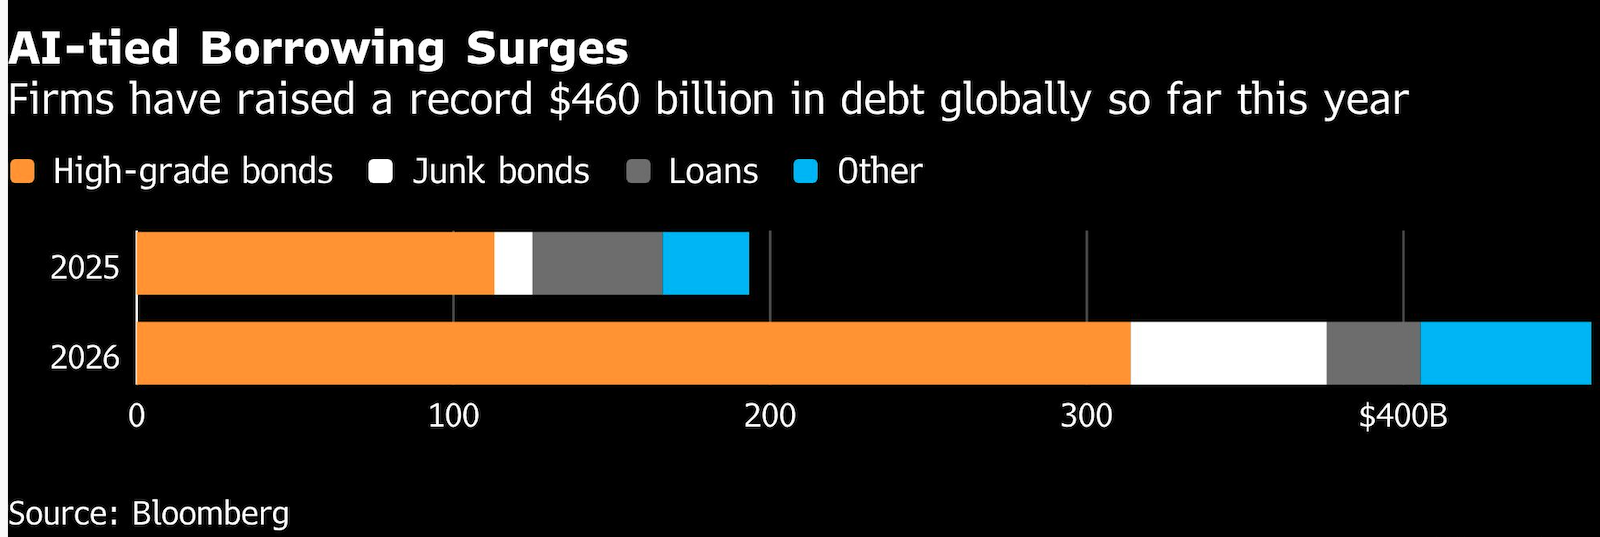
The unprecedented investment boom to build out the infrastructure for artificial intelligence is projected to reach more than $10 trillion, if all current plans are realized. The money is coming from many sources, including corporate cash flows, public equity and debt issuance, private debt issuance, off-balance sheet lease obligations and guarantees to AI data center developers from so-called hyperscalers and the leading chip provider, Nividia Corp.
There are several reasons for concern.
First, the nature of the race is likely to lead to overinvestment because it’s mostly a winner-take-all type of contest. There are more race participants — at least seven or eight companies with AI hyperscaler aspirations -- who are all trying to get to the finish line first. But the number of companies that will succeed will likely be no more than two or three as economies of scope and scale and network effects lead to a high degree of concentration in the provision of AI compute and other AI services. The high degree of market concentration in the provision of Cloud IT services seems likely to be replicated in provision of AI.
Second, it is unclear whether the industry will be able to generate sufficient revenue to generate an adequate return on capital to justify and sustain its investment. Given the rapid depreciation rate of AI data centers, it would likely require $3 trillion or more of revenue each year to generate an adequate return on that investment.

See more: AI Is Building Better Systems for Trust Officers & Their Clients
If a bust might lie ahead, we should also worry that the current boom may be sowing the seeds for a future financial crisis. At a minimum, the end of the boom would lead to a sharp retrenchment in the equity market. But the bigger question would concern the consequences for the AI lenders. After all, it was decline in the value of housing collateral and the lending that collateral supported that resulted in the Great Financial Crisis almost 20 years ago.
The risk of another GFC seems low for three reasons. First, concerns about an AI bust are prevalent. In contrast, during the early stages of the GFC, investors were in denial. Subprime mortgage lending was viewed as not very risky, AAA-rated collateralized debt obligations, or CDOs, were judged as safe, and investors took comfort in the fact that US housing prices had never declined on a national basis since the Great Depression.
Second, the financing of the AI investment boom seems more robust. In the GFC, one important accelerant was the fact that long-term illiquid assets such as complex CDOs were often financed by short-term liabilities. When subprime mortgage delinquencies and defaults rose, putting downward pressure on housing prices, the value of the CDOs was called into question. As a consequence, the borrowers were not able to roll over their short-term funding. The result was a fire-sale of assets that pushed the values of those assets far below their inherent value. This, in turn, caused more stress, more failures and further asset liquidations at fire-sale prices.
In contrast, most of the funding for the AI boom has a longer tenure that is better matched to the assets being financed. Insurance companies and other long-term institutional investors have greater staying power. Moreover, even in those cases in which investors have an option of taking their money out, private equity companies typically have the right to limit withdrawals. As a result, a fire-sale of assets seems much less likely.
That said, there are characteristics of the AI boom that are concerning. In particular, it is not easy to assess counterparty exposures and how those exposures might change if the outlook for investment returns or the financing environment were to worsen. And financing terms are often complex and opaque. Much of the financing activity is being executed through leasing structures, which stay off the balance sheet until the data center infrastructure is completed. Also, the financing, at times, has “wrong way” risk. For example, if Nividia guarantees of future chip values were triggered, it would be happening at the same time its margins would be crashing because of lower chip prices.
So what can be done? First, securities regulators should be given an explicit financial stability mandate. Since much of this activity is taking place in the non-bank financial sector, it is important that there is a regulatory body that takes responsibility and works to identify the emerging risks.
Second, banking and securities regulators should take steps to increase transparency. Who owes what to whom and under what conditions and contingencies? Enabling financial intermediaries and investors to understand counterparty risk fosters better decision-making and earlier mid-course adjustments before things get too stretched.
Third, there should be a review of accounting practices to ensure that they fairly represent the exposure and risks.
The core regulated banking system contains high-quality information about the composition of assets and liabilities, as well as mandated capital and liquidity buffers. In the non-bank private credit sector, matters are much more opaque, and capital and liquidity needs are left to the decision of individual firms. Rules that required a fuller disclosure of actual and contingent liabilities would help investors make more informed decisions, which would constrain undue risk-taking.
Forewarned is forearmed. Given the magnitude of the AI boom, investors need better information to properly assess and price for risk.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
More Wealth Management Topics >