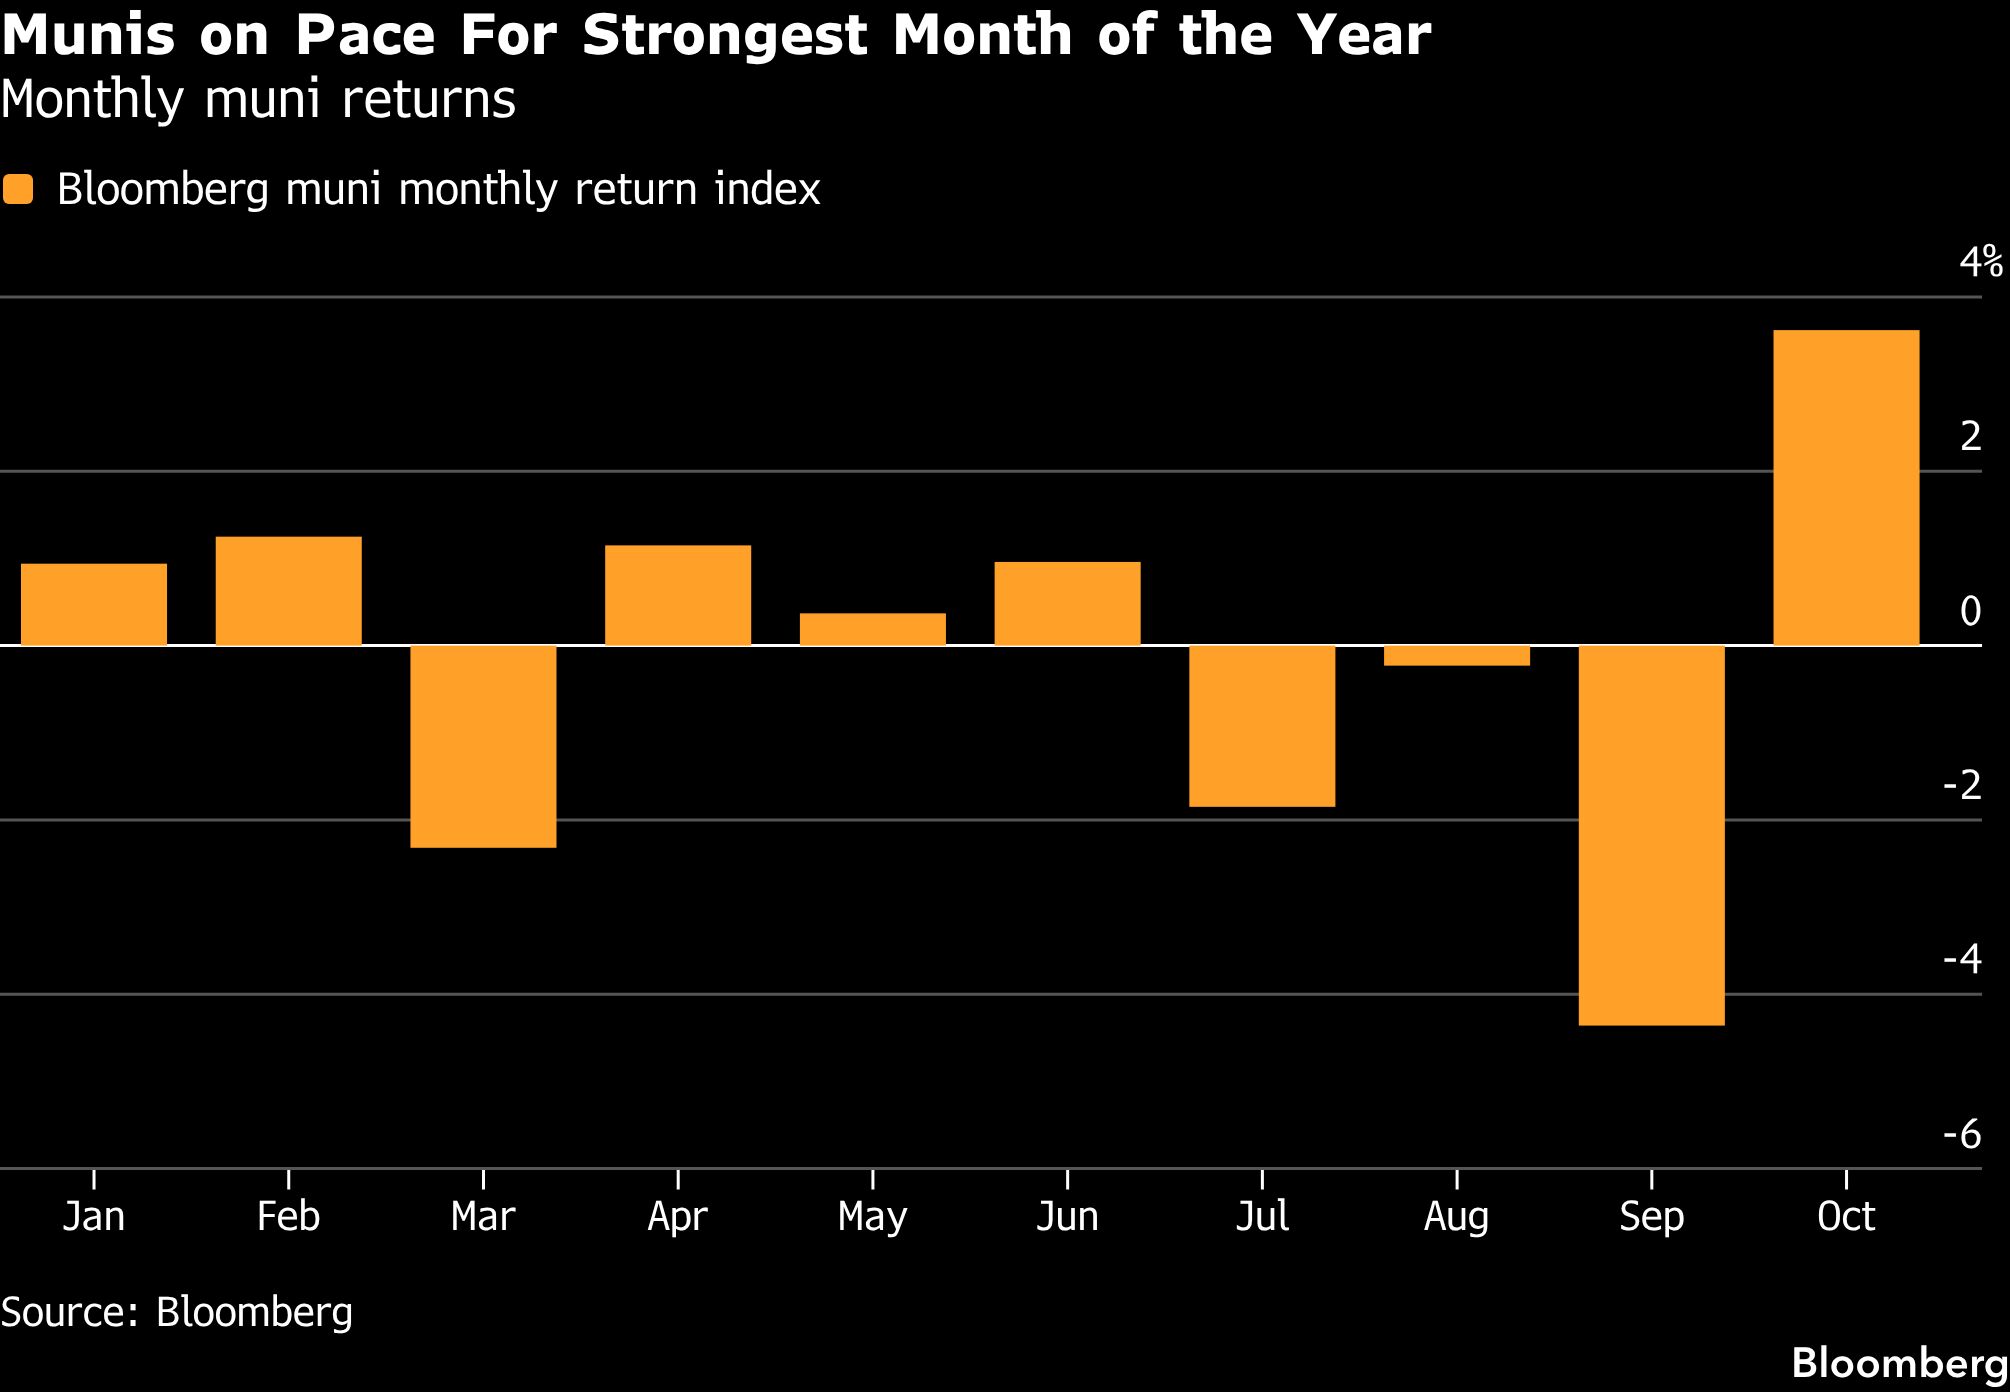
US state and local government debt is on track to notch its strongest October in more than four decades, as a relief rally follows one of the worst months for the bond market in years.
The Bloomberg Municipal Bond Index has gained roughly 3.6% so far this month through Thursday, putting it on pace for its best October since at least 1980 and its strongest month since November 2023. It would also mark the first month of positive returns since June, following months of declines fueled by concerns about inflation and interest-rate hikes.
Cheaper valuations and elevated yields led to October’s rebound, according to experts. Investors are also putting money back into munis after they sold in September to harvest tax-losses.
See more: Looking Ahead at ETFs for the 2027 Muni Bond Outlook
“A lot of people all at once are interested in the asset class for different reasons, but I think it is a value play right now,” said Eric Kazatsky, client portfolio manager at MacKay Municipal Managers. Higher yields are now attracting a deeper pool of investors, he said.

September’s selloff pushed muni yields to levels investors hadn’t seen since at least 2011 and left the market with its weakest monthly performance since 2008.
Issuers were also forced to pause some deals as state and local borrowers waited for better market conditions. Others held off on refinancing debt after municipal bond yields jumped.
The selloff also created an opportunity for investors to slash their taxes and seize on high yields through tax-loss harvesting, where investors sell securities at a loss to offset their taxable income or capital gains and then reinvest the money into muni exchange-traded funds.
“Investors learned and thought this may be an opportunity to gather some losses in portfolios,” Mark Marinella, a portfolio manager at Capital Group, said. “What’s important about that is that it’s not investors running away from the muni bond market, that’s investors harvesting losses, but staying in the muni bond market.”
Pat Haskell, head of the municipal bond group at BlackRock Inc., said that while the dislocation in the muni market was substantial, it ultimately left the market on stronger footing. Higher starting yields give investors more income and provide a greater cushion against further interest-rate volatility.
“Investors do not need to correctly predict the next move in rates to find value in municipals today,” Haskell wrote in BlackRock’s fourth quarter global fixed income outlook. “Instead, the recent repricing offers an opportunity to lock in historically attractive income and let yield do more of the work.”
US states and local governments are selling debt at a record clip, borrowing more than $500 billion so far this year as the need for infrastructure mounts. Municipal bond issuance is up roughly 6% from the same period last year and is on pace to top $600 billion by year-end, according to data compiled by Bloomberg.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
More Municipal Bonds Topics >