Investors can find clues about the future of the AI build-out from a seemingly unrelated industry.
Few investors would naturally put artificial intelligence data centers and US shale oil in the same frame. One is built on advanced semiconductors and software; the other on rock, steel and drilling rigs. But the economic pattern is familiar. A breakthrough changes what is possible, demand outruns supply, attractive profit pools emerge and capital floods in. Then capacity expands, costs fall and competition tests which businesses have durable advantages.
We’re not forecasting that AI will retrace shale’s path exactly. The two industries have vastly different technologies, customers and market structures. But in our view, the shale renaissance offers a useful lens for thinking about how opportunity can move through an innovation cycle, and why investors may need to look beyond the companies that first capture the market’s imagination.
A Surprising Parallel: Oil vs. Tech
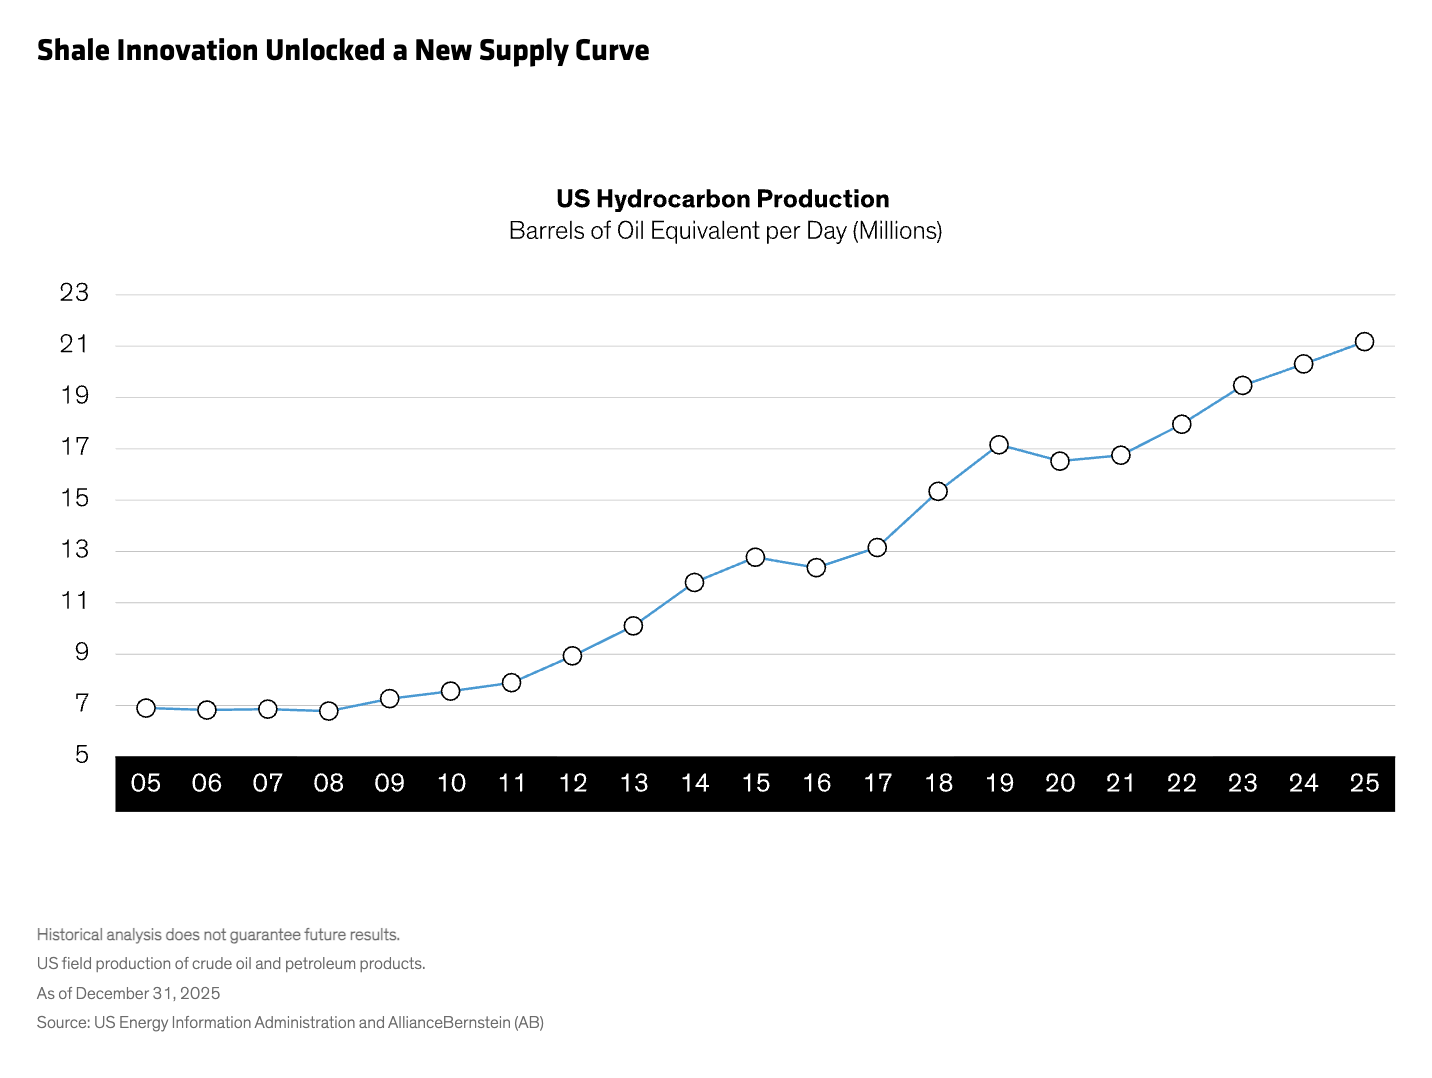
US oil and gas output was broadly stagnant in the early 2000s. Then, in 2006, horizontal drilling and hydraulic fracturing (“fracking”) made previously uneconomic resources commercially viable. Production climbed rapidly (Display) as operators refined the recipe and scaled up deployment, dramatically changing the economics for US drillers.
AI reached its own perception-changing moment with OpenAI’s late-2022 launch of ChatGPT, followed by a new generation of powerful graphics processing units (GPUs) in 2023. The combination made sophisticated generative AI applications feel practical much sooner than many businesses had expected. Demand for computing capacity surged, encouraging investment across chips, networking, power and data centers.
See more: Yields & Global Value: Inside Vanguard’s Top 8 ETFs for September
Capital Follows the Bottleneck
Some innovations are so compelling that the demand pull initially overwhelms supply. This creates unusually attractive profit pools that tend to grow much faster than mature markets. Incumbent suppliers enjoy strong, immediate benefits. These dynamics draw capital and new companies toward the constraint.
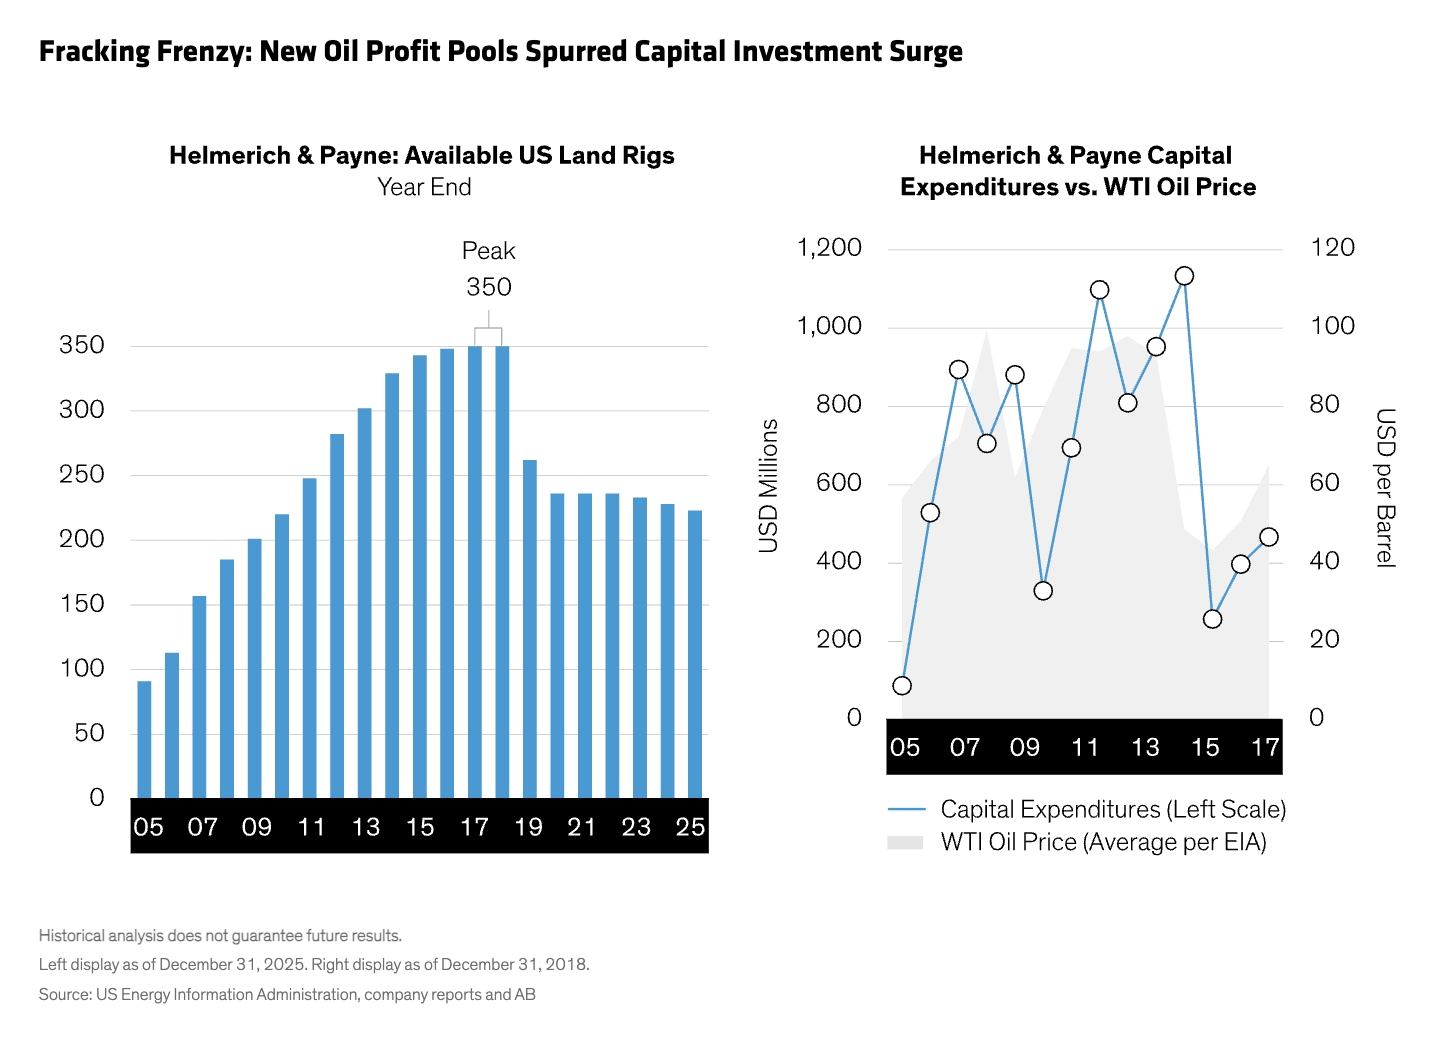
Fracking enabled US exploration & production companies (E&Ps) to access small pools of oil that couldn’t be extracted economically in the past. The industry’s supply side—the drilling services providers—expanded fleets and spending to meet producers’ demand. For example, Helmerich & Payne, the largest US drilling services provider, invested aggressively in capacity as the shale boom unfolded—tripling its available US land rigs to 329 by 2014 with capital expenditure exceeding US$1.1 billion in 2012 and 2015 (Display).
The AI ecosystem’s response rhymes. Technology companies and newer specialists are investing aggressively to secure capacity by building data centers. Yet capital intensity cuts both ways. Data centers require large upfront commitments and ongoing reinvestment as technology rapidly evolves, so today’s scarcity economics may not endure.
Productivity Can Deepen the Cycle
Supply growth is only part of the story. In shale, operators continuously improved drilling speed, automation, planning, intelligence and well productivity. These enhancements, combined with increased scale, lowered the cost of producing a barrel of oil year after year, helping US producers close much of the gap with Middle Eastern competitors. Pricing trends supported returns and encouraged further activity—and investment. The cumulative impact was easy to underestimate because many improvements compounded at once—a powerful force that is often underestimated in the early stages of a new opportunity. US hydrocarbon production has continued to rise through 2025 despite a 30% decline in Helmerich & Payne’s available US land rigs since the peak.
AI is arguably in an earlier stage of development, but we already see similarities in the pace of innovation. Since 2022, new large language models and GPU designs continue to redefine AI’s potential at lightning speed. Just as shale pushed oil prices down, the cost of generating a token is falling because of better chips, more efficient software and system architecture, as well as an abundance of models, including more low-cost open-source models. Lower costs can unlock new use cases and broaden adoption. But they may also intensify competition by making today’s scarce capability more widely available. As shale demonstrated, compounding productivity gains can eventually create enough effective supply to reshape industry economics.
Abundance Changes the Economics
Eventually, customers focus less on access and more on price, performance and reliability. Supply catches up in parts of the market, buying behavior changes and pricing power can erode. Incremental innovation releasing more effective capacity into an already expanding system accelerates the shift from scarcity to competition.
That is where the shale analogy becomes most useful. By late 2014, US E&Ps had created so much excess supply that it disrupted the global energy market, triggering a collapse in energy prices in 2015. Shale didn’t disappear, but we saw a reordering of returns, capital allocation and competitive positions. Strong operators kept improving, weaker participants consolidated or exited, and investors increasingly looked elsewhere for attractive opportunities.
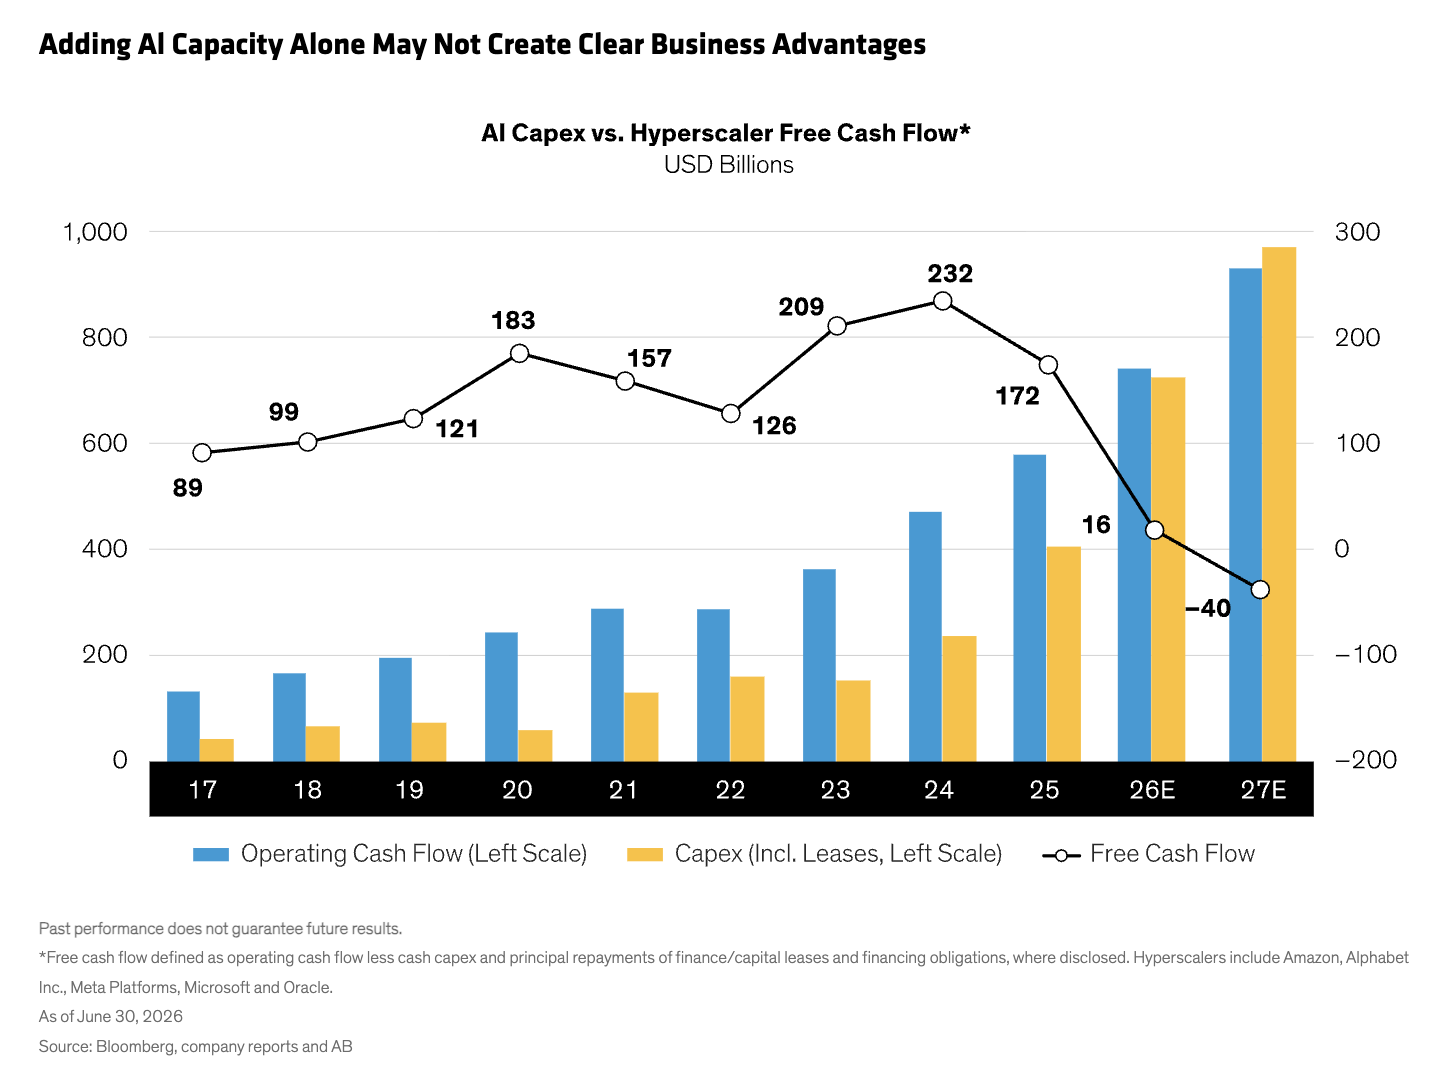
For AI, the demand curve, industry structure and the timing of any adjustment remain uncertain. Yet the focus is already shifting from adding capacity to improving efficiency, economics and more recently, safety. As cost-per-token falls and capacity grows, we believe investors must distinguish between businesses that benefit from scarcity and those that can sustain differentiation when scarcity fades. Scale, productivity, customer relevance and disciplined reinvestment may matter more than headline growth. Massive capital spending is already putting pressure on hyperscalers’ free cash flow (Display) and drawing increased scrutiny of how the AI build-out will affect profitability.
Following the Opportunity as it Migrates
The first phase of an innovation boom tends to focus attention on companies supplying the essential tools. In both AI and shale, long-term profitability depends not just on demand growth, but on capacity utilization and the durability of returns. Over time, the benefits can migrate from suppliers to users. Cheaper energy from shale supported consumers and energy-intensive industries even as returns for many producers weakened. In AI, we believe falling computing costs could similarly shift value toward businesses that use the technology to improve products, automate workflows or build new services.
This argues for a broader investment lens. The largest AI infrastructure beneficiaries may continue to grow, but sales growth may not translate into similar earnings growth.
The moral of the shale story: follow the economics. AI won’t repeat shale’s history, but it may rhyme in ways that matter for investors. Innovation creates profit pools that are expanded by capital, reshaped by productivity and redistributed by competition. As the AI cycle matures, we believe long-term equity investors should search beyond the technology sector that has dominated market attention, looking for businesses across industries that can turn falling AI costs into enhanced productivity, deeper customer relationships and durable returns on capital.
The views expressed herein do not constitute research, investment advice or trade recommendations, do not necessarily represent the views of all AB portfolio-management teams and are subject to change over time.
Chris Kotowicz joined the firm in 2007 and is a Co-Portfolio Manager and Senior Research Analyst for US Relative Value. He is also a Senior Research Analyst for the US Growth Equities team.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© AllianceBernstein
More Global Markets Topics >