For a quarter of a century, the hyperscalers have been some of the most profitable and technologically innovative businesses ever created. The reason was clear: their marginal cost per additional customer was almost zero. Costs were fixed and scale was effectively unlimited, which meant margins widened as volume grew. In the years before the current AI build, Alphabet earned 39 cents and Microsoft earned 61 cents on every dollar of capital1 . Paying 24 to 332 times profit to own them was aggressive but defensible.
Defensible in part because someone else had already paid for the ground they were built on. Around the turn of the century, the telecom industry laid enough fiber to carry the internet for a generation and went broke in the process. The hyperscalers had a genuine technological moat, but they earned those returns as beneficiaries of the last capital cycle rather than participants in it. In this cycle, they are participants — their own money, their own balance sheets, and price well down the decision tree.
Artificial intelligence disrupts the historical model. It demands massive amounts of physical capital before a dollar of revenue arrives, and it does not scale economically, as costs rise roughly with usage instead of staying fixed. The cost of serving a customer rises with how hard that customer makes the machine work.
On the capital side, power gets the headlines, but the more important cost is depreciation on the GPUs themselves, and that cost runs on a clock. A GPU loses most of its value in three to four years whether it is busy or not, primarily because the next generation makes it obsolete well before it wears out. They have set up a fixed and perishable inventory of GPU-hours that has to be sold before it expires. This is like the economics of a container ship or a refinery, not software.
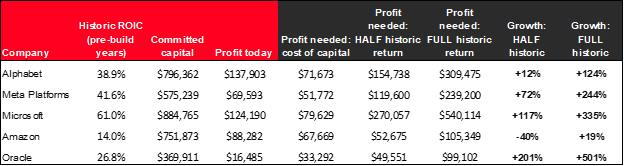
We took the capital these five companies have invested, added the capital they have committed but not yet spent, the data center leases signed and the equipment ordered that sit off the balance sheet, and calculated what that base earns today. Then we asked what it would take for each to earn what it use to earn.
None of this is impossible. It’s just a big ask for a formally non-capital-intensive business. Alphabet needs to grow profit by 124%, Meta by 244% and Microsoft by 335%. Put Meta’s number another way: 28% a year, every year, for five years. And each of those figures assumes the spending stops at year’s end (which it won’t). Every additional dollar of capital committed raises the bar even further. At that level of expected growth, Meta trades at 27 times net operating profit after tax (NOPAT).
The spending to achieve this growth has now outrun what these businesses produce, and you can see it in how they are funded. The first wave came out of free cash flow. Then the debt markets. Now the money arrives from insurance floats and pension funds. Meta financed its Louisiana data center through a joint venture it owns 20% of, which raised $27.3 billion in senior secured notes due 2049, anchored by PIMCO, with Meta guaranteeing the residual value of the campus.3
The supply side doesn’t offer any relief either. TSMC is the only company producing leading-edge AI chips at scale, which makes it the bottleneck and gives it a great deal of leverage. However, it hasn’t used that leverage to build on its own balance sheet. Semiconductor manufacturers are veterans of the commodity world and carry the scar tissue of building capacity into a customer’s optimistic forecasts, so TSMC made the hyperscalers an offer instead: guarantee the capacity and the plants get built.
Having learned what dependence on a single supplier costs, they now have to fund that supplier’s competitors as well. This should eventually mean far more chips. It doesn’t mean better returns. The same supply that lowers the cost of a GPU lowers the price of a GPU hour, and the benefit passes to the customer. What it leaves behind is an asset bought at scarcity prices competing against capacity built at commodity prices. Hence the risk.
None of this is new to a capital-intensive industry. In 2013, with oil near $100, our current energy holdings reinvested nearly every dollar of operating cash flow, spent roughly twice their depreciation, and earned between 5% and 14% on capital. The market paid 15 to 52 times profit for that. By 2015, the risk was apparent. They had chased volume growth rather than return per barrel, and the oil price did not cooperate (sound familiar?). Pain was felt and lessons were learned. Those same companies now reinvest about 60% of cash flow, spend roughly what they depreciate, and most of them earn more at $75 oil than they did at $98.4
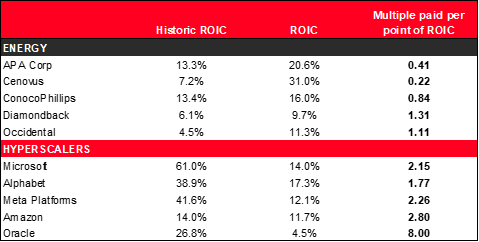
The exhibit below puts both groups against the same three questions: what did they earn, what do they earn now, and what does the market charge for each point of that return?
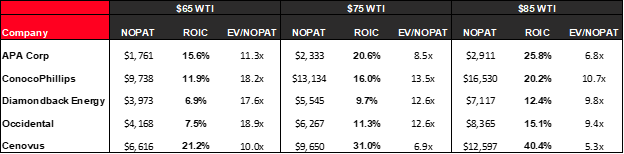
Our energy holdings trade at 7 to 14 times after-tax operating profit at $75 oil and still earn 7 to 21% on capital at $65, which is our bear case. They carry strong balance sheets, a mandate to earn a return on the marginal barrel instead of chasing volume and continued industry consolidation. At the other end of the table, 27 to 36 times profit buys businesses that have to double or triple their earnings simply to get back to the returns that justified those multiples in the first place.
We know which side of that table we want to own.
The last time an industry built the future, the technology survived and the financiers didn’t. This time, the hyperscalers are the financiers. We are well aware of what it costs to sit out a mania while it is still running. However, we would rather explain a few years of patience than a permanent loss of our investors’ capital.
The information contained in this missive represents Smead Capital Management’s opinions, and should not be construed as personalized or individualized investment advice and are subject to change. Past performance is no guarantee of future results. Seamus Sullivan, Senior Analyst, wrote this article. It should not be assumed that investing in any securities mentioned above will or will not be profitable. Portfolio composition is subject to change at any time and references to specific securities, industries and sectors in this letter are not recommendations to purchase or sell any particular security. Current and future portfolio holdings are subject to risk. In preparing this document, SCM has relied upon and assumed, without independent verification, the accuracy and completeness of all information available from public sources. A list of all recommendations made by Smead Capital Management within the past twelve-month period is available upon request.