Key takeaways
-
New vintage economics are improving. Recent redemptions from semiliquid direct lending vehicles have tightened financing conditions at the margin, helping lenders regain negotiating power. Newly originated loans now generally offer modestly wider spreads, lower leverage, larger equity cushions, and stronger debt-servicing capacity.
-
Bifurcation is likely to become more pronounced. Should these green shoots persist, new vintages will likely become more robust, while legacy portfolios will likely continue to bear the imprint of borrower-friendly terms from the peak deployment years. Elevated distress indicators and discounted public business development company (BDC) valuations suggest that credit losses, markdowns, and earnings pressure in older vintages have yet to fully run their course.
-
More frequent marks are not the same as price discovery. Wide dispersion in marks across BDC managers remains a key challenge for investors. Greater transparency and stronger valuation governance would help, but daily model-based marks cannot overcome private credit’s structural limits on observability, secondary market liquidity, and market-clearing transactions.
While redemption pressure in nonlisted BDCs (funds that invest in small and midsize private U.S. businesses) has eased from its peak, it remains materially above the industry standard 5% quarterly redemption threshold. As a result, capital continues to leave the asset class, forcing managers to look to preserve liquidity, moderate deployment, and, at the margin, tighten financing conditions.
The irony is that this tightening is beginning to create a growing distinction between the economics of new lending and the fundamentals embedded in existing portfolios.
See more: Anatomy of the Private Credit Market
The new vintage advantage
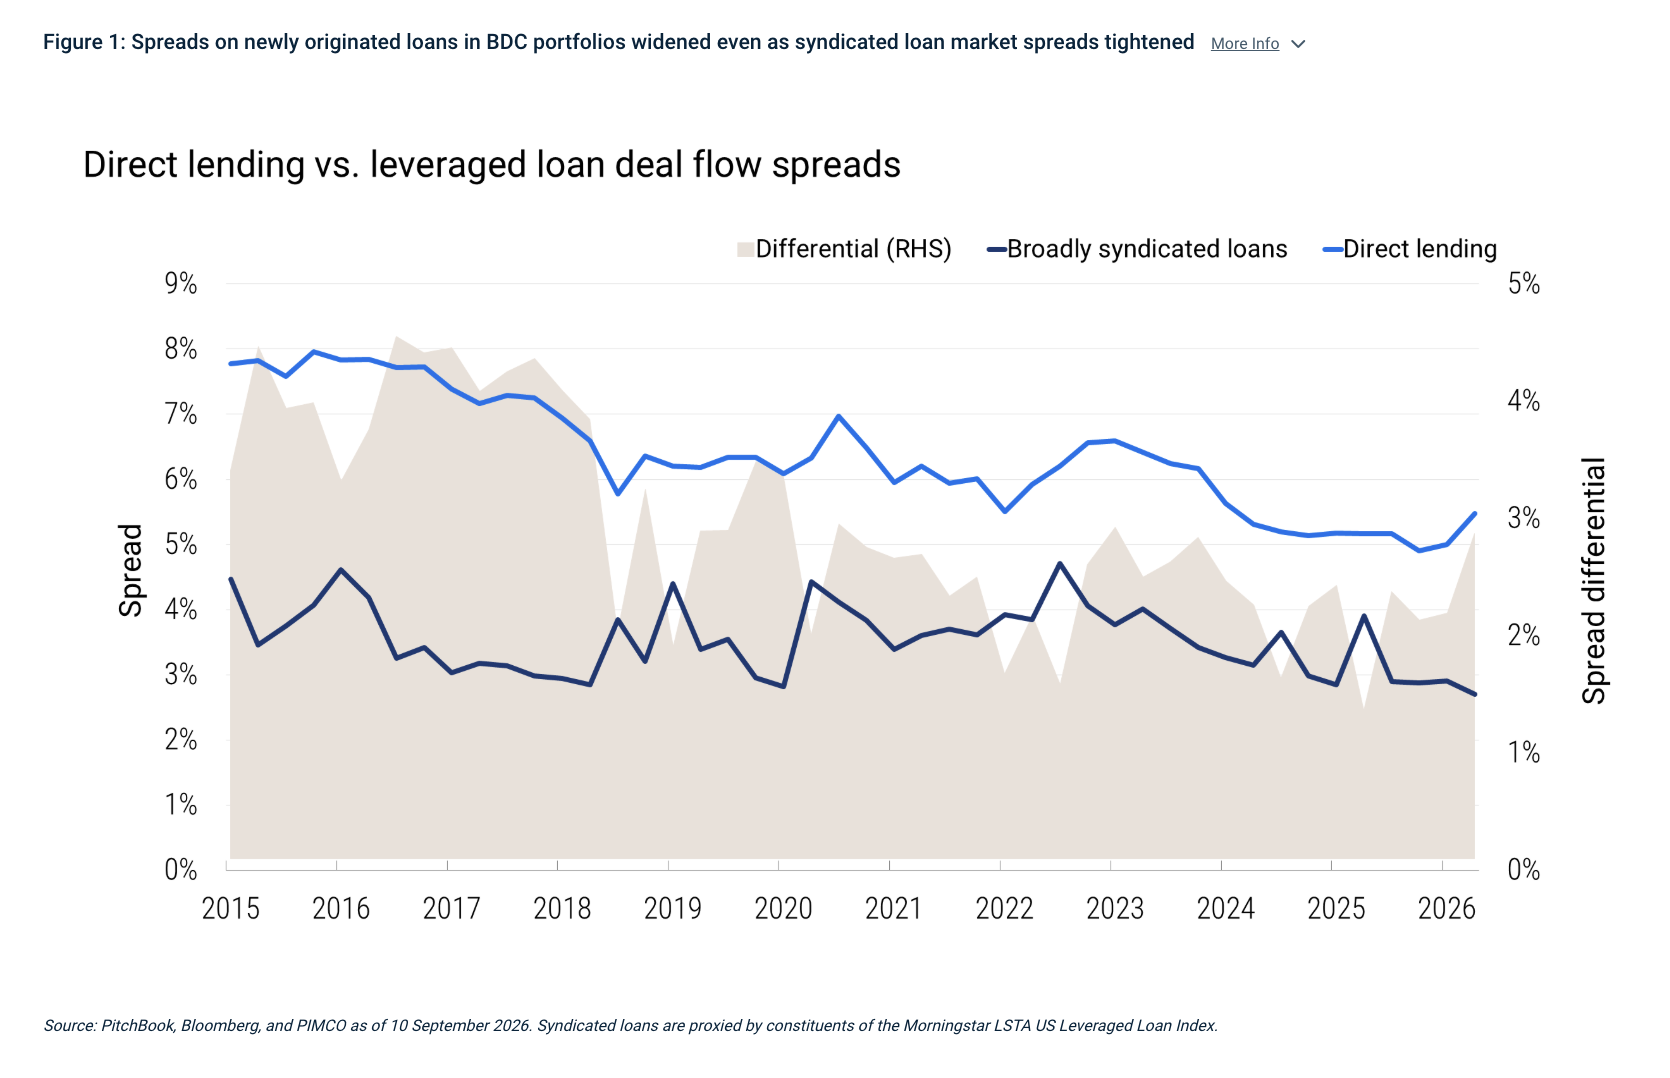
The divide between newly originated loans and the existing stock is becoming increasingly evident in underwriting standards. Spreads on new direct-lending loans have recently widened modestly even as spreads in the broadly syndicated loan market have tightened, increasing the relative compensation available to direct lenders (see Figure 1).
The adjustment extends beyond pricing. Lincoln InternationalFootnote1 reports that, for new loans issued in August 2026 to borrowers with $40 million – $100 million in EBITDA (earnings before interest, taxes, depreciation, and amortization), leverage levels declined versus the fourth quarter of 2025, while required equity cushions increased to 50% from 45%.
Similarly, KBRA DLDFootnote2 reports that interest coverage ratios on newly originated direct-lending loans reached 2.5x in the second quarter of 2026, the highest level since 2022, alongside improving fixed-charge coverage metrics.
In other words, the marginal dollar of capital is increasingly being deployed into loans with wider spreads, lower leverage, greater borrower equity support, and stronger debt-servicing capacity.
These developments point to a gradual improvement in the direct-lending opportunity set. After more than a decade in which abundant capital and intense competition produced increasingly borrower-friendly terms, the tide appears to be shifting at the margin. We see evidence of wider spreads, lower leverage, larger equity cushions, and stronger coverage ratios, which suggest that lenders are beginning to regain negotiating power.
Still, these are tentative green shoots rather than evidence of a regime shift. The trends will need to persist over the next several quarters before signaling a meaningfully different underwriting environment.
Even if the improvement proves durable, however, it is unlikely to change the trajectory of the broader asset class overnight. New vintages should benefit from wider spreads, more conservative structures, and stronger lender protections, potentially supporting better returns and credit outcomes. Legacy vintages – particularly those originated during the peak fundraising and deployment years – remain exposed to the tighter spreads, higher leverage, and weaker protections of a more borrower-friendly era.
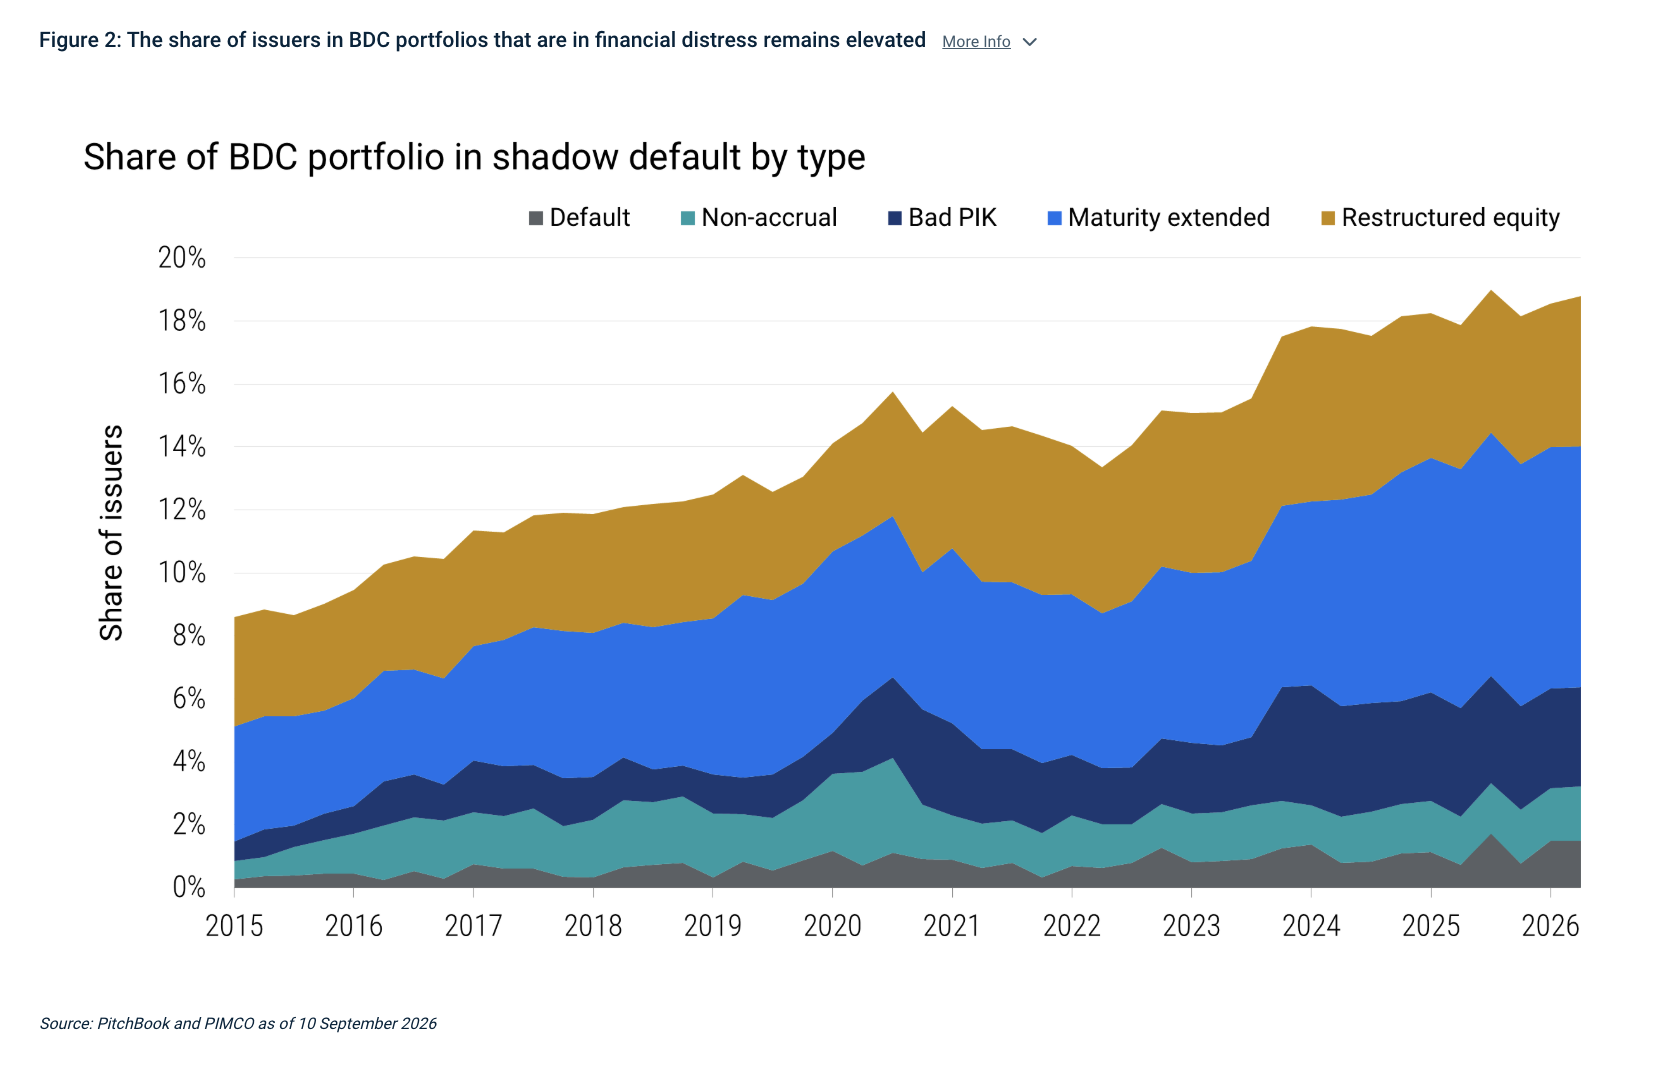
Measures of borrower distress remained near recent highs at the end of the second quarter, suggesting that the consequences of aggressive underwriting have yet to fully work through the system (see Figure 2). The result is an increasingly bifurcated market: Redemption-driven outflows remain a headwind for the asset class, even as the resulting tightening in financing conditions improves the opportunity set for new lending.
Marks still matter
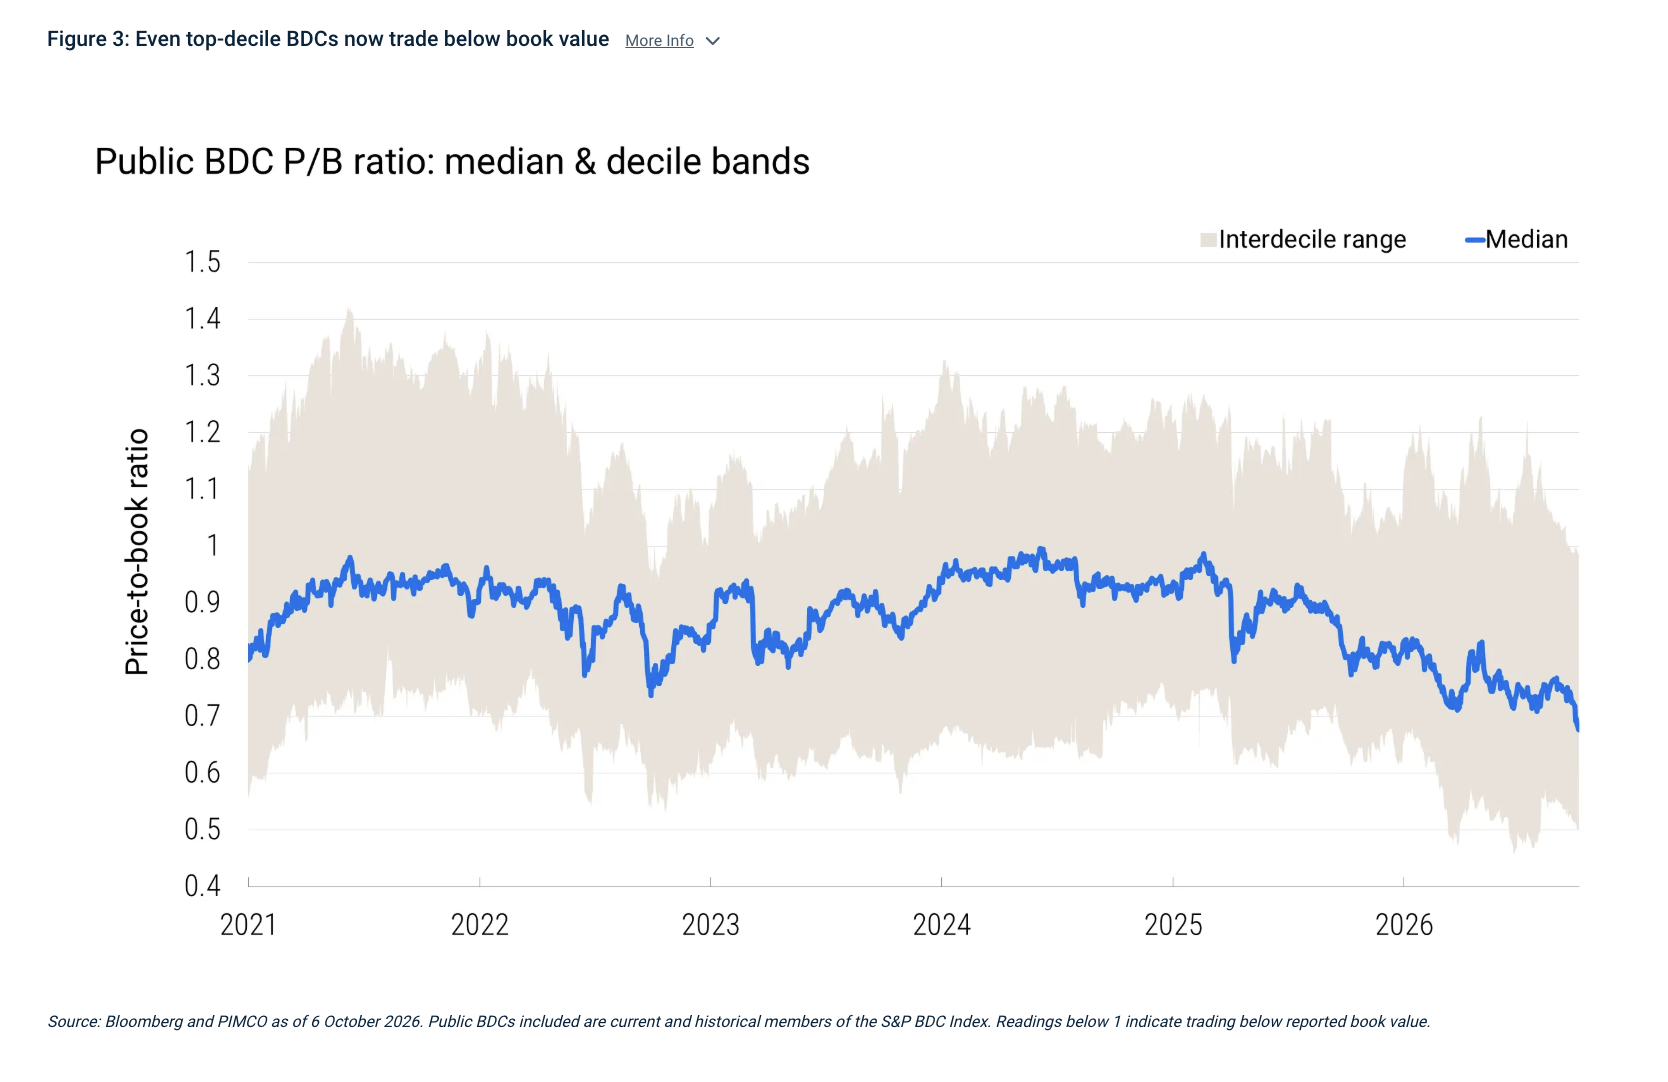
This potentially growing bifurcation makes credible valuation of the existing stock all the more important. Public market signals point in the same direction: Even the upper end of the public BDC valuation distribution continues to trade well below reported book value, suggesting that equity investors still assign some probability to future credit losses, portfolio markdowns, or weaker earnings power (see Figure 3).
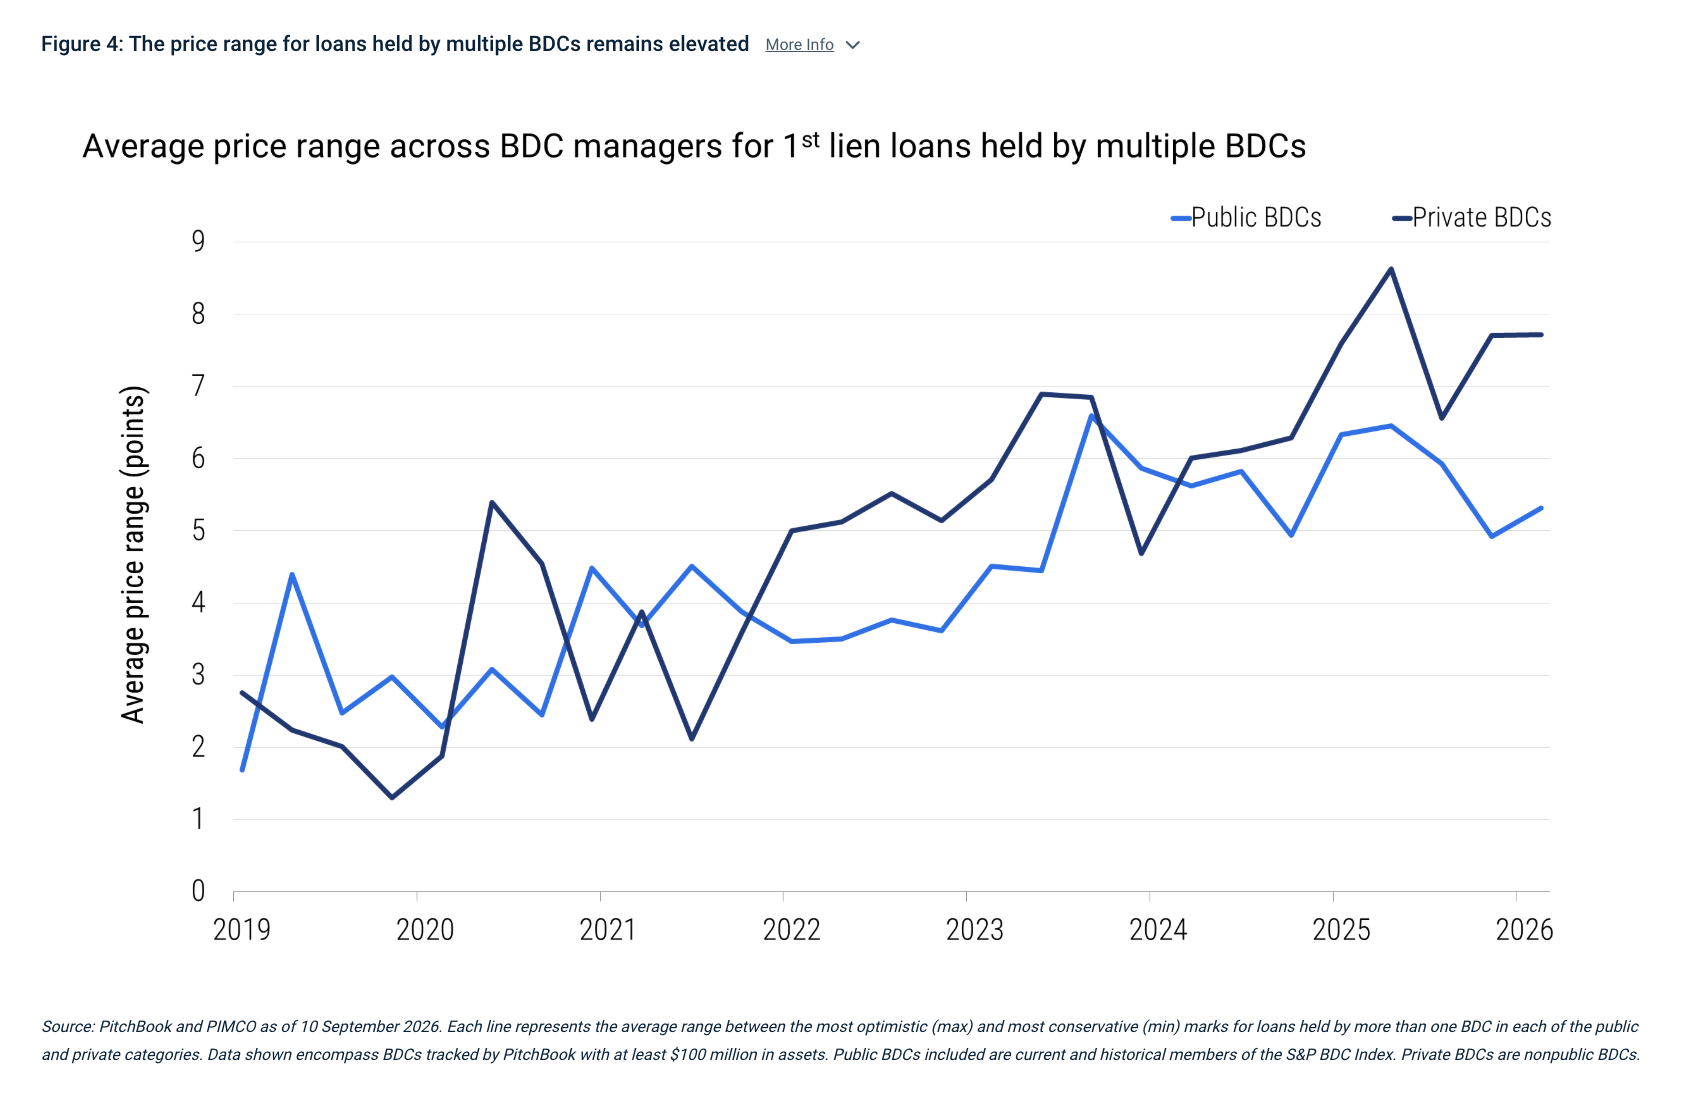
Investor skepticism is not solely about the direction of credit fundamentals. It also reflects persistent questions around valuation credibility. Dispersion in marks across managers remains elevated, with loans owned by multiple BDCs often carrying valuation differences of roughly six points (see Figure 4; this estimate is a weighted average across the public and private BDCs shown in the figure). Such gaps fuel concerns about manager-assigned valuations and make it difficult for investors to distinguish between genuine differences in portfolio quality and differences in marking practices.
We continue to view efforts to bring greater transparency to pricing as welcome developments. But the bar for meaningful improvement remains high. More frequent marks do not, by themselves, create price discovery. Producing daily valuations using model-based assumptions is simply a higher-frequency version of the same process that already generates wide dispersion across comparable assets when valuations are not anchored to observable market transactions.
The core issue is not the frequency of marks, but the absence of true price discovery and market-clearing transactions. Moreover, meaningful secondary market liquidity in private credit continues to face substantial structural obstacles, including limited standardization across instruments, operationally cumbersome settlement processes, transfer restrictions, information asymmetries, and the absence of the deep two-way sponsorship that underpins liquidity in public credit markets. These constraints make true secondary market liquidity a much higher bar than is often assumed (for more, see our 11 May 2026 commentary, “Daily Pricing Is Not Daily Liquidity”).
Michael Puempel and Gabriel Cazaubieilh contributed to this report.
Footnotes
1 Lincoln International, Market & Assumptions Overview, Q3 2026: Covering data through 1 September 2026, published 4 September 2026. ©2026 Lincoln Partners Advisors LLC. All rights reserved. LINCOLN PRIVATE MARKET INDEX, LINCOLN LENS PRIVATE MARKET INTELLIGENCE and LINCOLN INTERNATIONAL are service marks owned by Lincoln Partners Advisors LLC and its affiliated entities. Any use of these service marks and these materials, including the reproduction, modification, distribution or republication of these materials, without the prior written consent of Lincoln International, is strictly prohibited. Return to content↩
2 KBRA DLD Research Insights & Outlook, Private U.S. Sponsored Deals Analysis August 2026, published 10 September 2026. Return to content↩
Disclosures
Statements concerning financial market trends or portfolio strategies are based on current market conditions, which will fluctuate. Outlook and strategies are subject to change without notice.
Past performance is not a guarantee or a reliable indicator of future results. Forecasts, estimates and certain information contained herein are based upon proprietary research and should not be considered as investment advice. There is no guarantee that stated results will be achieved.
All Investments contain risk and may lose value. An investment in a business development company (BDC) is subject to credit and investment risk, leverage risk, market and valuation risk, price volatility risk, liquidity risk, interest rate risk and structural and regulatory risk. Broadly syndicated loans (BSL) involve interest rate and market risk, credit risk, default risk, liquidity, structural and legal risks. Private credit involves an investment in non-publicly traded securities which may be subject to illiquidity risk. Portfolios that invest in private credit may be leveraged and may engage in speculative investment practices that increase the risk of investment loss.
References to specific securities and their issuers are not intended and should not be interpreted as recommendations to purchase, sell or hold such securities. It is not possible to invest directly in an unmanaged index.
PIMCO as a general matter provides services to qualified institutions, financial intermediaries and institutional investors. Individual investors should contact their own financial professional to determine the most appropriate investment options for their financial situation. This material contains the opinions of the author and such opinions are subject to change without notice. This material has been distributed for informational purposes only and should not be considered as investment advice or a recommendation of any particular security, strategy or investment product. Information contained herein has been obtained from sources believed to be reliable, but not guaranteed. No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission. PIMCO is a trademark of Allianz Asset Management of America LLC in the United States and throughout the world.
CMR2026-1009-6008049
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© PIMCO
More Private Equity Topics >