Key takeaways:
- The consumer remains on solid footing despite building headwinds
- AI investment is likely to remain strong in the quarters ahead on robust demand
- Forward earnings estimates are supportive of the market
Third-quarter earnings season kicked off this week and expectations are high. Despite the headwinds of higher oil prices and interest rates, economic growth has remained resilient, while the AI investment boom continues to gain momentum. As a result, the S&P 500 is expected to deliver 29% year-over-year earnings growth, marking a third consecutive quarter of 25%+ gains. Notably, 2026 earnings estimates have risen 7.1% since the start of the quarter, defying the usual pattern of downward revisions. While hotter-than-expected inflation and recent semiconductor weakness have injected some volatility into the market, the broader backdrop remains constructive. Still, with expectations elevated, this earnings season will be an important test of whether corporate results can justify the strength of the broader economy. As we head into a busy eight-week stretch, here are the five key questions we're looking to answer.
Will the consumer remain resilient?
If the strong results from the mega-cap banks this past week are any indication, third-quarter 2026 earnings season should provide further evidence of a resilient consumer. Credit card spending remained robust at Citigroup (+13% year over year), Wells Fargo (+12% year over year), and JPMorgan (+10% year over year), while Delta Air Lines reported healthy travel demand despite higher airfares driven by surging crude oil prices. The key question is whether consumers can maintain that momentum as higher prices continue to pressure household budgets. So far, real-time indicators, including restaurant bookings, hotel occupancy, and department store spending, suggest demand remains solid. If that trend holds, it could provide a tailwind for the lagging consumer discretionary sector.
Will tech earnings stay on top?
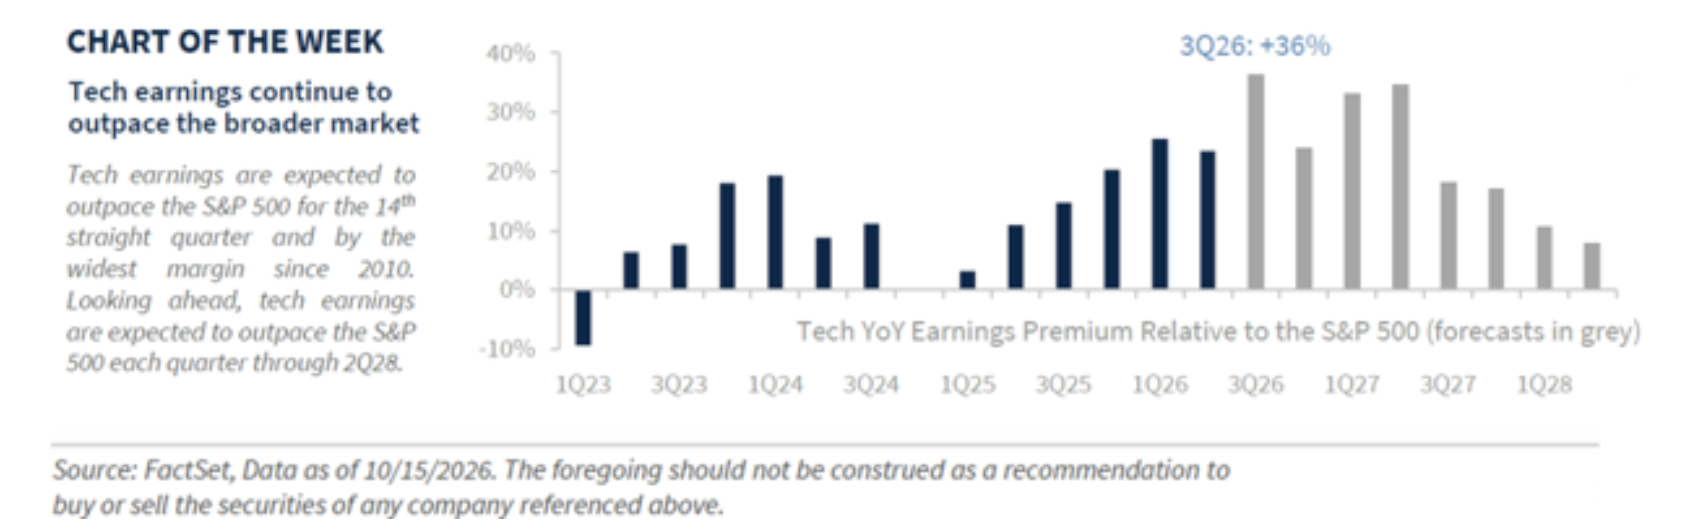
Tech earnings are expected to grow 64% year over year in 3Q26. While that's a modest slowdown from 73% growth in 2Q, it would still mark the 14th consecutive quarter of tech earnings outpacing the broader market, with the earnings premium (+36%) reaching its widest level since 2Q10. With tech margins 3x those of the rest of the S&P 500 and AI investment remaining on solid footing, tech earnings are expected to outgrow the S&P 500 each quarter through at least 2Q28. The key question is whether this earnings advantage can continue to support tech’s leadership as earnings growth moderates. We think it can. Constructive earnings, increasing shareholder-friendly activity and attractive valuations keep us overweight tech.
Can AI investment remain solid moving forward?
The slowdown in revenue growth at a major private AI company has raised questions about the staying power of the AI investment cycle. Given the scale of spending, those concerns are understandable. Still, the broader backdrop remains supportive. Hyperscalers remained capacity-constrained in 2Q26, and early 3Q26 supplier commentary points to the same trend, suggesting capex still has room to grow. Micron, for example, noted that demand for memory chips, a key AI input, continues to outpace supply. At the same time, AI adoption continues to broaden beyond tech. According to Ramp, business spending on AI reached a record high this week as 56% of businesses are now using AI, up from 44% a year ago. Adoption remains highest in the information sector (approximately 80% of firms), but other industries, such as accommodation and food (33%), health care (43%), and construction (43%), have increased AI usage by more than 10% over the past year. So, while volatility may remain elevated and headline-driven, the fundamentals still support strong hyperscaler spending and broader AI investment over the next 12 months. We expect that strength to show up in 3Q26 earnings and will be looking for clearer evidence that companies are translating AI investment into meaningful monetization.
See more: Q3 2026 Investment & Market Update