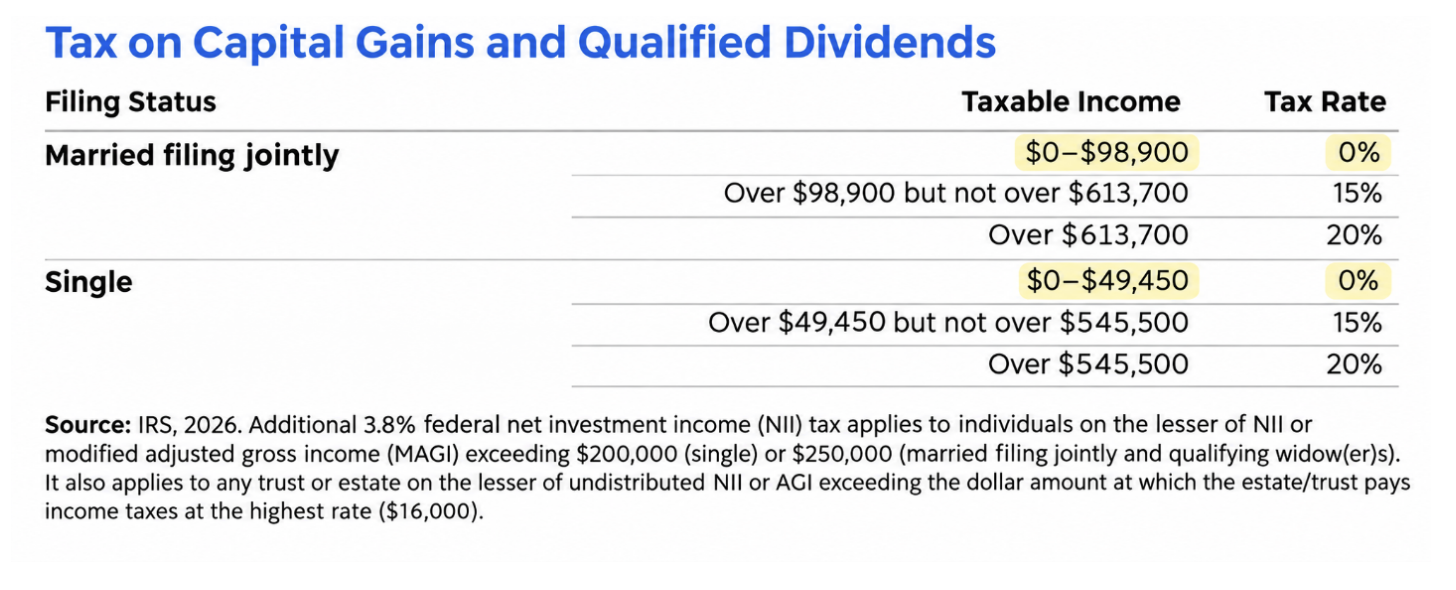
As year-end approaches, taxpayers have several planning opportunities to consider that may help reduce their overall tax bill. One often-overlooked opportunity is the 0% federal tax rate that applies to certain long-term capital gains and qualified dividends. For eligible taxpayers, this provision may offer an opportunity to realize investment gains before December 31 without incurring federal capital gains tax.
Taking Advantage of the 0% Capital Gains Tax Rate
The zero percent long-term capital gains tax rate may present an opportunity for taxpayers to realize investment gains while incurring little or no federal capital gains tax. By strategically managing income and recognizing gains in years when taxable income falls within the applicable thresholds, investors may be able to reduce the embedded tax liability in their portfolios.
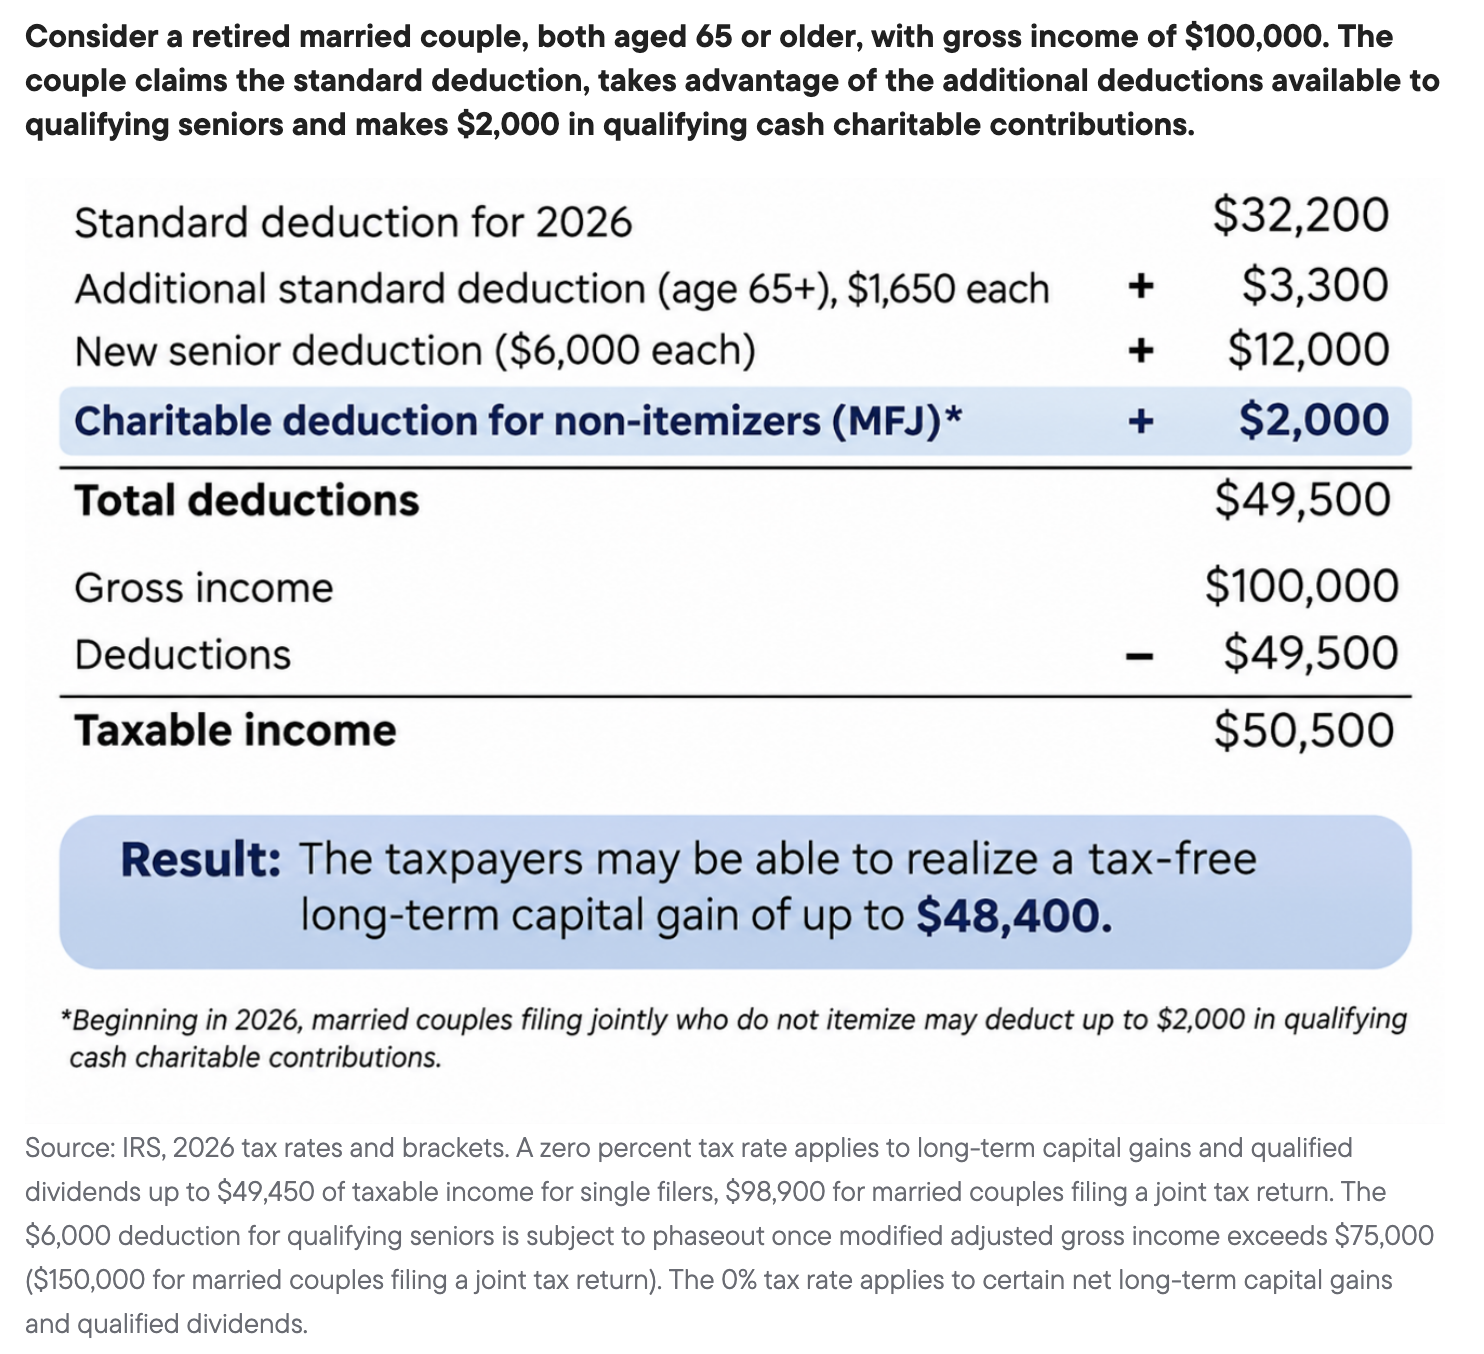
The One Big Beautiful Bill Act also introduced a charitable contribution deduction beginning in 2026 for taxpayers who do not itemize. Married couples filing jointly may deduct up to $2,000 in qualifying cash contributions, potentially creating additional room to realize long-term capital gains at the 0% federal tax rate.
The following example illustrates how this strategy may work:
Consider a retired married couple, both aged 65 or older, with gross income of $100,000. The couple claims the standard deduction, takes advantage of the additional deductions available to qualifying seniors and makes $2,000 in qualifying cash charitable contributions.
See more: Strong Jobs Report Reinforces Outlook and Market Rotation
As long as the couple in this example reports income at or below the threshold where the zero percent rate applies (taxable income of $98,900) there would be no federal tax on the long-term capital gain. At a 15% tax rate this results in a potential tax savings of almost $7,000. From a planning perspective, this is a use-it-or-lose-it opportunity for taxpayers who want to take advantage of the 0% capital gains rate before year-end. For those who intend to continue owning an appreciated investment, one strategy may be to sell shares to recognize the desired long-term capital gain and subsequently repurchase the investment. However, one should consider the potential for market price movement during the period between the sale, repurchase and trading costs, as even a short time out of the market could affect investment returns. Unlike tax-loss harvesting, the wash sale rule does not apply to sales resulting in a gain. Therefore, investors can generally repurchase the same security immediately without jeopardizing the recognized gain. Taxpayers should consult with qualified investment and tax professionals before considering this type of strategy.
Bill Cass, Director of Wealth Planning
WHAT ARE THE RISKS?
All investments involve risks, including possible loss of principal.
Any information, statement or opinion set forth herein is general in nature, is not directed to or based on the financial situation or needs of any particular investor, and does not constitute, and should not be construed as, investment advice, forecast of future events, a guarantee of future results, or a recommendation with respect to any particular security or investment strategy or type of retirement account. Investors seeking financial advice regarding the appropriateness of investing in any securities or investment strategies should consult their financial professional.
Franklin Templeton, its affiliated companies, and its employees are not in the business of providing tax or legal advice to taxpayers. These materials and any tax-related statements are not intended or written to be used, and cannot be used or relied upon, by any such taxpayer for the purpose of avoiding tax penalties or complying with any applicable tax laws or regulations. Tax-related statements, if any, may have been written in connection with the “promotion or marketing” of the transaction(s) or matter(s) addressed by these materials, to the extent allowed by applicable law. Any such taxpayer should seek advice based on the taxpayer’s particular circumstances from an independent tax advisor.
Important Information
This material is intended to be of general interest only and should not be construed as individual investment advice or a recommendation or solicitation to buy, sell or hold any security or to adopt any investment strategy. It does not constitute legal or tax advice. This material may not be reproduced, distributed or published without prior written permission from Franklin Templeton.
The views expressed are those of the investment manager and the comments, opinions and analyses are rendered as at publication date and may change without notice. The underlying assumptions and these views are subject to change based on market and other conditions and may differ from other portfolio managers or of the firm as a whole. The information provided in this material is not intended as a complete analysis of every material fact regarding any country, region or market. There is no assurance that any prediction, projection or forecast on the economy, stock market, bond market or the economic trends of the markets will be realized. The value of investments and the income from them can go down as well as up and you may not get back the full amount that you invested. Past performance is not necessarily indicative nor a guarantee of future performance. All investments involve risks, including possible loss of principal.
Any research and analysis contained in this material has been procured by Franklin Templeton for its own purposes and may be acted upon in that connection and, as such, is provided to you incidentally. Data from third party sources may have been used in the preparation of this material and Franklin Templeton ("FT") has not independently verified, validated or audited such data. Although information has been obtained from sources that Franklin Templeton believes to be reliable, no guarantee can be given as to its accuracy and such information may be incomplete or condensed and may be subject to change at any time without notice. The mention of any individual securities should neither constitute nor be construed as a recommendation to purchase, hold or sell any securities, and the information provided regarding such individual securities (if any) is not a sufficient basis upon which to make an investment decision. FT accepts no liability whatsoever for any loss arising from use of this information and reliance upon the comments, opinions and analyses in the material is at the sole discretion of the user.
Franklin Templeton has environmental, social and governance (ESG) capabilities; however, not all strategies or products for a strategy consider “ESG” as part of their investment process.
Products, services and information may not be available in all jurisdictions and are offered outside the U.S. by other FT affiliates and/or their distributors as local laws and regulation permits. Please consult your own financial professional or Franklin Templeton institutional contact for further information on availability of products and services in your jurisdiction.
Issued in the U.S. by Franklin Templeton, One Franklin Parkway, San Mateo, California 94403-1906, (800) DIAL BEN/342-5236, franklintempleton.com. Investments are not FDIC insured; may lose value; and are not bank guaranteed.
You need Adobe Acrobat Reader to view and print PDF documents. Download a free version from Adobe's website.
CFA® and Chartered Financial Analyst® are trademarks owned by CFA Institute.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Franklin Templeton
More Innovative ETFs Topics >