Key takeaways
- Year-end funding pressures may create an opportunity for institutions with excess cash. Dealer balance sheet constraints have historically pushed equity financing premiums higher during December.
- Cash-and-carry offers a potential source of incremental return without materially increasing directional equity exposure. The strategy seeks to earn the financing premium embedded in equity derivatives.
- The opportunity depends on execution and liquidity. Institutions with existing passive equity investments may have a relatively straightforward implementation route, provided the net financing premium justifies the trade.
What is an equity cash-and-carry strategy?
An equity cash-and-carry strategy allows investors to seek additional return on excess cash by purchasing physical equity exposure, such as an ETF, and simultaneously selling corresponding equity index derivatives, such as futures or total return swaps. The positions largely offset directional equity market movements, allowing investors to earn the implied financing premium embedded in derivatives pricing.
See more: A Crowded Exit? A Discussion on the Yen Carry Trade
For institutions with substantial cash balances, the strategy offers an alternative to leaving capital in conventional cash investments while they consider longer-term allocations. With the December futures roll approaching, the potential to earn additional financing income deserves attention.
Why year-end could create more opportunity
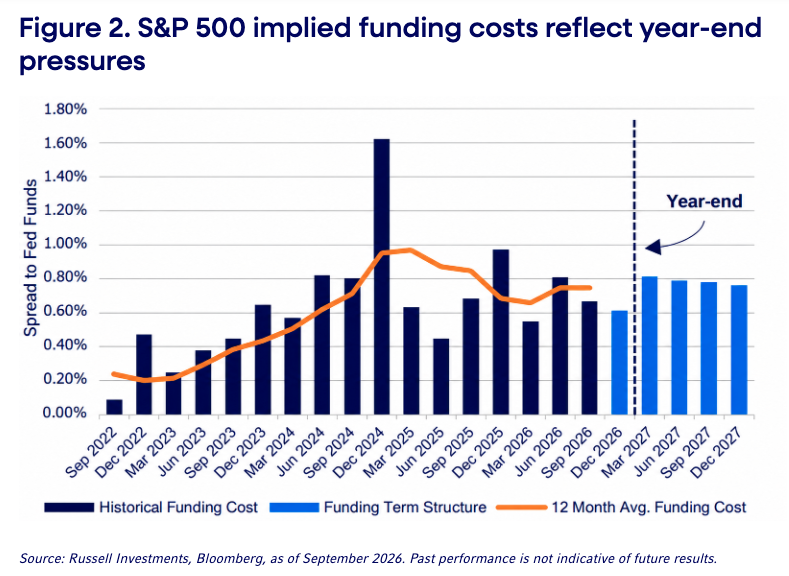
Equity financing premiums reflect demand for long synthetic equity exposure relative to the financing capacity available from dealers. Banks face regulatory constraints on the balance sheet they can commit to these positions, particularly around year-end reporting dates. When demand exceeds available supply, futures can trade above theoretical fair value, creating an opportunity for investors positioned to provide financing.
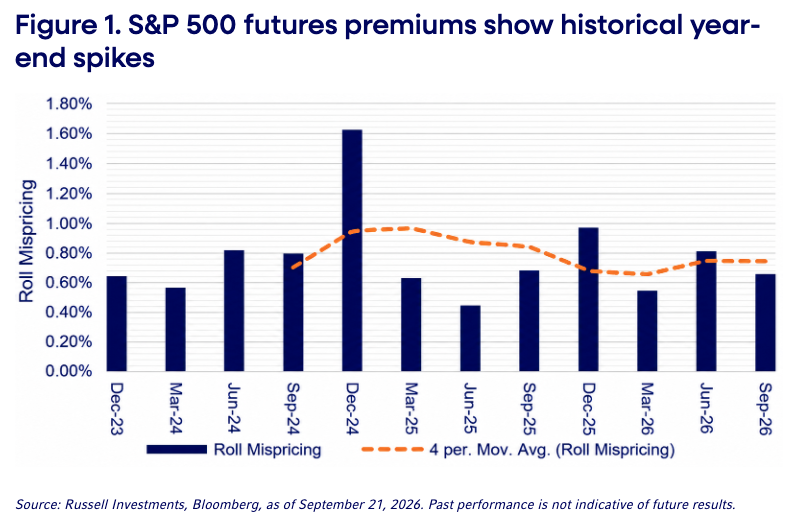
Recent analysis from our derivatives trading desk illustrates the pattern. S&P 500 futures traded at annualized premiums of 162 basis points to fair value in December 2024 and 97 basis points in December 2025.¹ Both periods reflected elevated financing costs as dealers managed year-end balance sheet constraints.
The June 2026 roll demonstrated how other demands on dealer capacity can amplify the imbalance. S&P 500 futures traded unusually rich for a non-December cycle, with financing pressures potentially exacerbated by the SpaceX IPO. The September roll was more subdued, with the S&P 500 futures premium moderating to 67 basis points, compared with 81 basis points in June.²
The contrast helps explain why December deserves attention. Although September funding levels moved closer to historical averages, year-end balance sheet constraints could again limit dealer financing supply.
The direction of equity markets will also influence demand. Continued equity strength could support long synthetic exposure, while a sell-off and deleveraging could narrow or eliminate the premium. Investors considering cash-and-carry should therefore evaluate available financing spreads rather than assume another December spike.
How cash-and-carry can enhance returns on excess cash
For institutions holding substantial liquidity, the appeal of cash-and-carry is the ability to earn an attractive yield on their cash with minimal credit risk.
Recent year-end funding spikes have offered approximately 50–100 basis points of additional annualized return over conventional cash investments, before implementation costs. On a $100 million allocation, a 50-basis-point enhancement sustained for a full year could generate approximately $500,000 in additional income.
The strategy can be particularly relevant when an institution is evaluating other uses for excess liquidity. A public pension fund considering an allocation to high yield credit, for example, may find value in committing a portion of its cash to a market-hedged financing strategy.
The return profiles differ. High yield credit introduces credit spread and default risk, while cash-and-carry seeks a financing premium with diminutive equity exposure. The appropriate allocation depends on the institution's return objectives and liquidity needs.
Implementation: Align the trade with the institution's liquidity needs
For institutions already invested in low-cost passive equity funds, implementation may be relatively straightforward. Additional capital can be allocated to the existing fund while an offsetting short synthetic position is established through an overlay program. Investors without an appropriate passive allocation may instead purchase a low-cost index ETF and sell corresponding derivatives.
These are two common implementation approaches, though other structures may be appropriate depending on the institution’s needs. The right approach depends on the investor's existing holdings and ability to coordinate execution.
The physical and synthetic positions should be established and closed together to limit slippage. Market-on-close execution can help align the trades, whereas mismatched execution prices can introduce variability in the strategy’s return.
Liquidity requirements also influence suitability. Institutional portfolios with stable excess cash may be better positioned to maintain cash-and-carry positions for longer, allowing them to earn the financing premium over a more extended period. Institutions whose cash supports near-term spending, capital commitments, or operating requirements may have less capacity to absorb liquidity demands and therefore require an early unwind. Unwinding the trade early risks closing out the derivatives at less favorable implied funding levels.
Although the positions largely offset equity market exposure, short derivatives can generate increased variation margin or collateral obligations during an equity rally. Investors must maintain sufficient liquidity to meet those requirements and evaluate the net financing return after transaction costs.
The cash-and-carry strategy would not be appropriate for an institutional portfolio with limited capacity to meet additional cash demands. During an equity rally, additional cash would be required to cover mark-to-market losses on the derivatives. If those cash requirements became too burdensome, the portfolio might have to unwind the trade early—potentially at higher implied funding levels, making the exit more costly.
For institutions positioned to act, preparing for a potential year-end funding spike allows time to evaluate available capital, execution arrangements, and the financing premium required to justify implementation. Year-end conditions may create more attractive pricing, but the strategy should only be established when the economics align with the institution's liquidity needs and objectives.
Investor implications
Equity cash-and-carry offers institutions with stable excess liquidity a potential source of incremental return tied to demand for synthetic equity financing. Historical year-end funding pressures create a timely reason to evaluate the opportunity.
Investors should focus on executable net spreads and coordinated implementation while preserving liquidity for other obligations. Preparing ahead of the roll provides flexibility to act if financing premiums become attractive.
1 Data point is from Bloomberg and Russell Investments. Equity funding premiums are reported in annualized terms. Standard S&P 500 futures are rolled quarterly and subject to variability in implied financing. Estimated premiums assume equity funding remain constant and the position is held for one year. Altering the holding period or the entry/exit points will result in a different return.
2 Bloomberg
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
The information, analyses and opinions set forth herein are intended to serve as general information only and should not be relied upon by any individual or entity as advice or recommendations specific to that individual entity. Anyone using this material should consult with their own attorney, accountant, financial or tax adviser or consultants on whom they rely for investment advice specific to their own circumstances.
Products and services described on this website are intended for United States residents only. Nothing contained in this material is intended to constitute legal, tax, securities, or investment advice, nor an opinion regarding the appropriateness of any investment, nor a solicitation of any type. The general information contained on this website should not be acted upon without obtaining specific legal, tax, and investment advice from a licensed professional. Persons outside the United States may find more information about products and services available within their jurisdictions by going to Russell Investments' Worldwide site.
Russell Investments is committed to ensuring digital accessibility for people with disabilities. We are continually improving the user experience for everyone, and applying the relevant accessibility standards.
Russell Investments' ownership is composed of a majority stake held by funds managed by TA Associates Management, L.P., with a significant minority stake held by funds managed by Reverence Capital Partners, L.P. Certain of Russell Investments' employees and Hamilton Lane Advisors, LLC also hold minority, non-controlling, ownership stakes.
On July 2, 2026, Russell Investments Group, Ltd. (“Russell Investments”) entered into a definitive agreement and plan of merger (the “Transaction”) pursuant to which Russell Investments will be acquired by a consortium led by B Capital Group Management, L.P. that includes California Public Employees Retirement System. The Transaction is expected to close by the end of Q1 2027, subject to the receipt of regulatory approvals and other customary closing conditions.
Frank Russell Company is the owner of the Russell trademarks contained in this material and all trademark rights related to the Russell trademarks, which the members of the Russell Investments group of companies are permitted to use under license from Frank Russell Company. The members of the Russell Investments group of companies are not affiliated in any manner with Frank Russell Company or any entity operating under the "FTSE RUSSELL" brand.
© Russell Investments Group, LLC. 1995-2026. All rights reserved. This material is proprietary and may not be reproduced, transferred, or distributed in any form without prior written permission from Russell Investments. It is delivered on an "as is" basis without warranty.
© Russell Investments
Read more commentaries by Russell Investments