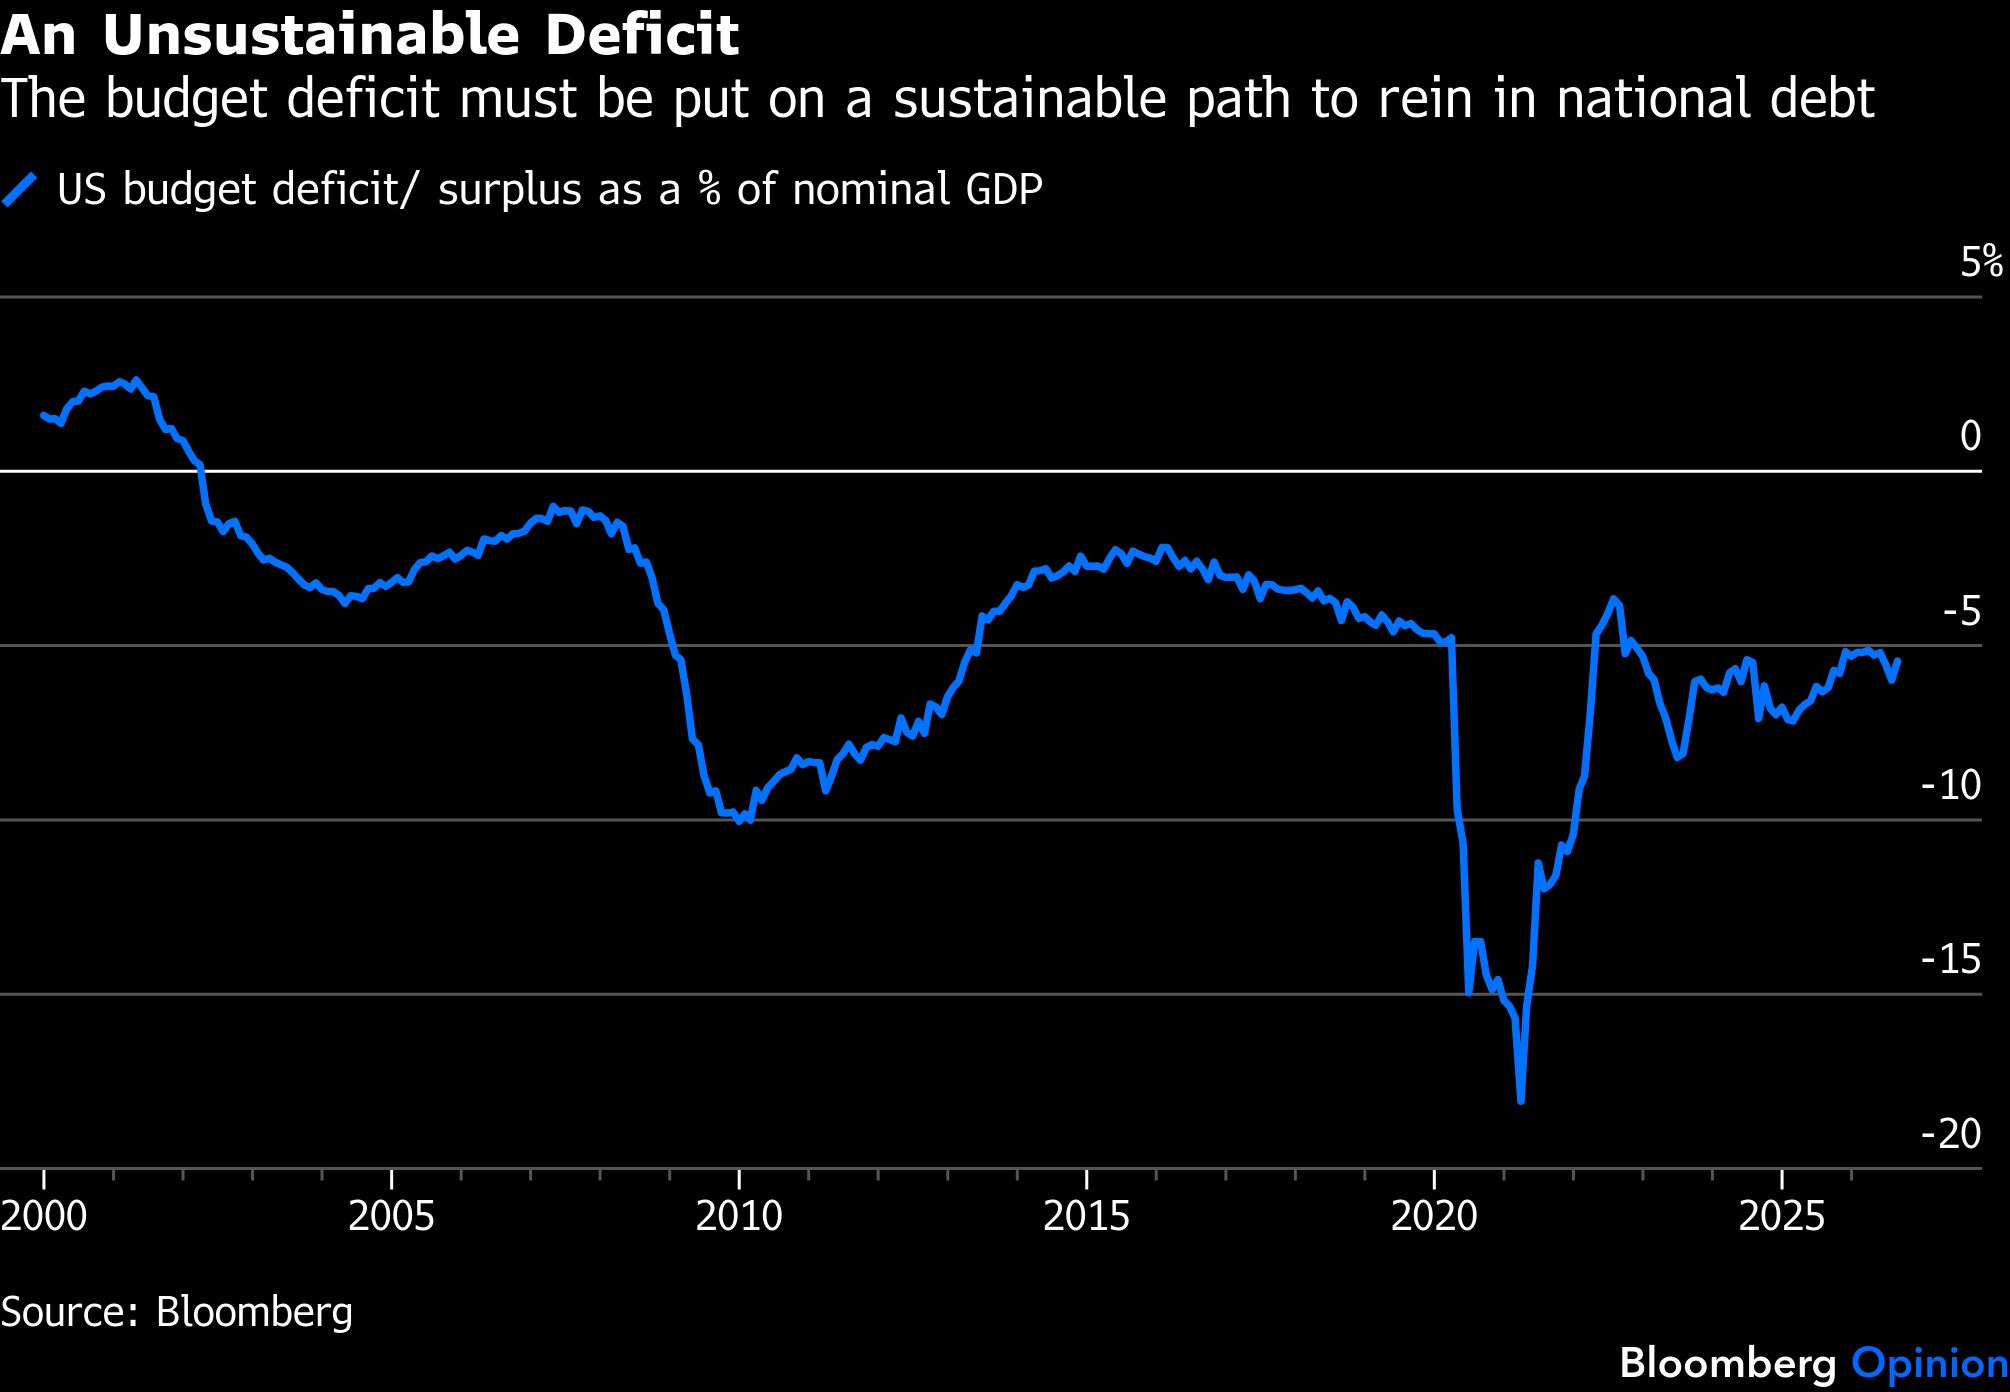
The US deficit has reached $1.97 trillion and is on track to pass 6% of gross domestic product this fiscal year, the latest milestone in a remarkable deterioration of the federal budget. With national debt at a record $40 trillion, the feeling that the music must stop at some point has jittery market watchers zeroed in on a jittery bond market.
Running high deficits when the economy is strong makes it more difficult, and more expensive, to spend what’s necessary during a recession, which will inevitably come. High public debt also lowers private savings, increases borrowing costs for everyone and adds hefty interest payments to government spending. The benefit is that it enables large economic investments — pay now to grow later — but our borrowing is mainly financing current consumption.
How do we get out of this?
See more: US Debt Trap: A Crisis Without A Calendar
We must change direction, stepping off the unsustainable course and moving on to a sustainable one. Cue Republicans saying we should cut spending, Democrats saying we should raise taxes, and no solution emerging. How about we start with that secret third thing — tax spending. It’s where the money is anyway.

This is technically called tax expenditure, defined in the Congressional Budget and Impoundment Control Act of 1974 as revenue lost to exclusions, exemptions, deductions, credits and deferrals in the tax code. In other words: all the coupons we dole out through the tax system, everything from the mortgage interest deduction and child tax credit to bonus depreciation.
These coupons will total $2.3 trillion this year. If you keep count, that’s larger than federal Medicaid ($700 billion in 2026) and Medicare ($1.2 trillion in 2026) — combined. It’s 50% more than Social Security ($1.5 trillion in 2026). If they were a program, tax coupons would be the largest the federal government has in its portfolio, by a comfortable $800 billion margin.
If their size makes them an easy target, their composition makes them a tough one.
There are 271 distinct tax coupons across personal and corporate income taxes. They range from the smallest 100 or so, which don’t even have a cost estimate, to the biggest three: the tax exemption for retirement savings, the tax exemption for employer-sponsored health insurance and the tax discount given to income from capital gains and dividends. Despite boasting the largest three, the personal income tax has fewer coupons than the corporate tax.
There were about 130 tax coupons in the 1980s and 1990s. The blossoming of discounts since then is endemic to the tax-cut era that we are in.
This century has seen two sizeable and permanent reductions in tax revenue. First came the “temporary” tax cuts of 2001, which were expanded a half dozen times, extended once, and made permanent in 2012 in the American Taxpayer Relief Act. Next came the “temporary” tax cuts of 2017, which were made permanent in the One Big Beautiful Bill Act of 2025.
So much legislative action in tax cuts, as opposed to inaction in just about every other sphere, means policy that should have shown up as spending or regulation wound up in the tax code. It’s why, for example, rather than amend the Fair Labor Standards Act to increase the tipped minimum wage and give a raise to every tipped worker, the Trump administration instead created the tip credit. Or why, instead of amending the Social Security Act to change the tax on benefits, there’s a new deduction for seniors.
This is expensive. The 2012 cuts adjusted for inflation work out to $550 billion a year in lost revenue and the 2025 cuts drained $450 billion a year. A combined trillion-dollar haircut came from changes to rates and bases, and a much thicker coupon book.
It’s also expensive to Americans. The price of ‘tax preparation and accounting services’ has grown cumulatively more than 200% since 2000, more than double overall price growth and averaging 4.5% a year. There are probably some Americans for whom the reduction in taxes is less than the increase in the cost to prepare them.
The sprawling complexity of our tax code is a handicap that puts any discussion of our fiscal health four strokes down. Say, for example, Congress increases marginal rates to raise revenue, the coupon book is like an opaque protection racket that concentrates the burden of higher taxes on those not lucky enough to have a discount already. That only creates pressure for more discounts. It’s that great combination you’re looking for in federal policy: ineffective, unfair and self-propelling.
Tax reform — actual tax reform — must make the tax code simpler. That starts with evaluating each of the 271 discounts and assessing if there is a more efficient or effective way to meet the needs of the population or policy being served. Does this benefit have to go through the tax code? Is it incumbent on tax payers to provide it? If no, get it off the books.
The wages of tipped workers, for example, are the responsibility of the businesses who employ those workers and profit from their labor. Get rid of the tipped credit and raise the tipped minimum wage via labor law. Iterate through all 271 coupons.
If this sounds like an incredibly onerous and complex task, keep in mind, I’m proposing that Congress do a better job at its primary job — that shouldn’t feel like a reach. And for whatever purpose it’s been co-opted, the primary role of the tax system is to raise revenue. There’s no question we need it to do better.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
Read more articles by Kathryn Anne Edwards