Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.
Think interest rates are peaking? If so, agency mortgage-backed securities (MBS) deserve a look. Think rates have further to climb? MBS may still earn a place in your fixed-income allocation, potentially offering more yield than Treasuries with essentially no credit risk.
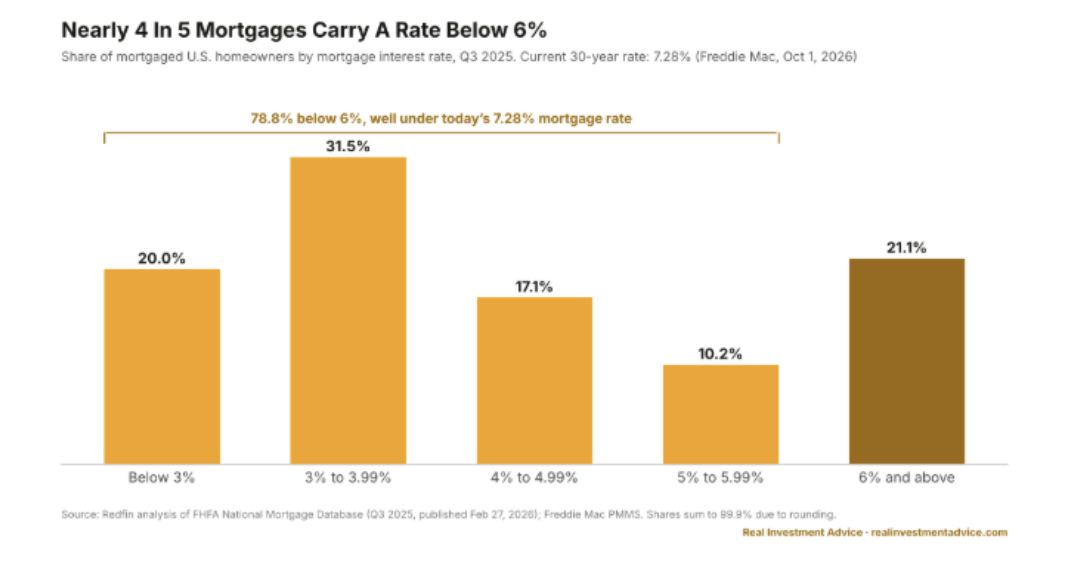
Here is the twist. In 2022 and 2023, MBS investors learned a painful lesson. As rates surged, homeowners stopped refinancing, and MBS durations rose at the worst possible time. Today, that dynamic has largely run its course. With 30-year mortgage rates at 7.25% and nearly 80% of homeowners with a mortgage holding a rate below 6%, refinancing has all but stopped, leaving MBS durations little room to extend further. The feature that hurt MBS investors in 2022 and 2023 has little room for further harm.
MBS are a unique type of bond because mortgagees can prepay part or all of their mortgage at any time without penalty. This means that MBS investors, who have essentially lent the mortgagees money, are inherently short a prepayment option. The prepayment option accounts for much of the extra yield MBS offer over Treasuries, as well as their greater interest rate risk. But when the risks are limited, MBS holders are often in an advantageous position.
In this article, I weigh the pros and cons of MBS at current yields, explain what will drive future returns, and share how individual investors can gain exposure.
Setting the Stage
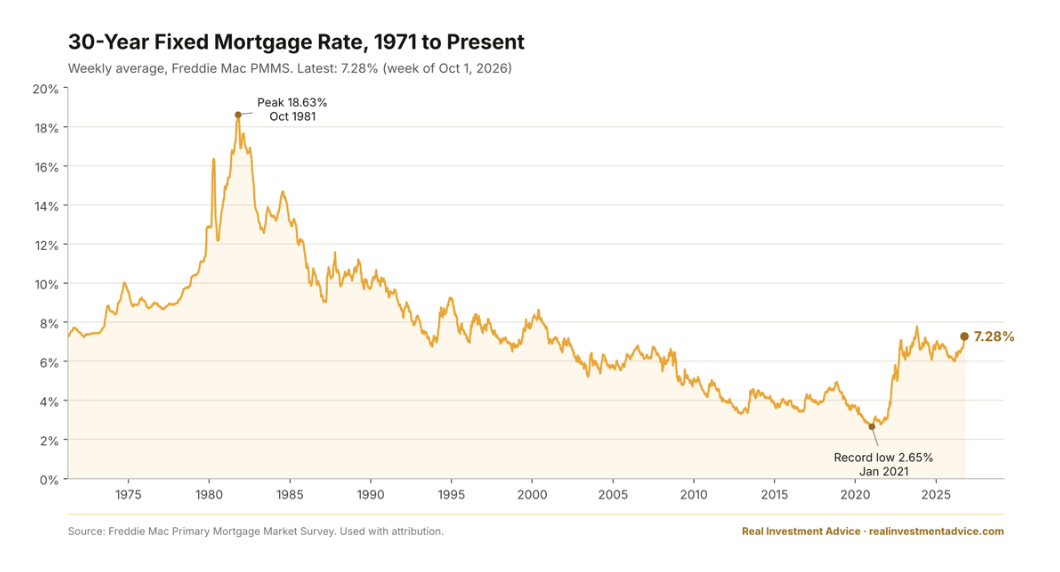
Mortgage rates and Treasury yields have moved sharply higher over the last six months. Per Freddie Mac, the average 30-year fixed mortgage rate was 7.28% as of October 1, the highest since November 2023, and up from 6.34% a year ago.
The graph above shows that virtually all mortgages that originated in the early 2000s have a rate below the current rate. Accordingly, refinancing activity has dried up.
Furthermore, the Mortgage Bankers Association (MBA) reported that its refinance index is over 50% below what it was a year ago. Joel Kan of the MBA said, “Mortgage rates jumped to their highest level in almost three years, pushing borrowers to the sidelines.”
The iShares MBS ETF (MBB), a reasonable proxy for the agency MBS index, holds securities with a weighted average coupon of 3.63%, roughly 3.50% below the current mortgage rate. With most mortgages at least 2% below current rates, very few homeowners have an economic reason to refinance.
In bond terminology, mortgagees’ prepayment option is worth little. To better understand why this matters for MBS investors, let's focus on MBS duration.
Understanding MBS Duration
Duration measures a bond’s price sensitivity to changes in interest rates. A bond with a duration of seven years should lose about 7% of its value if yields rise by 1%, and gain about 7% if yields fall by 1%. For Treasury, municipal, and corporate bonds, duration is fairly predictable because their interest and principal cash flows are fixed.
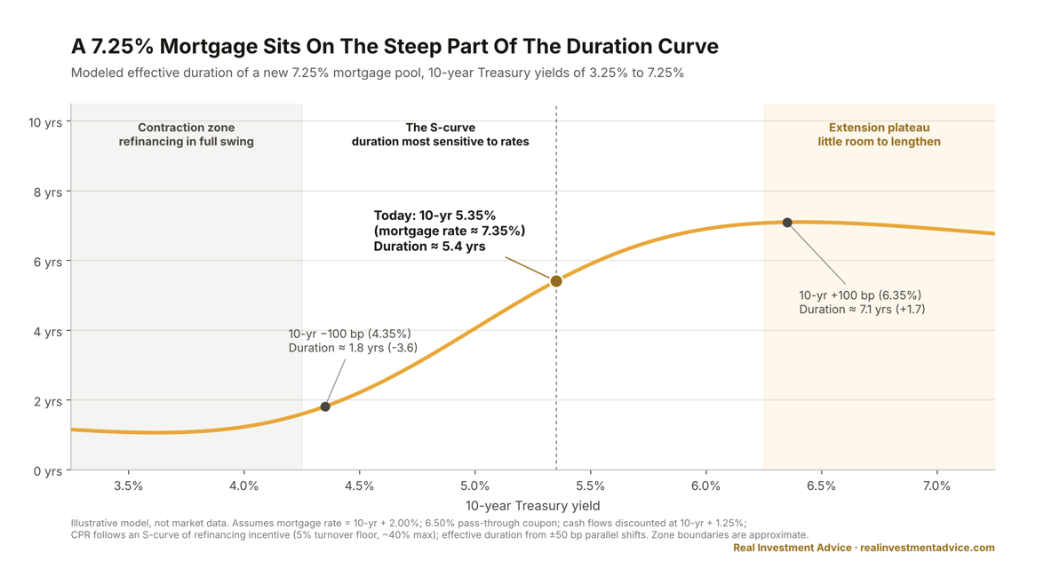
MBS investor cash flows depend on when and by how much homeowners pay down their mortgages, which depends largely on interest rates. Therefore, changes in interest rates have a much more profound impact on MBS durations than Treasury and corporate durations.
MBS investors track effective duration, a model-based duration estimate that accounts for how prepayments are expected to change as rates move.
- When rates rise, refinancing slows and cash flows are pushed further into the future, extending duration.
- When rates fall, refinancing accelerates and principal comes back sooner, shortening duration.
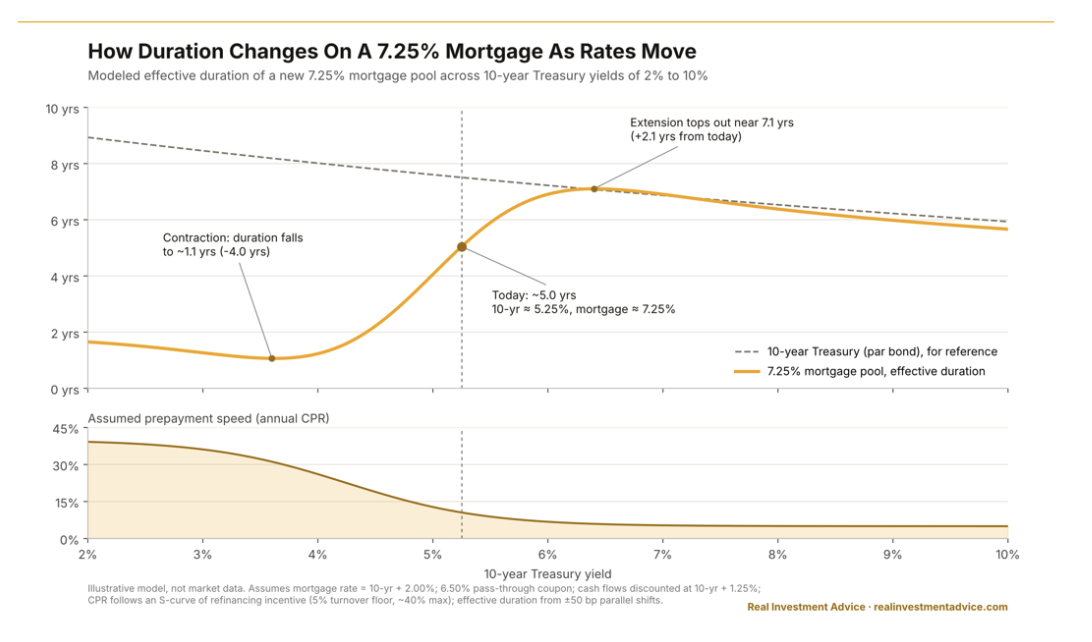
The graph below shows a hypothetical comparison of MBS and Treasury durations for a range of Treasury yield levels. Note how quickly MBS duration changes when rates are between 4% and 6%. At the same time, note the relatively flat, downward-sloping Treasury duration once rates are above 6%. The lower graph shows that refinancing activity is highly sensitive to rate changes when 10-year Treasury yields are in the 4% to 6% range.
Coping With Duration Shifts — Negative Convexity
The graph above shows that MBS rate exposure tends to shift in the wrong direction at the wrong time for investors. For instance:
- Duration increases when yields rise, so price losses are greater than they would have been if duration had remained constant.
- Duration declines when falling rates would otherwise produce larger price gains, had duration remained constant.
Those negative consequences are called negative convexity.
This all means that the stated duration of an MBS or a portfolio of MBS is a snapshot, not a constant. Investors should expect it to change as rates change and watch where current mortgage rates sit relative to the point at which homeowners can profitably refinance.
Extension Risk Is Largely Spent
Extension risk, or rising duration, has been harming MBS investors since rates started rising in late 2021. As rates rise, refinancing slows, the expected life of the mortgage pool lengthens, and duration increases precisely when investors least want greater duration. MBS holders acutely felt the negative convexity in 2022 and 2023.
Today, despite the recent rate increase, much of that duration extension has already occurred. When a mortgage pool is deeply out of the money, or not economically refinanceable, as many are today, prepayments are driven almost entirely by factors unrelated to interest rates such as:
- Home sales
- Scheduled amortization of principal
- Defaults, which, for agency MBS, return principal at par
- Cash-out refinancing, which is limited at current rates
These and other sources of principal repayment create a floor under prepayment speeds.
Today, prepayments can't slow much more; thus, further rate increases would not extend duration much. Put differently, MBS investors buying today are taking on duration that is relatively capped on the upside. Accordingly, the risk/reward for MBS looks more balanced than it did a few years ago.
The Con: The Double Whammy If Rates Fall
The flip side of limited duration extension risk is the MBS problem when rates decline. If mortgage rates fall meaningfully, higher-coupon pools face two penalties at once:
- Principal that is earning higher rates and is returned through prepayments must be reinvested at lower rates.
- Duration shortens. As refinancing accelerates, the expected life of the MBS declines, capping price appreciation relative to a comparable Treasury.
This is the cost of the prepayment option MBS investors essentially sold to homeowners. The extra yield they earn over Treasuries is the premium investors are paid for bearing it.
The Silver Lining to the Double Whammy
Within the double whammy — negative convexity — lies a potential reward in today’s market. If mortgage rates fall to 5%, over two-thirds of mortgages, as I share below, have no financial incentive to refinance.
For most of the MBS market, falling rates in the recent environment are a good thing:
- Refinancing will be slow to kick in, so duration declines should be minimal and investors can capture much of the price benefit of lower yields.
- Faster prepayments become a gain. Lower rates tend to boost home sales, and every sale pays off a loan at par. For MBS trading below par, each dollar returned early is profit pulled forward.
Bear in mind it's not just the low number of high-rate loans that will likely limit prepayments when rates fall. Refinancing takes months — borrowers must notice the lower rates, shop lenders, and close loans. Furthermore, given the lack of recent refinancing and home-sale activity, lender capacity could become a bottleneck if applications surge.
Many borrowers never refinance. Some lack the credit score or home equity to qualify, some have balances too small to justify closing costs, and others simply do not act. As a result, investors continue to collect above-market coupons on the loans that remain.
Falling rates can be very beneficial to MBS holders given today’s backdrop.
How to Invest in MBS
For institutional investors, the agency MBS market is one of the deepest and most liquid fixed income markets in the world. Owning individual MBS is ideal in theory. It allows investors to choose the coupon, vintage, and prepayment characteristics that best fit their views. However, in practice, several factors make it challenging and impractical for smaller investors:
- Pools factor down. Every month, a portion of principal is returned. A $100,000 position may be $60,000 within a few years, and small, odd-lot positions trade at meaningful discounts to larger pools.
- Monthly principal must be reinvested. Small, irregular cash flows are difficult to put back to work efficiently.
- Prepayment analysis requires data and models that most individual investors do not have.
- Dealer access and pricing transparency for small trades are limited.
For these reasons, an ETF or mutual fund may be a more practical option for smaller investors. Funds handle reinvestment, maintain diversification across coupons and vintages, and benefit from professional management, institutional models, and lower trading costs.
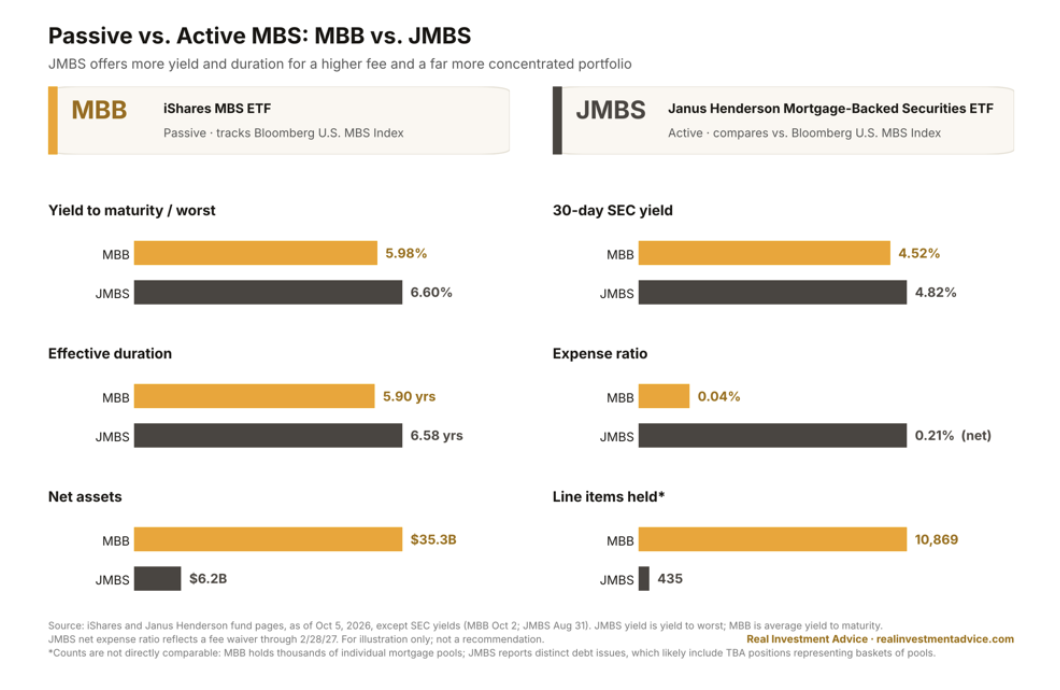
Passive ETFs such as MBB offer broad index exposure at a low cost; its expense ratio is 0.04%. Actively managed MBS funds, such as JMBS, can shift their holdings toward coupons and specified pools that managers believe offer better convexity profiles, albeit at higher fees.
Investors should review a fund’s coupon distribution, effective duration, and use of leverage or derivatives. Two funds with similar durations can behave differently.
The graphic below compares the most popular passive MBS ETF, MBB, to the largest active ETF, JMBS.
Summary: Investment Thesis
A bullish thesis rests on two key points. First, interest rates stabilize and start to fall.
Second, even if rates rise, the duration shift is largely capped, as the graph below shows. Accordingly, assuming MBS-to-Treasury spreads do not change, the price change between an MBS and a similar-maturity Treasury will not be that indifferent.
Three years ago, extension risk was the reason to avoid MBS. Today, it is one reason to own them. With most mortgages far below market rates, MBS duration has little room left to extend. Investors are left with an asset class that offers high yields, minimal credit risk, and stable duration.
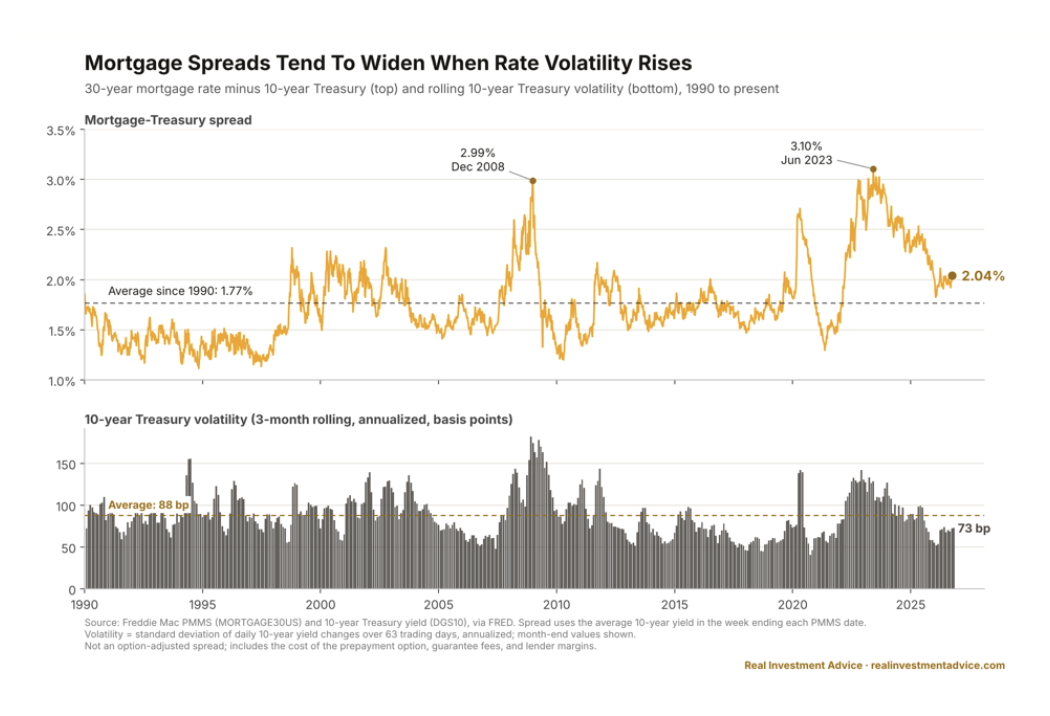
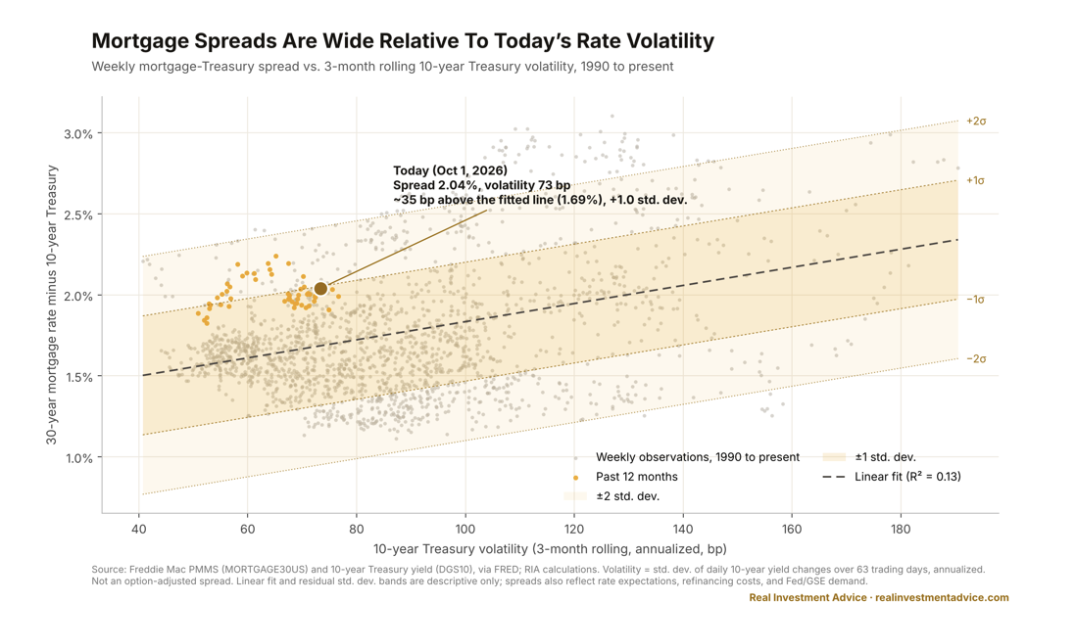
Thus far, I haven’t discussed how MBS spreads relate to Treasuries. Think of the spread, or yield difference, as the cost the investor receives for selling the prepayment option to the mortgagee. MBS investors want spreads to tighten or fall.
The two graphs below show that spreads are wider than normal and, excluding the financial crisis and sharp uptick in yields during 2022 and 2023, are near 35-year highs. Thus, if Treasury yields stabilize or decline, we should expect the spread to fall, benefiting MBS holders over Treasury investors.
The more compelling part of the thesis is what happens if rates fall. Bond investors are conditioned to fear MBS in a falling-rate environment. However, most homeowners currently have little or no financial incentive to refinance, and those who do will take their time. As a result, MBS durations should decline slowly, allowing investors to capture price gains while continuing to collect a yield premium over Treasuries for longer than many expect.
There is a potential kicker. If rates fall because the Fed is cutting rates and the yield curve is positively sloped, MBS holders benefit from reduced duration by “rolling down” the yield curve. While lower durations reduce potential price gains, MBS are valued at the lower yields of short-duration Treasury bonds, which adds a return benefit that a flat curve would not provide.
Put simply, investors choosing between Treasuries and MBS should consider MBS. They receive higher yields, face limited additional extension if rates rise, and stand to benefit if rates fall.
The prepayment option remains the key risk.
Read more by Michael Lebowitz:
- Worried Consumers Keep Spending: Here's Why
- From TINA To TIGA: Diversification Pays Again
- Japan Disproved the “Debt Causes Inflation” Narrative
Michael Lebowitz is a portfolio manager with RIA Advisors and author for Real Investment Advice. For more information, contact him at [email protected] or 301.466.1204.
Join RIA Advisors and elevate your career within a deeply experienced team focused on innovation. Our collaborative environment is built on a foundation of advanced technology and effective investment models, designed to enhance your ability to serve clients and grow your practice. Benefit from a supportive culture that encourages professional development and fosters a forward-thinking approach. By joining our team, you’ll be part of a group dedicated to excellence and continuous improvement, empowering you to focus on building meaningful client relationships and pursuing your business ambitions. Discover the advantages of working with our accomplished advisory team by starting your conversation today.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
More Factor-Based Investing Topics >
 Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.