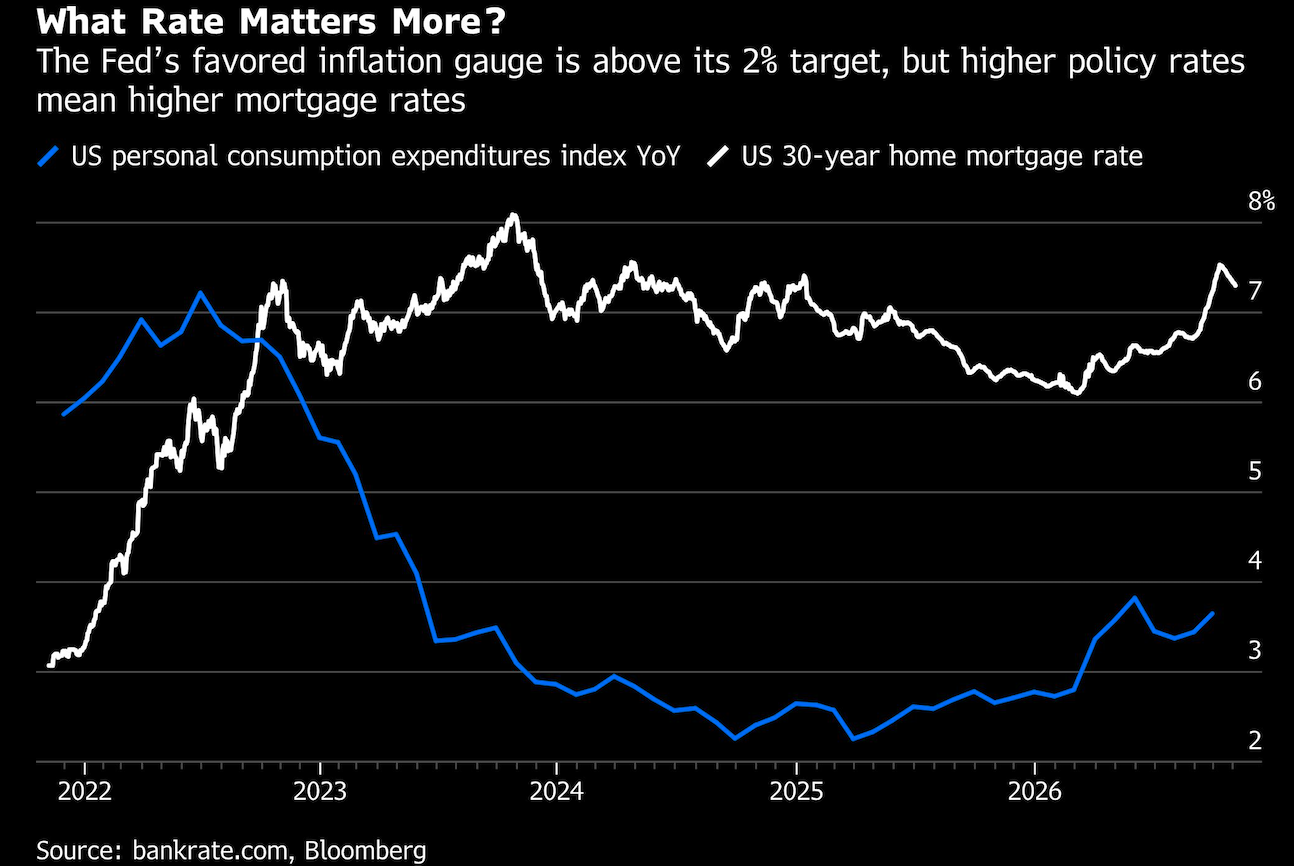
The big message from the midterms is that Americans are struggling with the cost of living. In case anyone missed it, they need relief now. This will put even more attention on the Federal Reserve: Will Chair Kevin Warsh do all he can to bring down inflation or placate the White House, which wants lower interest rates?
These are the wrong questions to ask. The solutions to affordability don’t lie with the Fed and its blunt interest-rate tool; they lie with Congress, which has two years to engineer real relief before the ballot box is back in play. The economy does not have an inflation problem, but it does have an affordability problem. These are separate issues because high prices today are about too little supply.
The latest inflation reading was a 3.6% increase in the price level. Apollo Global Management Inc. Chief Economist Torsten Slok estimates the Fed would need to take its policy rate up another 2.75 percentage points to 6.75% to get inflation to its 2% goal. That’s too much. The economy may be running a bit hot right now, which could justify a few rate increases, but it’s not overheating to the degree where such an aggressive approach makes sense, not even to hit the Fed’s target.
Many of the high prices in the economy today are tied to supply constraints: There’s insufficient housing, healthcare provision and energy supply and a dearth of migrant workers, plus the impact of tariffs. These are factors beyond the Fed’s control.
There are also structural forces at work that could result in a higher inflation rate even under the best of circumstances. An aging population means more consumers and fewer workers. And even before tariffs, we had been pulling back on trade, countering decades of globalization that lowered prices by making production more efficient and adding more low-cost labor to the mix. These trends point to the type of inflation that the Fed will struggle to arrest.
If they act forcefully, policymakers risk a serious recession with little benefit. Former Fed Chair Paul Volcker took the economy into recession in the 1980s to bring inflation down from more than 13%. Inflation is now just under 4% — high but manageable. A recession today could be even worse for American households than the current inflation rate.

See more: Do Bond Investors Get Rewarded for Taking Duration Risk? (Part 1)
Outside of technology, many sectors are already struggling with a 4% policy rate environment. Going higher may bring significant job losses or firm failures. Even tech has a point where borrowing costs start to bite. A big drop in stocks, which 60% of Americans hold, would wipe out significant household wealth. And mortgage rates would rise, probably well above 8% or 9%.
Perhaps it is all worth it to relieve households struggling with affordability. But households are suffering because of the price of energy, healthcare and housing, which are all supply driven. Higher rates may worsen the lack of affordability by increasing consumer borrowing costs and reducing inflation-adjusted wages from job loss and slower growth.
What about Fed credibility? Economists believe one reason inflation was so low for so long is because Volcker embedded among businesses and consumers a belief that the Fed had the will and ability to fight inflation. This baked low inflation into price increases and pay raises long into the future.
Arguably, though, the Fed has not had that credibility for some time. Inflation was below 2% for years after the global financial crisis and has been above it in the post-pandemic world. The one constant has been outside-of-target inflation. Besides credibility is relative. People might still believe the Fed will fight inflation at very high levels — say more than 5% — but will tolerate more modest deviations.
The more prudent way to make life cheaper for Americans is expanding goods and services. This is a harder problem that involves real trade-offs and lots more deregulation. It will also require the jubilant Democrats to take the opposite approach to their current messaging, which centers on extending benefits to a larger share of the population. These subsidize demand and restrict supply.
What we need is more supply. More housing where people want it, taking on voters who resist change in their neighborhoods. Congress can offer state and local governments incentives to allow the private sector to build more homes and make money on those investments — even private equity. More energy. There is already a bipartisan permitting bill that will weaken environmental regulations and make it easier to raise power and energy production — but it forces Democrats to contend with the environmental lobby. More healthcare. We could increase slots in medical schools, or make it easier for foreign doctors to practice in the US. And we can cap the tax deduction employers get for providing health insurance; removing that market distortion could mean higher wages instead of Cadillac benefits but will require taking on labor unions.
It seems easier to look to the Fed or give people more benefits to pay for the limited services we have. But we’ve reached our limit with stoking demand to grow the economy. We must now take on constrained supply and that will mean embracing the market and risk, and rejecting special interests.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
More Innovative ETFs Topics >