Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.
Our article, "Think Rates Are Peaking: Consider Mortgage-Backed Securities," explored mortgage-backed securities (MBS) as a lesser-understood fixed-income option for those who think interest rates are peaking and may head lower. Given the interest we've received, it's worth exploring non-fixed-income alternatives to owning Treasury, corporate, and municipal bonds.
The recent rise in yields presents an opportunity to earn a respectable return while reducing risk in a stock portfolio. At current yields, many investors are happy locking in bond income. Others may want exposure to bond yields but are wary of owning bonds.
For investors in the second camp, the stock market currently offers more options than usual. Many stocks across S&P sectors are more sensitive to Treasury yields than at almost any time over the past five years. Before digging deeper, it helps to understand why gaining exposure to bonds in today’s yield environment can improve your odds of reaching your financial goals.
Risk Management: 3 Points or 7?
Diversification entails accepting a lower potential return in exchange for a higher probability of achieving your ultimate financial goal. A recent NFL game illustrated a risk management decision investors face today.
On October 8, 2026, the Tampa Bay Buccaneers led the Dallas Cowboys 24-10 with 8:36 remaining. The Buccaneers' offense faced fourth-and-goal from the one-yard line. A chip-shot field goal would have made it 27-10, a three-score game that would have forced Dallas to score three times, including at least two touchdowns, in under nine minutes. Instead, Tampa Bay went for the touchdown and failed. Dallas got the ball and quickly drove 99 yards to make it a one-score game, leaving them plenty of time to score again and tie.
Despite their poor fourth-and-goal decision, Tampa Bay won 24-16. The field goal would have significantly increased the odds of winning. Reaching for the slightly better outcome, a touchdown, could have easily turned a high-probability win into a loss.
Investors face a similar scenario today. The five-year Treasury yields about 4.75%. If yields fall by a percentage point, the one-year return is roughly 9.2%. Yields would have to rise about 1.10% before a buyer loses money over the year. Furthermore, an investor who holds to maturity locks in 4.75% a year. Stocks may do better than 4.75% annually over the next five years, but an investor already ahead in the race to fund retirement does not need to maximize the margin. They need to avoid losing.
If you're in a financial position to kick the field goal and lock up a victory but are afraid to buy bonds, the following analysis can help.
Measuring the Bond Exposure Inside a Stock
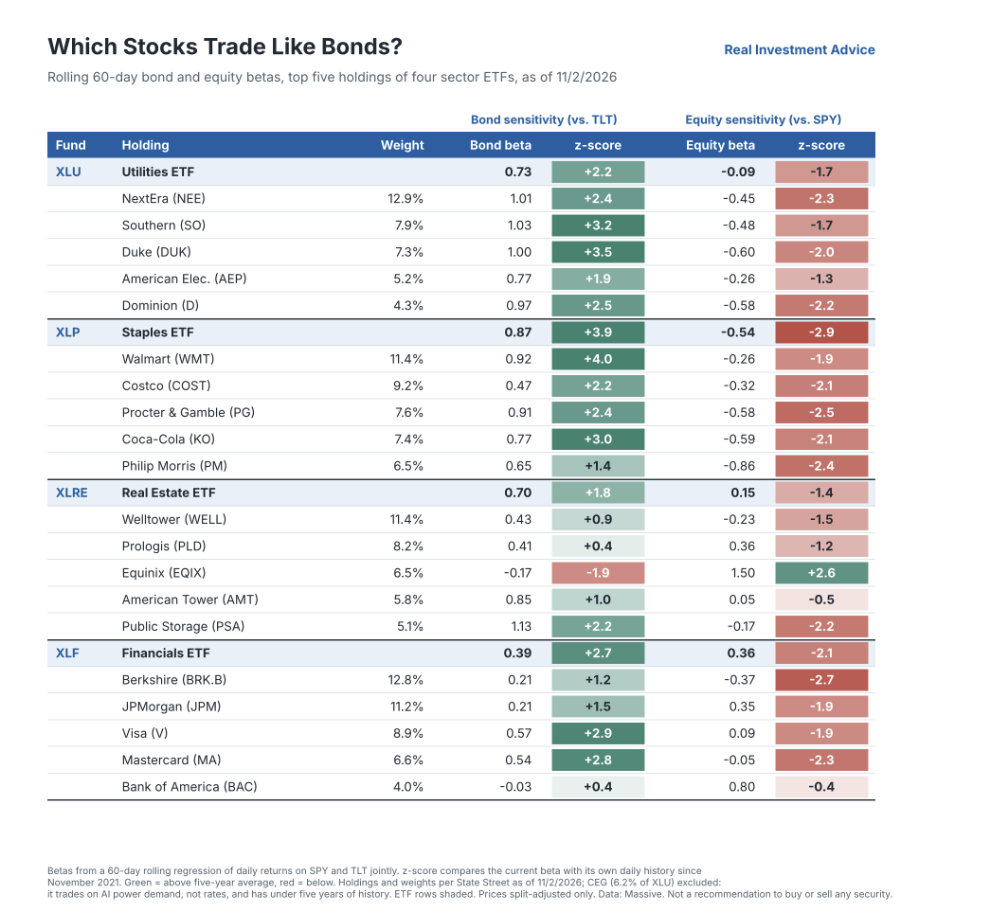
To quantify a stock or ETF's sensitivity to the equity market relative to its sensitivity to interest rates, we regressed the daily returns of four interest rate-sensitive sector ETFs and their five largest holdings against the S&P 500 (SPY) and 20-year UST Notes (TLT).
The following bullet points support the analysis in the table below:
-
Window: Betas were calculated using a rolling 60-trading-day window, based on daily data from November 2021.
-
Bond beta: The expected percentage move in a stock for a 1% move in TLT, holding SPY constant.
-
Equity beta: The expected move for a 1% move in SPY, holding TLT constant.
-
Z-score: The figure statistically measures how far today's beta sits from its own five-year average, measured in standard deviations. For context, readings of one standard deviation or more, in either direction, should occur about a third of the time. Readings of two standard deviations or more should occur roughly once a month. A three-standard-deviation reading should occur about once every year and a half.
TLT has a duration of roughly 16 years. Therefore, a 10-basis-point rise in long-term yields would reduce TLT's price by about 1.6%. A stock with a 0.6 bond beta would then be expected to fall roughly 1% (0.6 × 1.6%). The opposite holds true if yields decline.
What the Table Tells Us
Across the 20 stocks, 19 have bond betas above their five-year averages, and 19 have equity betas below. In other words, most of the stocks are behaving more like bonds and less like stocks than they typically do.
Staples: XLP's bond beta of 0.87 is nearly four standard deviations above its five-year average. Within the sector, Walmart (+4.0) and Coca-Cola (+3.0) are among the most extreme readings on the table.
Utilities: Southern, Duke, AEP, NextEra, and Dominion carry bond betas between 0.77 and 1.03, and all five have negative equity betas. Duke (+3.5) and Southern (+3.2) are more than three standard deviations above normal.
Real Estate: Public Storage and American Tower have bond betas of 1.13 and 0.85, while Prologis is 0.41. Equinix, a data center REIT, has an equity beta of 1.50 and a slightly negative bond beta. Rates matter for REITs, but they explain only part of the price action.
Financials: Banks typically benefit from higher yields, so their bond betas tend to run near zero or below in an environment like today. However, JPMorgan, Visa, and Mastercard have positive bond betas that are 1.5 to 2.9 standard deviations above normal, and XLF's bond beta z-score is +2.7. Bear in mind that banks' profit margins depend partly on the shape of the yield curve, in addition to overall yields.
Betas Change
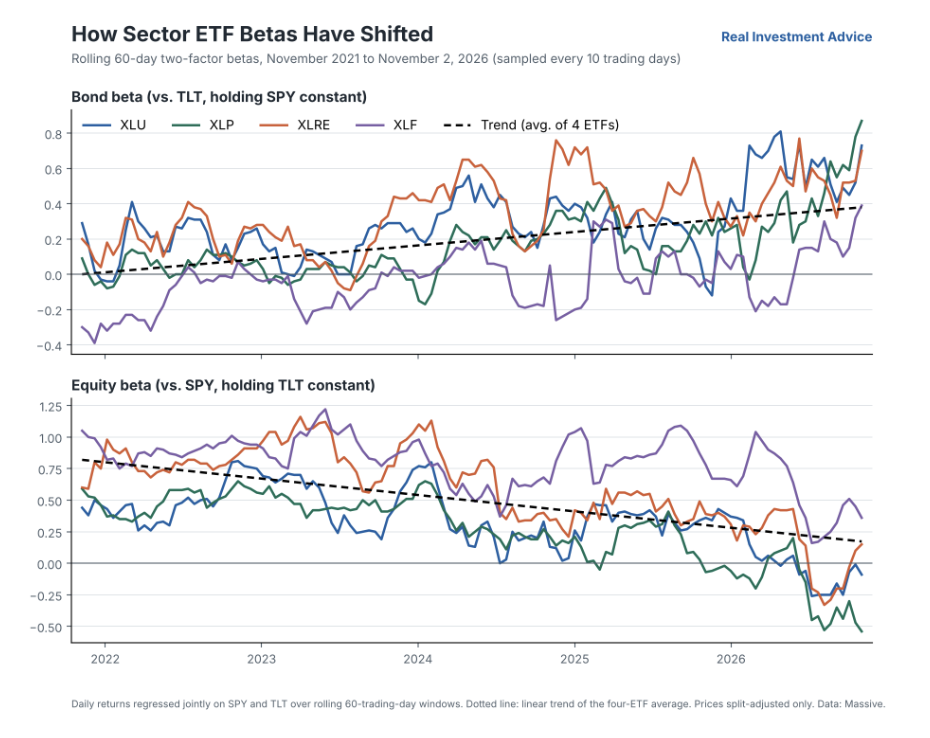
The rolling betas shared above change daily, so it's important to measure them against historical averages and trends. To put the current betas in historical context, we graph the four ETFs' equity and bond betas since November 2021. The dotted trend lines help highlight the trend of the last five years.
The four-ETF average bond beta has trended upward from roughly zero to about 0.38, while the average equity beta has trended lower from about 0.80 to 0.17.
The takeaway is that the price behavior of the four sectors — especially staples, utilities, and REITs — has become much more dependent on bond yields and much less so on the stock market.
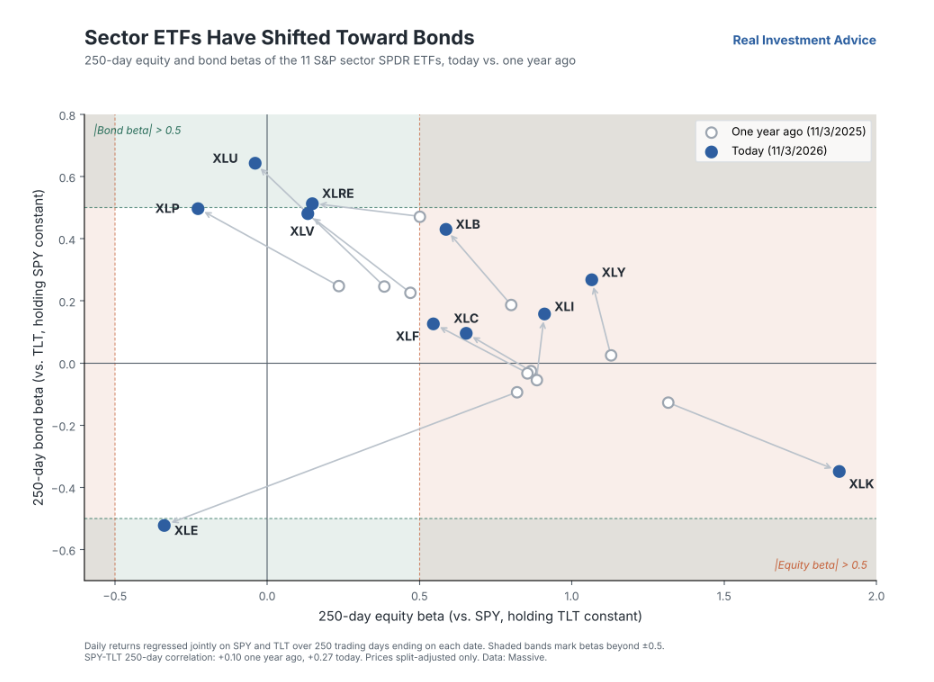
The graph below broadens the lens to all 11 S&P sector ETFs. It plots each sector's current equity beta against its bond beta today and one year ago. Note that this graph is slightly different from the table and graph above. It uses 250-day betas rather than 60-day betas and covers all 11 sectors rather than four. It provides a broad view of how betas have shifted; thus, it's not a direct comparison with the figures above.
Nine of the 11 sectors have higher bond betas than a year ago, and nine have lower equity betas. Utilities and REITs now have bond betas above 0.5, and staples sits right at 0.5. Technology and energy are the exceptions, moving further away from bonds.
Stocks That Act Like Bonds Are Not Bonds
Some stocks, like those shown in the table above, currently deliver bond-like interest rate sensitivity and may do so in the future, but they lack the bond features that make kicking the field goal so attractive.
A Treasury, corporate, or municipal bond has a maturity date and a par value. Hold it to maturity, and the current yield to maturity is locked in, assuming it doesn’t default. A stock, regardless of how high its interest rate beta is, has neither. It can lose value to weaker fundamentals, a corporate event, or a broad equity selloff. Stocks are also subject to dividend reductions or eliminations at any moment. Other risks include tax laws, regulations, and competition.
It's also important to reiterate that today's low equity and high yield betas are not permanent. In late 2022, utilities names AEP, Duke, and NextEra had equity betas between 0.5 and 0.9. Today, all three are negative. Furthermore, the z-scores in the table measure how stretched these relationships are, and stretched relationships tend to revert, as they did in 2022.
There is another caution. When stocks and bonds fall together, bond proxies are likely to provide less cushion than their low equity betas suggest. The recent positive correlation between TLT and SPY also blurs the separation of the two betas, which may exaggerate some extreme readings in our table.
Summary
Investors on a good path to meeting their financial goals face Bucs Coach Todd Bowles' choice. A 4.75% Treasury is the field goal, a known outcome if held to maturity. Bond proxies sit somewhere between the field goal and a touchdown attempt. They currently offer rate exposure within equity securities, but still carry traditional equity risks.
Understanding how your stock portfolio is exposed to the stock and bond markets, and adjusting exposures when necessary, is one way equity investors can try to keep three points on the board and improve their odds of winning their financial goals.
Read more by Michael Lebowitz:
Michael Lebowitz is a portfolio manager with RIA Advisors and author for Real Investment Advice. For more information, contact him at [email protected] or 301.466.1204.
Join RIA Advisors and elevate your career within a deeply experienced team focused on innovation. Our collaborative environment is built on a foundation of advanced technology and effective investment models, designed to enhance your ability to serve clients and grow your practice. Benefit from a supportive culture that encourages professional development and fosters a forward-thinking approach. By joining our team, you’ll be part of a group dedicated to excellence and continuous improvement, empowering you to focus on building meaningful client relationships and pursuing your business ambitions. Discover the advantages of working with our accomplished advisory team by starting your conversation today.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
More Innovative ETFs Topics >
 Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.