AI: Where Will the Money Come From?
Price Is What You Pay, Value Is What You Get
Last Chance to Watch the Free Longevity Symposium
Cleveland, DC, Tulsa and Las Vegas
“A billion here, a billion there, and pretty soon you’re talking about real money.”
- Commonly attributed to Sen. Everett Dirksen, although the saying was often used before.
The quote above now seems quaint. I’m sure that many of us can remember when a billion dollars was an unfathomable amount of money. And in one sense, it still is. It’s hard for the human mind to get around the concept of the billion. A trillion dollars? We throw the word around every day, not realizing that $1 trillion is 1 million millionaires.
It would take 11 days and three hours to count to 1,000,000 one second at a time. It would take 31,700 years to count to a trillion.
Berkshire Hathaway has over one third of $1 trillion in cash ($365 billion). We just saw the first trillion-dollar ETF (Vanguard). SpaceX went public for $1.7 trillion. OpenAI and Anthropic both plan trillion-dollar IPOs. There are 10 companies in the S&P 500 worth over $1 trillion with another four in shouting distance. The equity raises we are seeing are simply staggering the mind. We are going to talk about AI and capital needs: who will get it and who won’t? And the critical question: what will that mean for your portfolio?
But first, and quickly, at the end of the letter I will be talking about the longevity and health webinar that is actually scheduled for October 24, which may be going on while you read this. No worries, you can still listen to or read each of the sessions. Just sign up below. And note that after this I will not be mentioning Lifespan Edge for a very long time, if ever. If you want to follow my longevity journey in a separate format, just click on the link. Now let’s think about AI.
AI: Where Will the Money Come From?
Gemini tells me that the US is on pace to invest $6.7 trillion in data centers by 2030, with $5.2 trillion being AI-specific capacity. The four major AI companies (Microsoft, Amazon, Alphabet and Meta) are expected to be about half of that. Anthropic and OpenAI and SpaceX are all making massive investments.
That is in a world that must fund trillions of dollars of sovereign debt not just in the US but all over the world. Plus, other “normal” business investments which will be even more hundreds of billions, if not trillions. And that brings us to the thrust of today’s letter: who will get access to this money and what are the returns going to be?
First off, there are several types of AI companies. Some use the compute power, some build it and rent it out, some are hyperscalers and cloud providers, some are enormous and some are startups. Their needs and long-term viability are completely different.
First off, the trillion-dollar hyperscalers like Microsoft, Amazon, Meta or Google are not going to have problems raising money. Their debt is investment grade, and they generate collectively $380 billion in free cash flow per year. They are taking that and investing it into AI capital expenditures and borrowing additional money as well. This may impair their future profits for a period of time, but these are massive companies and they can take a “short-term” hit. It will likely affect their share price, but we don’t know whether the market will see that as positive or negative yet. And different companies will have different characteristics and price volatility.
And then there are the “neo clouds.” In the AI world, neo clouds refer to specialized cloud infrastructure providers that focus on delivering AI infrastructure, particularly GPU-as-a-Service (GPUaaS). These providers are designed to meet the demanding AI workloads of enterprises, model builders, and hyperscalers by offering high-performance computing capabilities. The term "neo" is used to describe a new generation of cloud providers that are built specifically to support AI workloads, offering a different approach to cloud computing than traditional hyperscalers. Neo clouds are built around accelerated computing, GPU infrastructure for AI training, fine-tuning, and inference, and they cater to the unique needs of AI workloads, which require dense compute, high-bandwidth networking, fast storage, and carefully engineered interconnects.
Note that these are essentially leasing companies, investing in real estate and GPUs and leasing or renting them out to larger hyperscalers. These Neo clouds use the rental agreement to finance the data centers, but the income doesn’t typically start until they are finished, so there are massive upfront costs that must be borrowed or raised as capital from the market.
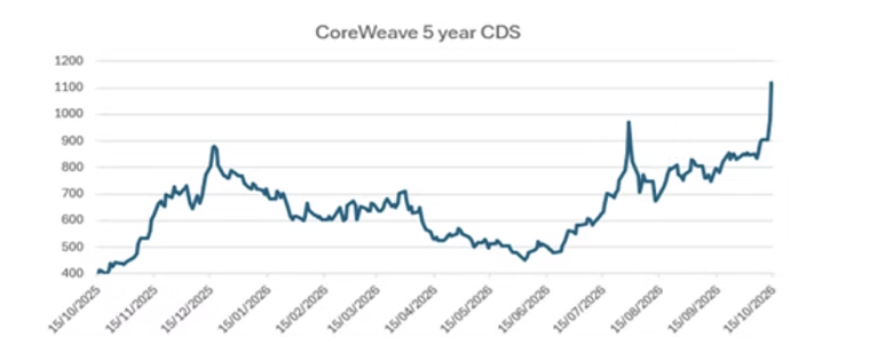
This was all fine and good last year. Now investors are beginning to question the potential profitability of the Neo clouds, like CoreWeave, which we touched on last week. Right now, the credit default swap market is projecting a 55% chance that CoreWeave defaults on some of its credit. Basically, if you want to lend money to CoreWeave and hedge it, you must spend $5.5 million to hedge your $10 million loan over five years. That of course makes the interest rate that CoreWeave pays go through the roof. They are now basically junk bonds.
See more: RIA AI Adoption Is Showing Up in the Filings
Gemini tells me that CoreWeave will need to raise $113 billion just to meet its current commitments. How can they make a profit if they are paying 15% interest rates annually? Note that Nvidia owns almost 9% of the company and they are basically an exclusive Nvidia shop in terms of the GPUs they buy. Will Nvidia let them go down? Probably not, but it will likely not be at a price that shareholders of CoreWeave will be happy with.
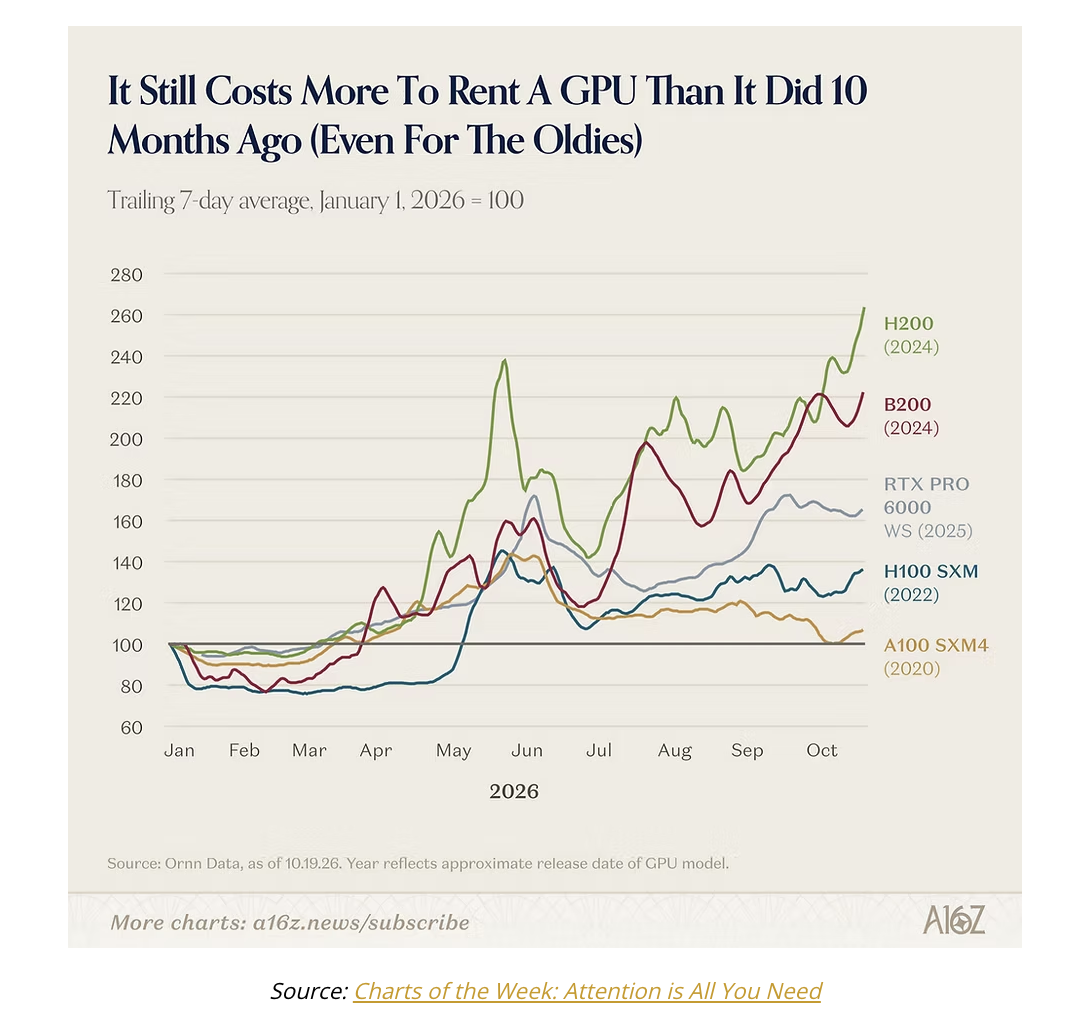
All that said, the critics that say that the chips and GPUs that Neo clouds and other large data centers are using are depreciating assets that will not have any value as the new chips come along, don’t understand where the actual value in those chips is. It now costs more to rent a used GPU than it did 10 months ago. In the chart below you can see that even six-year-old GPUs are renting for more than they did just 10 months ago. The rent on two-year-old chips is up 2.5 times since the original launch.
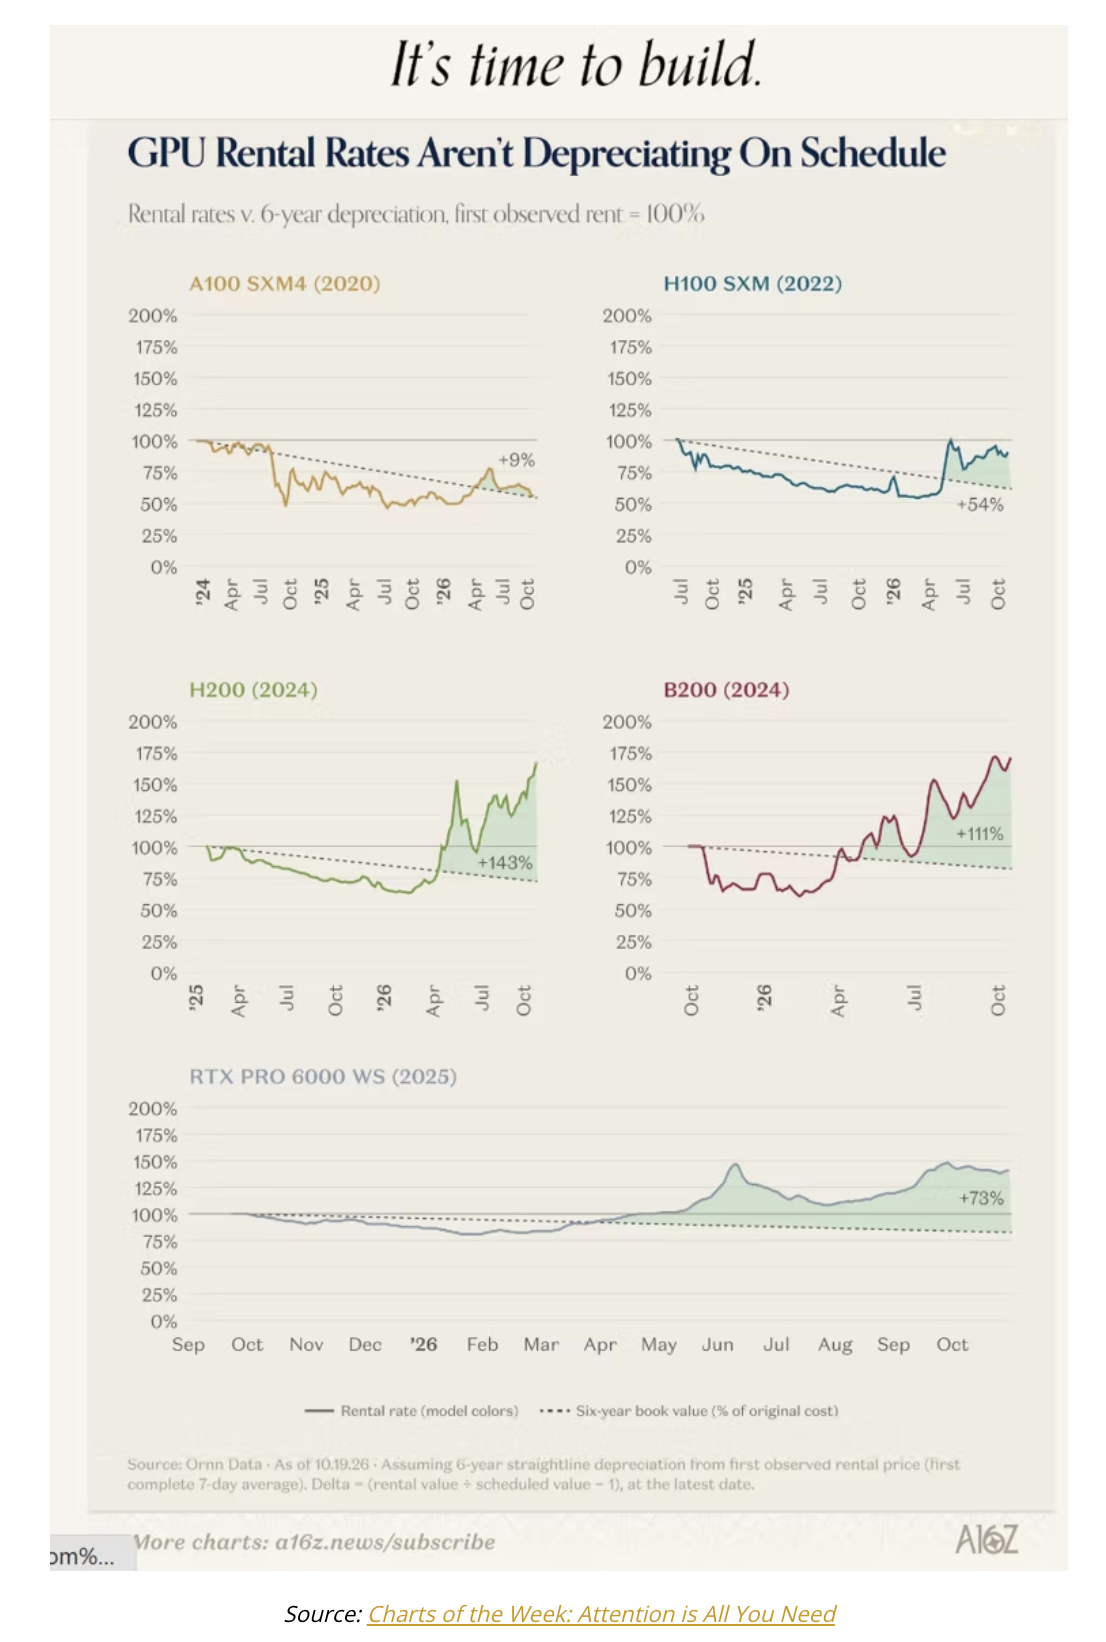
Assets in general and chips specifically depreciate from an accounting standpoint on a specific schedule. A16Z built this chart below showing the rental rates for five different generations of chips. Notice how the rental rates, even for six-year-old chips, are ahead of their depreciation rate. And for 2024 era, they are now getting from 111% to 143% higher rental rates than when they were initially bought. That is why the proponents of the Neo clouds are so bullish. And believe me, there are a lot of them. Even after a 55% drop in the market cap of CoreWeave, investors still value them at $39 billion. That hardly seems like a company whose credit rating is going to junk. That being said, price is what you pay and value is what you get.
I am an AI bull in the sense that I was an Internet bull back in the 90s. The Internet was clearly going to change everything, we just didn’t know how much yet. And we did not know which companies would be the real winners.
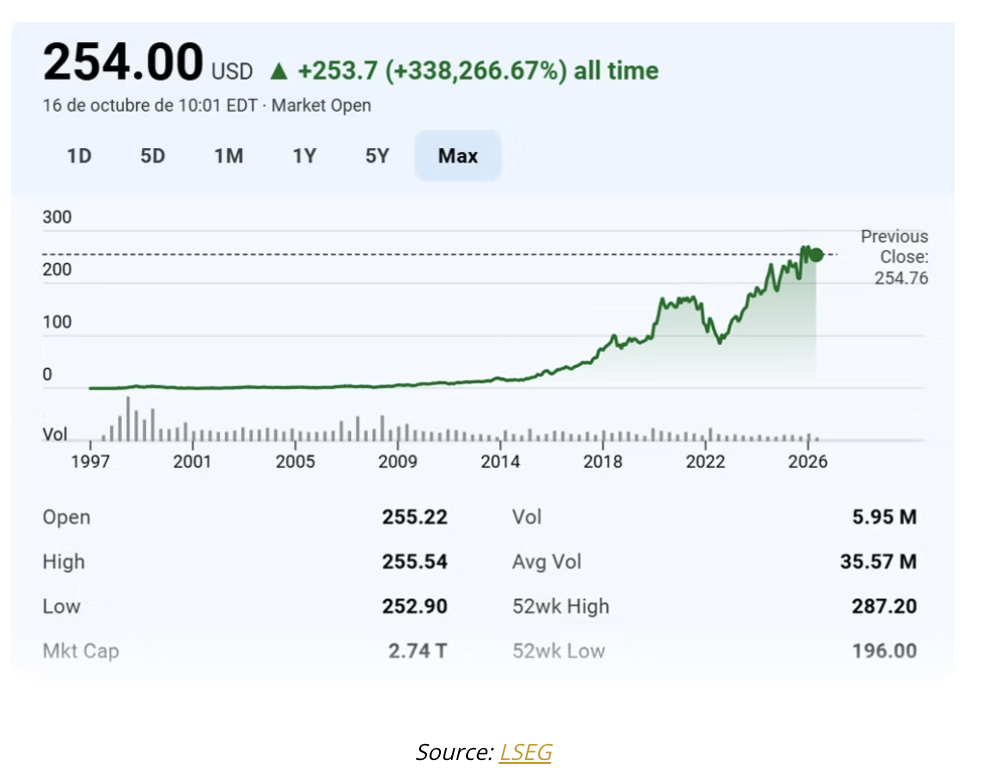
I used this chart last week, but it bears revisiting it here. It took Amazon almost 15 years before it “exploded.” And then it went hyperbolic. If you invested in 1999, you are up over 300,000% 27 years later. But it was an up-and-down ride. And there were literally scores of companies just like that.
I think AI is going to be like that. There are going to be powerful winners. Some will rise faster than others, but I think many AI companies will be like Amazon and that it will take a very long time for them to reach the explosive growth in terms of valuation we currently think will happen. And others, like pets.com, will disappear.
There was another bubble last century, but nobody really talks about it, because it didn’t show up in the stock markets. I’m thinking about the automobile manufacturing business. There were between 3,000 and 3,300 automobile manufacturing companies started slightly before and 20 years after 1900. By 1920, there were 98 and by 1930 there were 44. A lot of this was consolidation, but a lot of it was simply companies going out of business. It will be a lot more visible in the AI world, but not totally. There are hundreds of AI startups all focused on various aspects of the market, many of them competing head-to-head with numerous competitors, and not all will survive. That’s Schumpeter’s creative destruction, and it’s good for consumers and the economy.
From DeepView:
“This week at Gartner IT Symposium/Xpo, the company's annual flagship event, the analyst house revealed contrarian data on AI investment from surveys of CEOs and CIOs and other Gartner research:
- 81% of CIOs are increasing AI spend
- 44% of CEOs struggle to demonstrate AI-driven financial returns to stakeholders
- 13% of CIOs say their organizations have realized significant or transformational value from AI
- 11% of CFOs see clear returns from AI
- 4% of CIOs have plans in place to redesign roles for a human-agent workforce
- 58% of CIOs face increased pressure to deliver cost improvements from AI
“These numbers highlight the fact that AI is rapidly shifting from experimental mode into a place where it has to show accountability for impact and ROI. Leaders are going to have to be able to articulate not just what AI can accomplish but how those benefits can justify the costs for both deployment and ongoing operations.
"Volume is not value," said Alicia Mullery, Gartner analyst. "AI is creating a reckoning for organizations that lack fundamental disciplines, such as defining use-case value ahead of time and establishing criteria for when to walk away."
“Gartner analyst David Furlonger further extrapolated, "The AI value problem will not be solved by simply adding more AI to existing ways of working."
“In other words, if companies rely on AI to simply automate individual tasks then the economic upside is likely to remain limited and the pressure on executives will continue to increase. Instead, they're going to have to think bigger. Enterprises will need to do the harder work of redesigning workflows, reimagining decision-making processes, and rethinking organizational structures.
“That’s a lot to ask and it takes investment and organizational buy-in, but that’s what will be required to drive the kind of transformations that match the rhetoric and the level of investment we’re seeing around AI. It also requires bringing AI down from the clouds and thinking of it like all of the other technology shifts and changes from the past. Even if it’s a more powerful and capable technology than what’s come before, it still needs to earn its stripes in the same way and live by the same economic laws.”
(I read a lot about AI. I find the newsletters from A16Z and DeepView to be the best free letters that I found. They are not short and easy reads, but they are full of facts and inside knowledge.)
Price Is What You Pay, Value Is What You Get
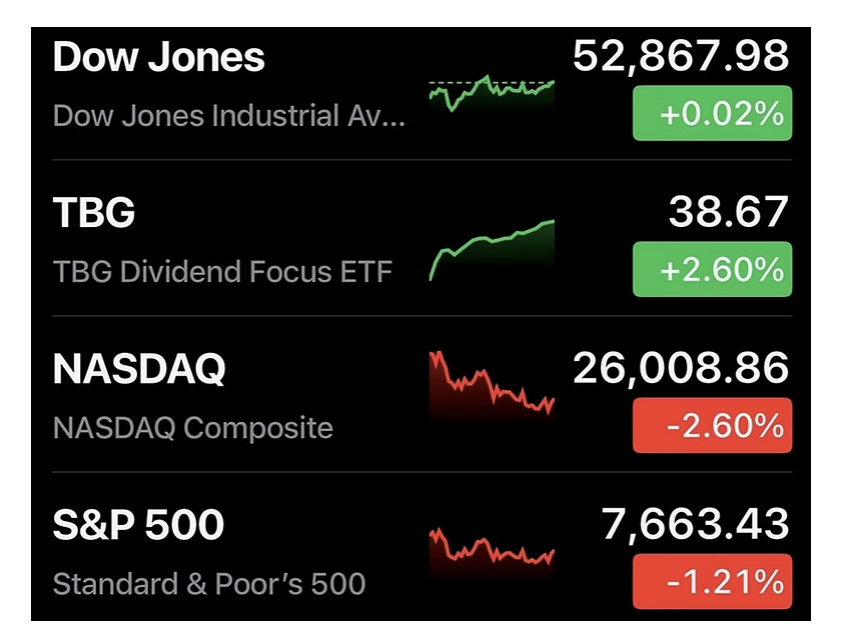
Last week I made the case that index investors would get hammered when individuals begin to question the profitability, let alone the viability, of various AI companies. Investors tend to throw the baby out with the bathwater. I didn’t expect to see confirmation of it so quickly. On Thursday, we saw significant negative price action in tech and telecom stocks. The S&P was down by 1.21% and the NASDAQ collapsed 2.6%. Dividend aristocrat ETFs were actually up around 2%. My friends at The Bahnsen Group run a specialized dividend ETF that is an actual mirror of the stocks and positioning of how they manage client money on an individual basis, so it is a good proxy for an actively managed dividend portfolio. While the index funds were down, the TBG Dividend Focus ETF was up 2.6%. Obviously, this was a serious rotation from growth stocks like AI and telecom into value stocks represented by high and growing dividend-paying stocks.
I write this on Friday morning, and there is a mild correction as I write this, and it could completely reverse by the end of the day. Who knows? But the point is that specific actively managed value stocks will likely outperform growth stocks in a market correction - if history has any bearing on the point, which I personally think it does.
Many readers have asked me how they can invest in dividend stocks like Bahnsen does, as their portfolios are smaller. This ETF is one of the best ways I know. You can look at the individual holdings if you are so inclined. The symbol is TBG. They (and I through my readers) get a lot of requests from international investors about how to adopt this strategy. In a few months, there will actually be what is called a UCITS fund which will mirror the US ETF, so most international investors will be able to access it that way. There are no minimums, so that makes it useful for investors who like to manage their own portfolio or are starting their journey.
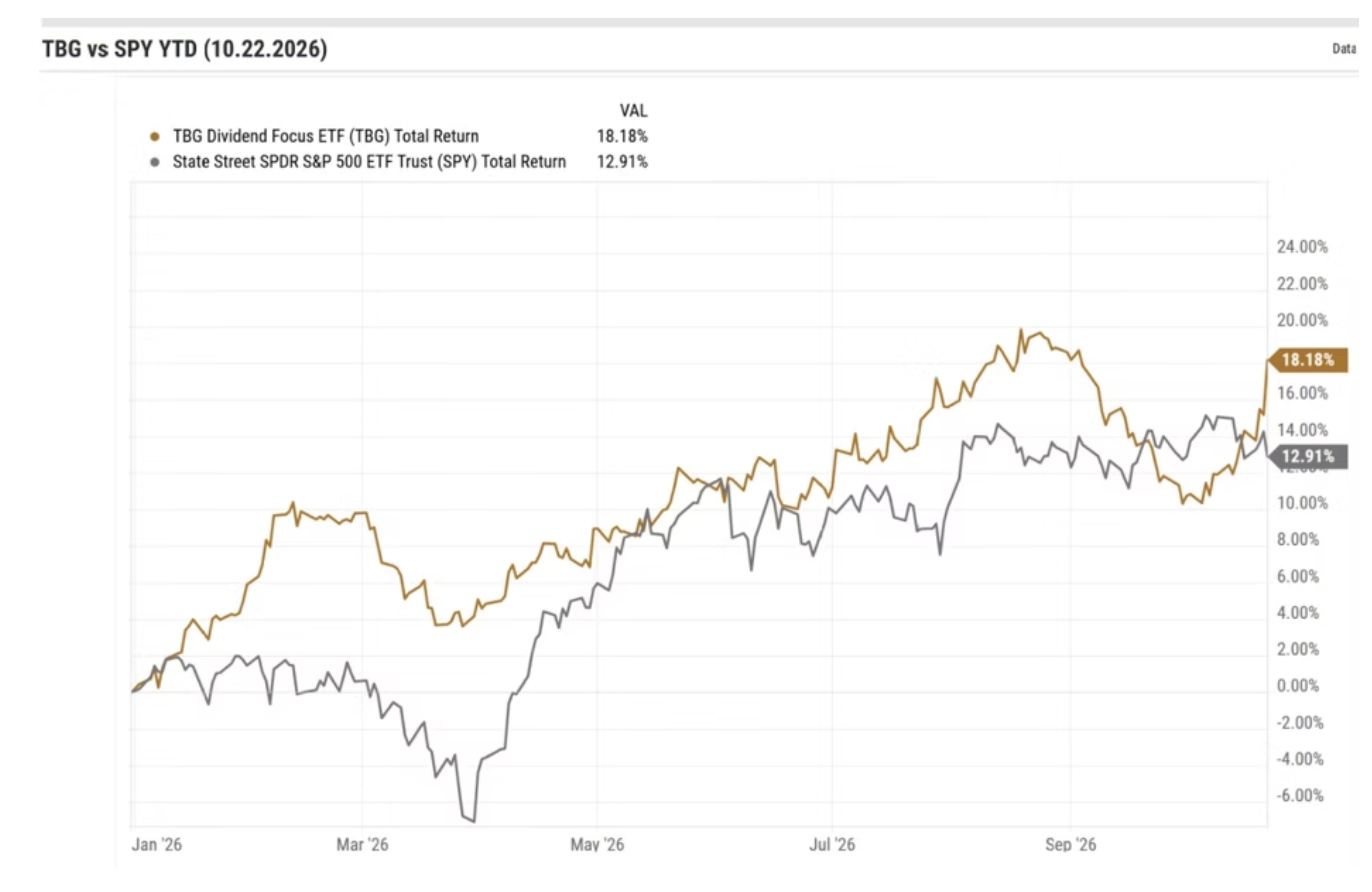
This is a chart of the year-to-date performance of the TBG ETF versus the S&P 500. Yes, it outperformed, but not uniformly and there were significant ups and downs. Dividend portfolios, even well-managed ones, have volatility. This is not a bond. And it will certainly not keep up with a bull market in AI and tech stocks, at least until there is a correction.
(That being said, TBG offers a wide range of services that really complement the dividend portfolio, and you should consider at least talking with them about what they can do for you. David writes a weekly letter on Friday called Dividend Cafe, one of my favorite reads. So many readers have thanked me for telling them about Dividend Cafe. And if you are looking for someone to talk to about some of those value stocks I was talking about, you should just ask to talk with one of their representatives. If you ask, they will also send you David’s latest book on dividend investing, which I think is a must-read.)
Caveat: Thursday was a one-day event. While it was a large outlier, over a year’s time it will just be seen as noise. You should certainly not invest based on one-day returns. I bring up the point because I think it suggests what the trend will be if the bubble in AI tech is revalued, as many think it will be. Since we don’t know the future, that is why I use the word “if.” Maybe the AI world doesn’t correct. Stranger things have happened, but I wouldn’t bet on it.
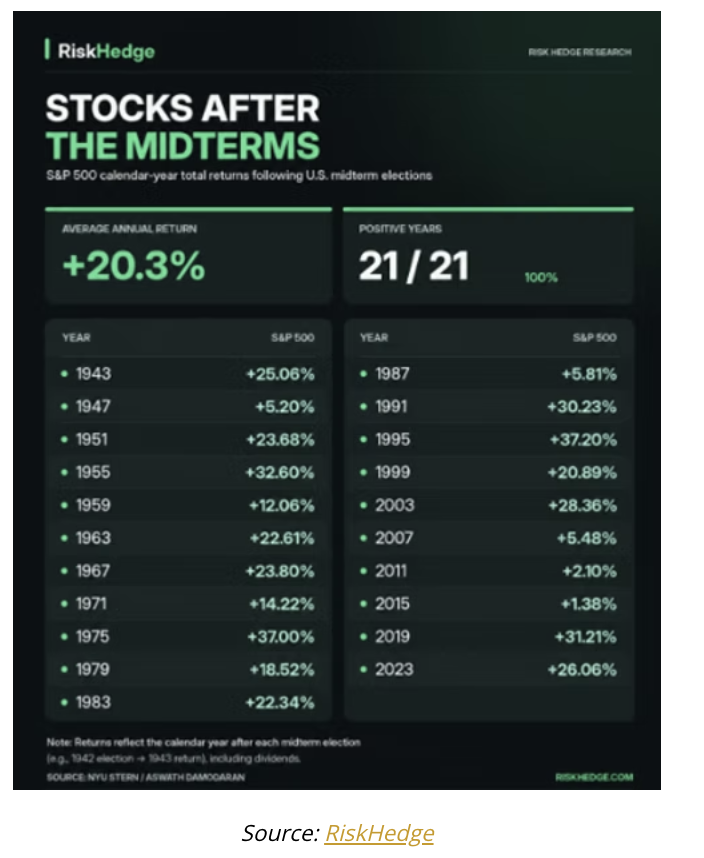
While we are talking about the stock market, my associate Stephen McBride noted that for the past 80 years, the stock market went up 21 out of 21 times in the year after the midterm elections. So, it’s possible the stock market doesn’t correct all that much. (No guarantee either way.)
Last Chance to Watch the Free Longevity Symposium
Our Lifespan Edge longevity symposium is live on Saturday, October 24th. If you are reading this later, you can still watch it as everything - all 12 presentations - will be online and on YouTube as well as on our website. And we will shortly have transcripts.
After today, my intention is to not mention Lifespan Edge in this letter again. If you want to follow me and Dr. Mike Roizen on our longevity journey, you can keep up with us by clicking on the link below.
About the symposium:
The topics will cover a wide range, including brain health, the latest breakthroughs in technology, peptides, stem cells and more. One of the leaders in that Parkinson’s cure that I’ve been writing about will give us his data. There will be 12 cutting-edge presentations, each focused on their specialty, for 25-30 minutes.
You can sign up at Lifespan Edge Symposium. You will immediately get an email with a link to the webinar. At the website, you can see who the speakers are and their topics. It will be a zoom conference with the ability for you to send your questions to the speakers. We are structuring this to be practical advice that you can adapt to your own needs, from the simple question of “what vitamins should I take?” to an explanation of the powerful growing role of peptides and stem cells, and what it means for you. We will be talking to the doctors who are writing the legislation to allow stem cell therapies to be tried in various states. What this means is that in a growing number of states you will be able to access these extraordinarily powerful technologies for yourself. These are the experts on the cutting edge, specifically chosen by Mike for their expertise.
The biotechnology world is changing so fast, and we want to help you keep up. We all want to not only live longer, but to increase our healthspans so that we can live an active and fulfilling life, not just exist in old age. As Mike will explain, there are 14 biological mechanisms that will be needed in order to reverse aging. Two are available now and four others are in human trials, with more breakthroughs on the immediate horizon. Mike thinks there is an 80% chance that by 2035 we will be reversing aging. Your mission, should you choose to accept it, is to make sure that you live to 2035 and know where and how to access these new technologies.
We are here to help. Simply click on the link, sign up and we will make sure you get your free pass. I really want all my readers to do this, because I want to be writing to you in 2035. Don’t procrastinate. Sign up now.
Again, if you want to keep up with what Mike and I are learning about longevity, you need to sign up here as my plan is that I will not be writing about Lifespan Edge in the future, as this letter should be focused on economics and finance. Stay tuned…
Cleveland, DC, Tulsa and Las Vegas
Shane and I will be in Cleveland November 3-8, where my daughter Abbi will be having brain surgery, and I will get a few procedures and medical checkups done. I then fly to Washington, DC for an Inner Circle meeting. I will be back with Abbi and my kids and grandkids for Thanksgiving in Tulsa. In a few weeks after that, I will be in Las Vegas at the huge A4M Longevity Fest December 10-13.
People are always asking me what supplements I take for my health. Besides the usual vitamins and minerals, let me share one simple thing. Every day Shane makes me ½ a cup of “coffee” which has small amounts of powdered creatine, colostrum and inulin. The research on all of these supplements, and especially creatine, is powerful. She just puts the powder in and uses one of those small hand mixers to stir it up. I like to add a little Stevia as I don’t drink my coffee black. This is especially useful for those of us of a certain age. If you do this for a few months, I believe you will thank me.
I am ready for this election to be over, but maybe not for the reason you are. Someone either on purpose or fat-fingered my cell phone number into a Democratic fundraising machine in Texas. On top of the Republican fundraising machines, that was my fault. They think I am someone called Mark. I am literally getting 20 texts a day. Up until a few weeks ago, I really didn’t notice. But as I have started using my new and incredible Phonak hearing aids, which I connect to my phone, I now get that whooshing sound every time someone sends me a text. I get enough texts from friends and business associates that I have to look. Sigh.
Feel free to drop me a note, as I always read every email sent to me. And with that, I will hit the send button. You have a great week!
Your trying to figure out how to use AI analyst,
John Mauldin
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Mauldin Economics
Read more commentaries by Mauldin Economics