Farmers understand the risks of monoculture: planting only one crop, year after year. While initial yields may be strong, they will weaken as the soil’s nutrients are depleted. Sustainable farming requires variation in which seeds are sown.
The U.S. economy is gaining at an impressive pace, but with a risk of too much concentration in AI-related investments. A healthy economy should see growth across sectors. Though AI is still a dominant theme, we’d like to see green shoots of more diverse investment growth.
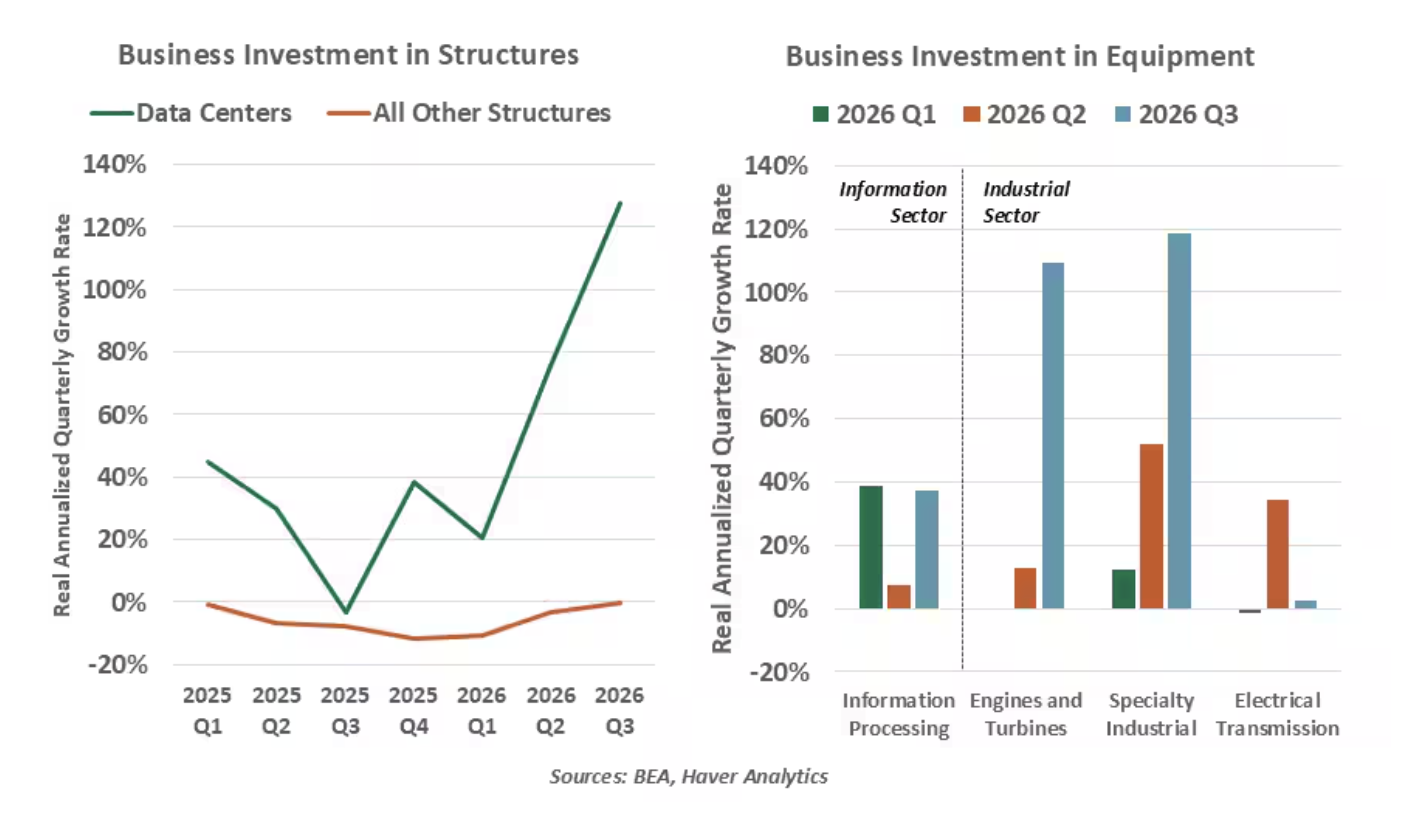
Business investment has led economic gains in the U.S. in the year to date. In the third quarter, nonresidential investment contributed 1.8% of the strong 3.4% gain in annualized gross domestic product. Data centers and computing equipment were the top investment items.
Markets have also borne out this trend. Investor enthusiasm for AI and its supporting technologies has been unabated since ChatGPT’s launch in 2022. Capital markets stood ready to support the AI buildout. Debt issuance by the six major hyperscalers (large-scale cloud computing providers) is on track to nearly double this year. The technology sector drove two years of equity market outperformance in 2024 and 2025, but hyperscalers’ values have become more volatile this year. We have kept an eye on this market dynamic as a risk to the wealth effects that have enabled robust consumer spending.
But the intensity of activity surrounding AI leaves the market and economic performance heavily reliant on this sector. A tech downturn could spur a broad recession if it is the only source of growth; better diversity is needed.
See more: Behind the Shift Within the FOMC
We have expected a broader investment boom since summer 2025. The “One Big Beautiful” reconciliation bill offered tax rate certainty and created powerful incentives for businesses to spend on capital projects. Sweeteners like advanced depreciation allowances for equipment and commercial buildings and higher expensing limits for research and development added further support. And yet businesses were slow to act. Policy uncertainty and shifts in the cost of capital made some businesses hesitant. Development has been focused on data centers, not the broad array of projects that were envisioned.
Last quarter’s GDP report reveals the extent of this concentration. Apart from computer equipment and peripherals, investment categories experiencing strong growth included power generation, specialty industrial equipment and turbines, all of which are associated with the AI buildout.
The concentration risk presented by a heavy emphasis on AI came into focus around the midterm election, when candidates favoring more restrictions on data center construction did very well. While we do not expect the outcome of election 2026 to meaningfully alter the trajectory of the AI buildout, it cannot continue upward at such elevated rates indefinitely. We need a more well-rounded set of investment drivers.
There are some nascent signs that capital spending is broadening. The White House boasts a list of investments launched since 2025, counting 522 projects totaling $383 billion of investment. Though semiconductors lead by value, the majority of identified projects are in sectors like metals and materials, energy, pharma, vehicles, defense and machinery. These projects account for 165,000 new jobs.
The AI investment boom helped to carry the economy through a dry spell. Now, a healthier variety of investment will ensure that yields will be sustained.
Ryan James Boyle is the Chief U.S. Economist within the Global Risk Management division of Northern Trust.
Information is not intended to be and should not be construed as an offer, solicitation or recommendation with respect to any transaction and should not be treated as legal advice, investment advice or tax advice. Under no circumstances should you rely upon this information as a substitute for obtaining specific legal or tax advice from your own professional legal or tax advisors. Information is subject to change based on market or other conditions and is not intended to influence your investment decisions.
© 2026 Northern Trust Corporation. Head Office: 50 South La Salle Street, Chicago, Illinois 60603 U.S.A. Incorporated with limited liability in the U.S. Products and services provided by subsidiaries of Northern Trust Corporation may vary in different markets and are offered in accordance with local regulation. For legal and regulatory information about individual market offices, visit northerntrust.com/terms-and-conditions.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Northern Trust
More Capital Growth Topics >