Consumer sentiment rises in November to the highest level in three months. The final November reading for the University of Michigan Consumer Sentiment Index came in at 51.5. This marks a 7.3% (3.5 points) increase from October. Consumer sentiment sits up 1% compared to a year ago and is currently in the 1st percentile in the series' history.
Key Takeaways
-
The University of Michigan Consumer Sentiment Index final reading rose to 51.5 in November, a 7.3% increase from October.
- The Current Economic Conditions Index rose 5.8% to 49.4, while the Consumer Expectations Index rose 8.4% to 52.9.
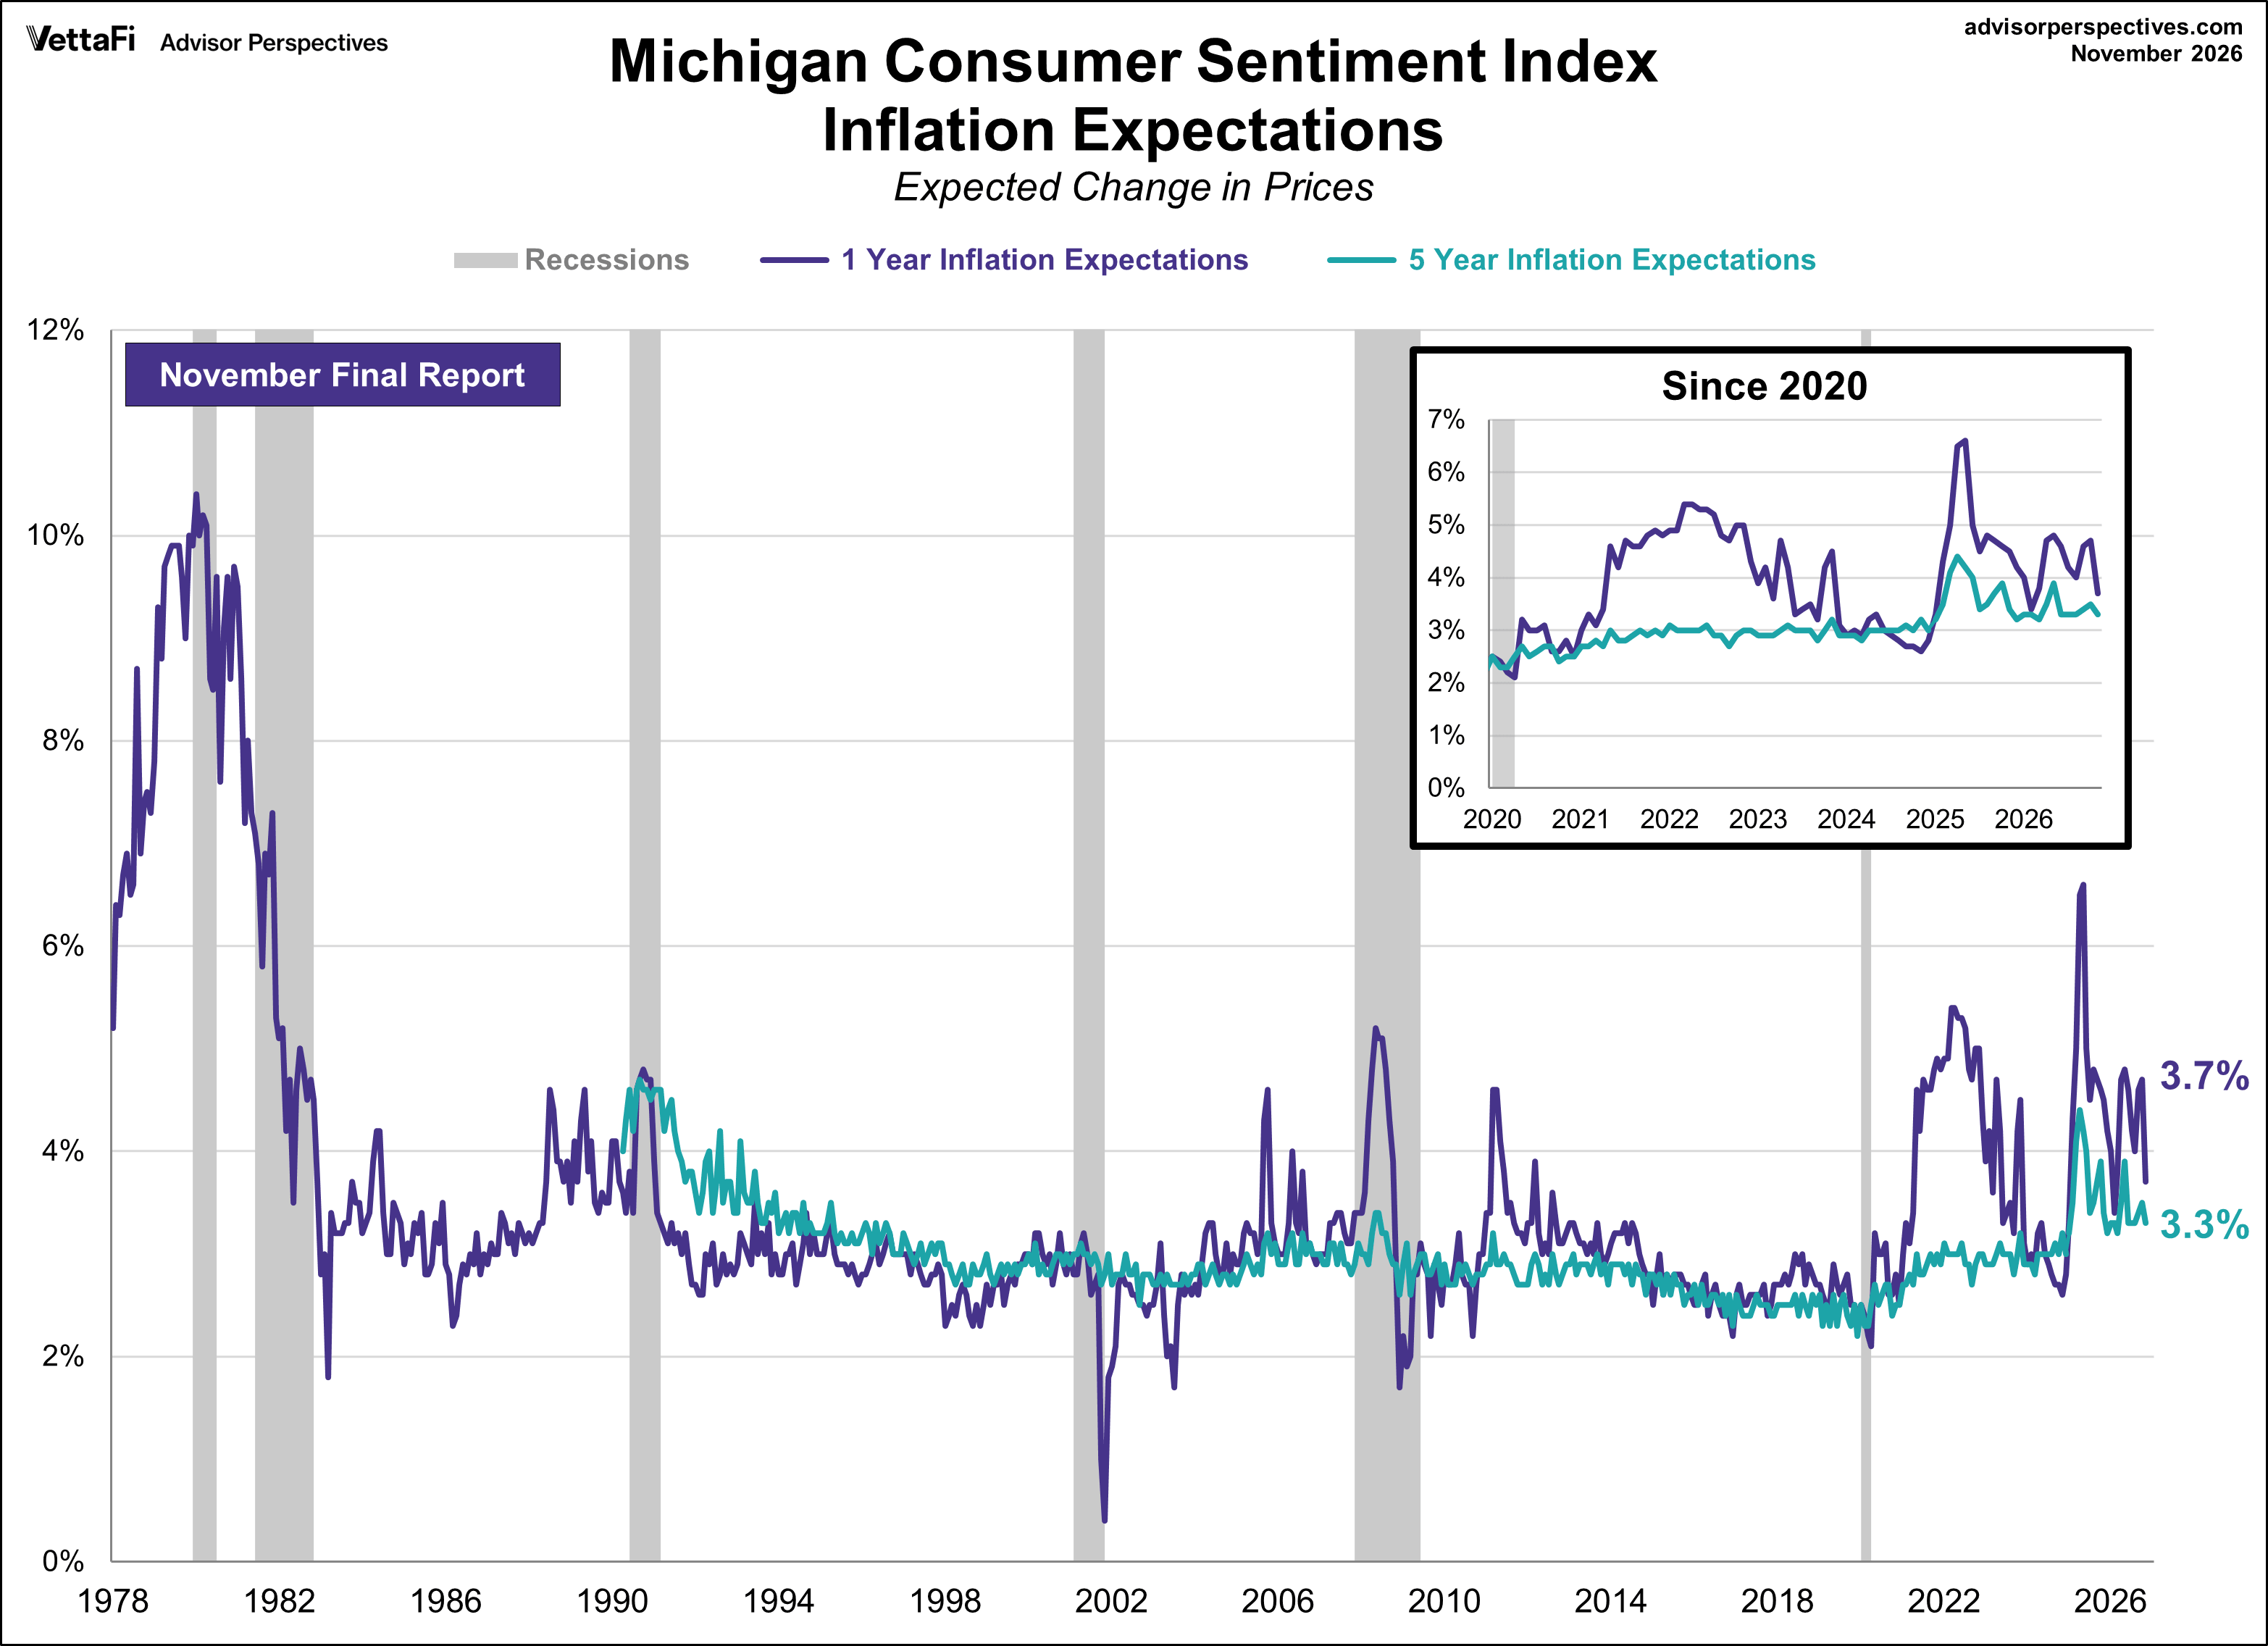
- Year-ahead inflation expectations decreased from 4.7% to 3.7% from October.
Joanne Hsu, the director of surveys, made the following comments:
Consumer sentiment rose about 7% this month, led by substantial post-election gains in both short- and long-run expected business conditions. Current personal finances improved for low-wealth consumers and, to a lesser extent, middle-wealth consumers, who experienced some relief with falling gas prices. In contrast, those with the largest stockholdings reported a decline in personal finances, consistent with continued AI-related agitation in stock markets. Consumers appear to anticipate potential changes to public policy under a divided government to come. Accordingly, the expectations index surged for independents, who swung to the left in the midterms, and increased more moderately for Democrats. Expectations fell for Republicans, who may not favor a slowdown of the White House policy agenda. Sentiment remains subdued at 9% below February, prior to the start of the Iran conflict, reflecting continued uncertainty regarding the cost-of-living factors that dominate consumers’ perspectives. This release covers interviews completed between October 20th and November 16th.
Background on the University of Michigan Consumer Sentiment Index
The Michigan Consumer Sentiment Index is a monthly survey of consumer confidence levels in the U.S. with regards to the economy, personal finances, business conditions, and buying conditions, conducted by the University of Michigan. There are two reports released each month; a preliminary report released mid-month and a final report released at the end of the month.
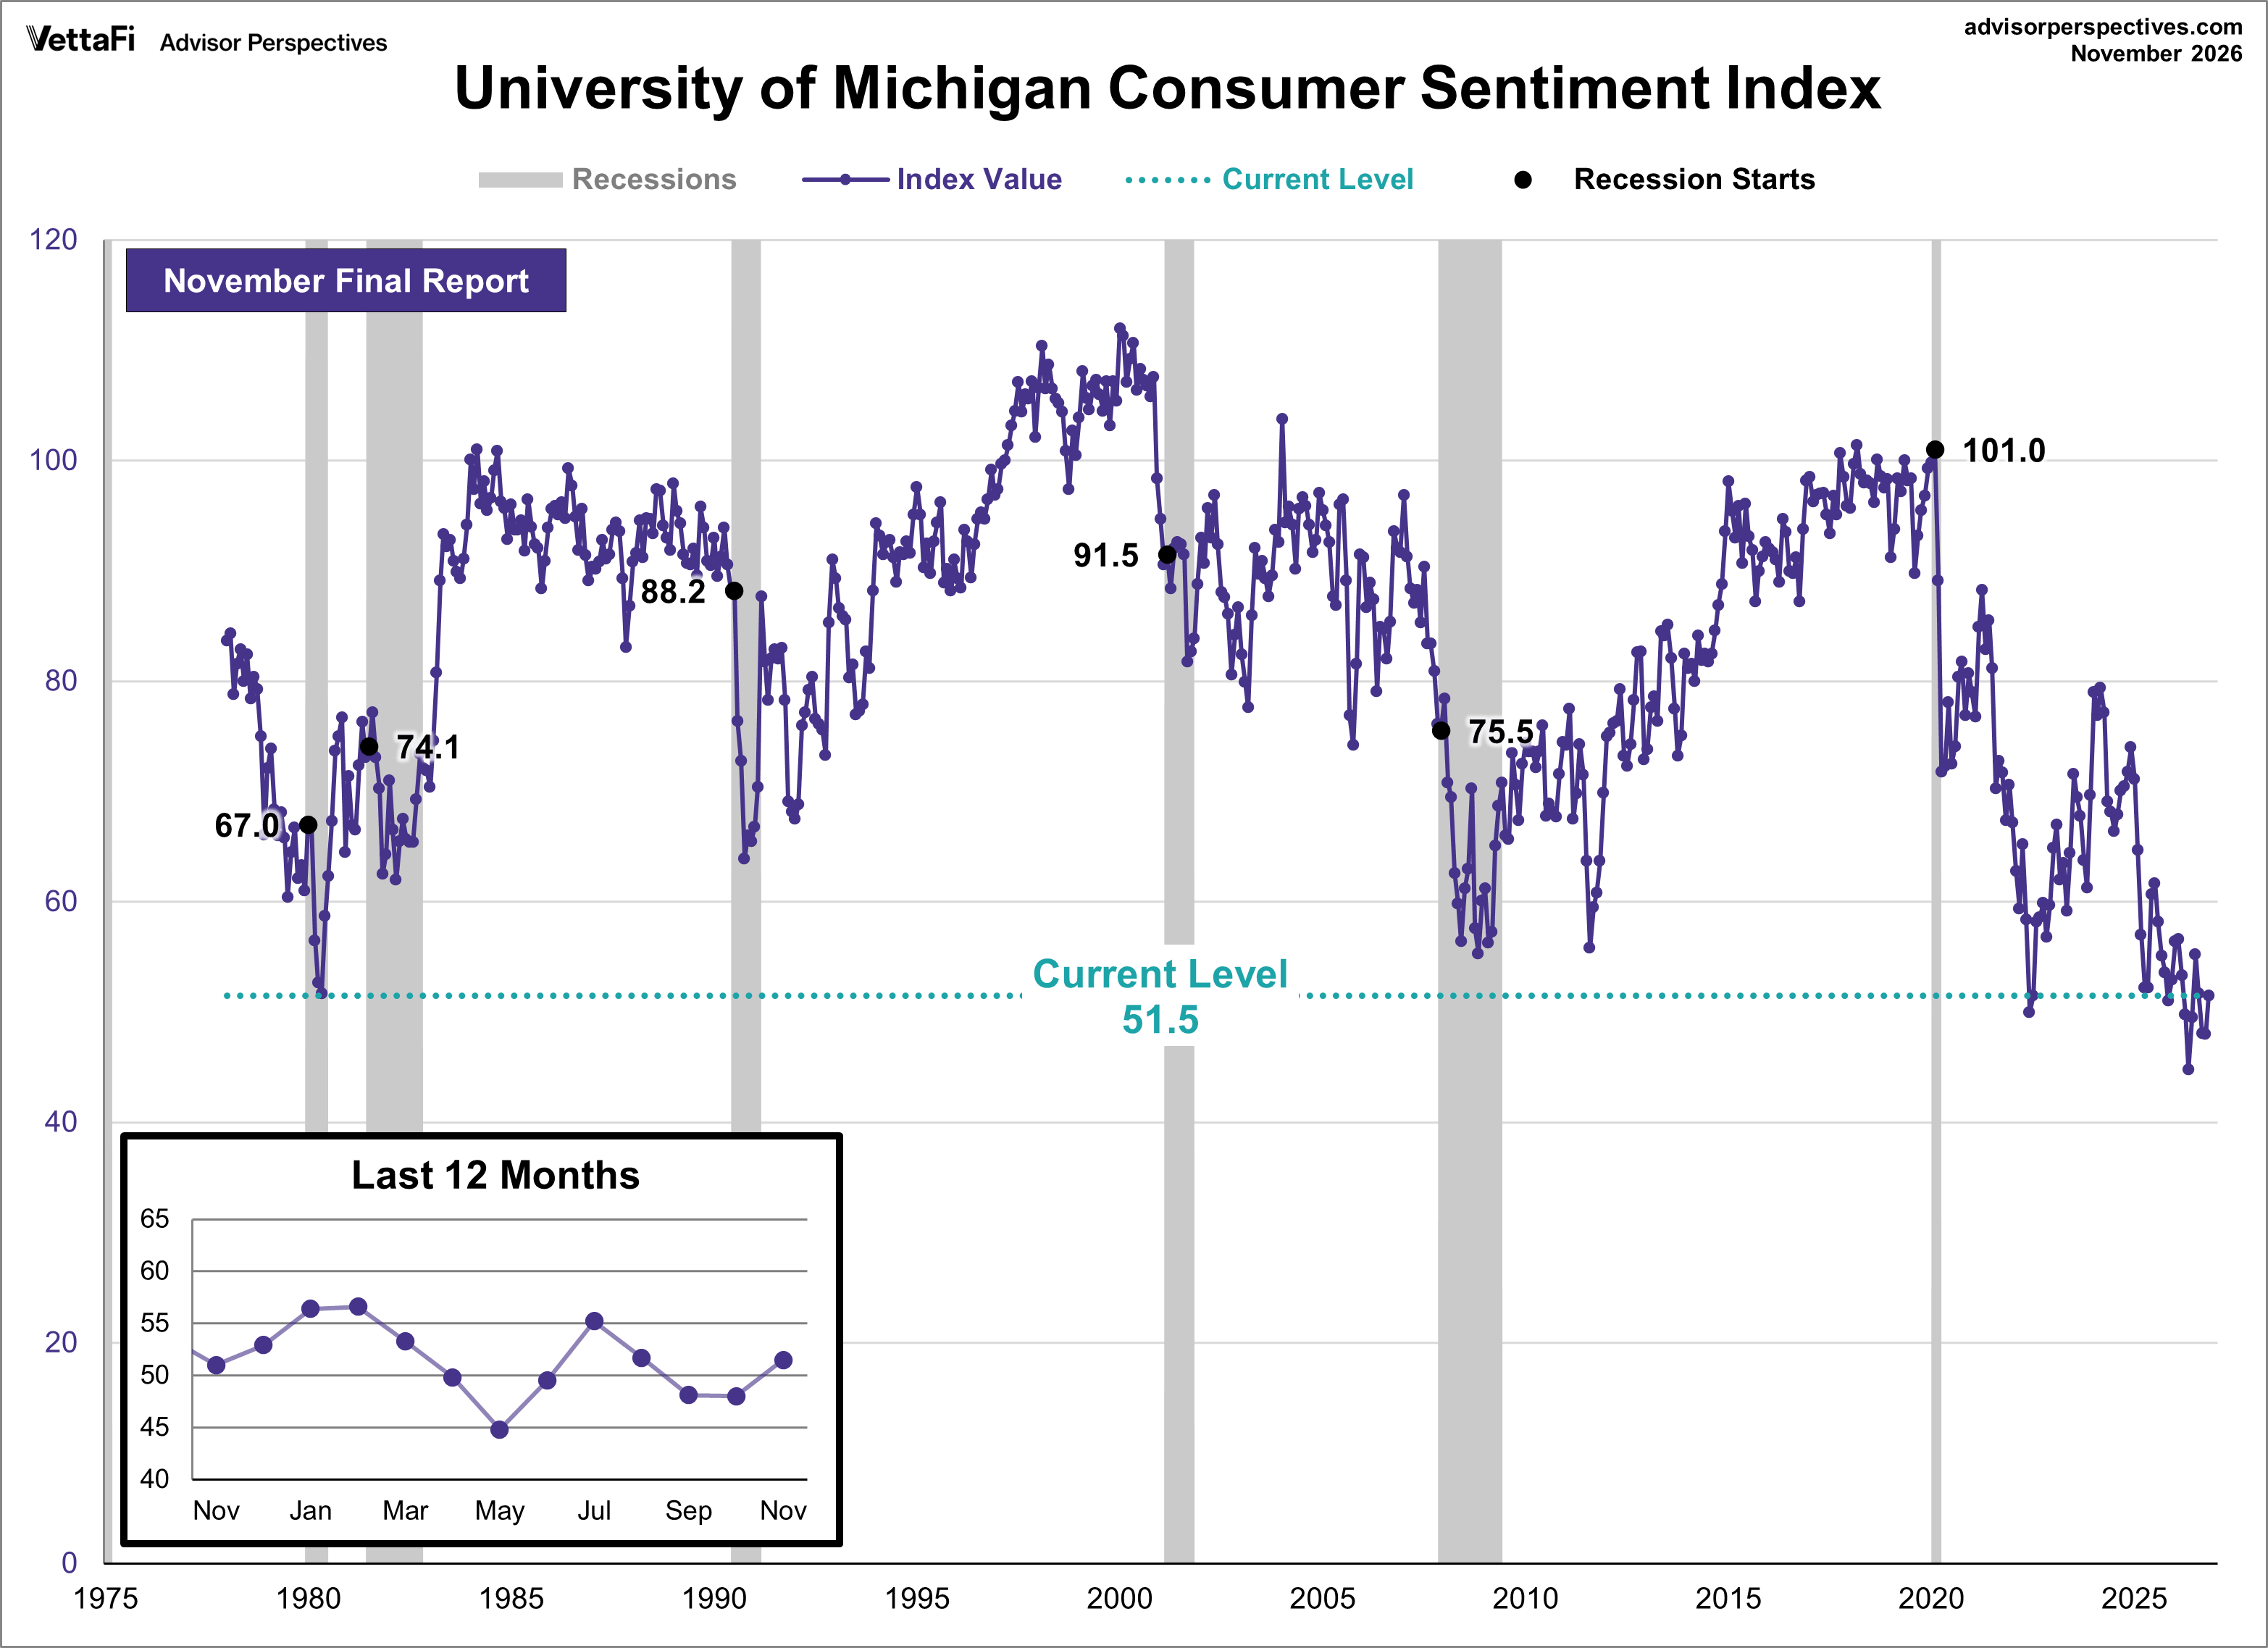
The chart below provides a long-term perspective on this widely watched indicator. We have highlighted the index's value at the start of each recession. The current level of 51.5 is below the index's value at the start of all six recessions since its inception.

To put today’s report in historical context, consumer sentiment is currently 38.3% below its average reading of 83.5 (arithmetic mean) and 37.3% below its geometric mean of 82.2, based on data dating back to 1978.
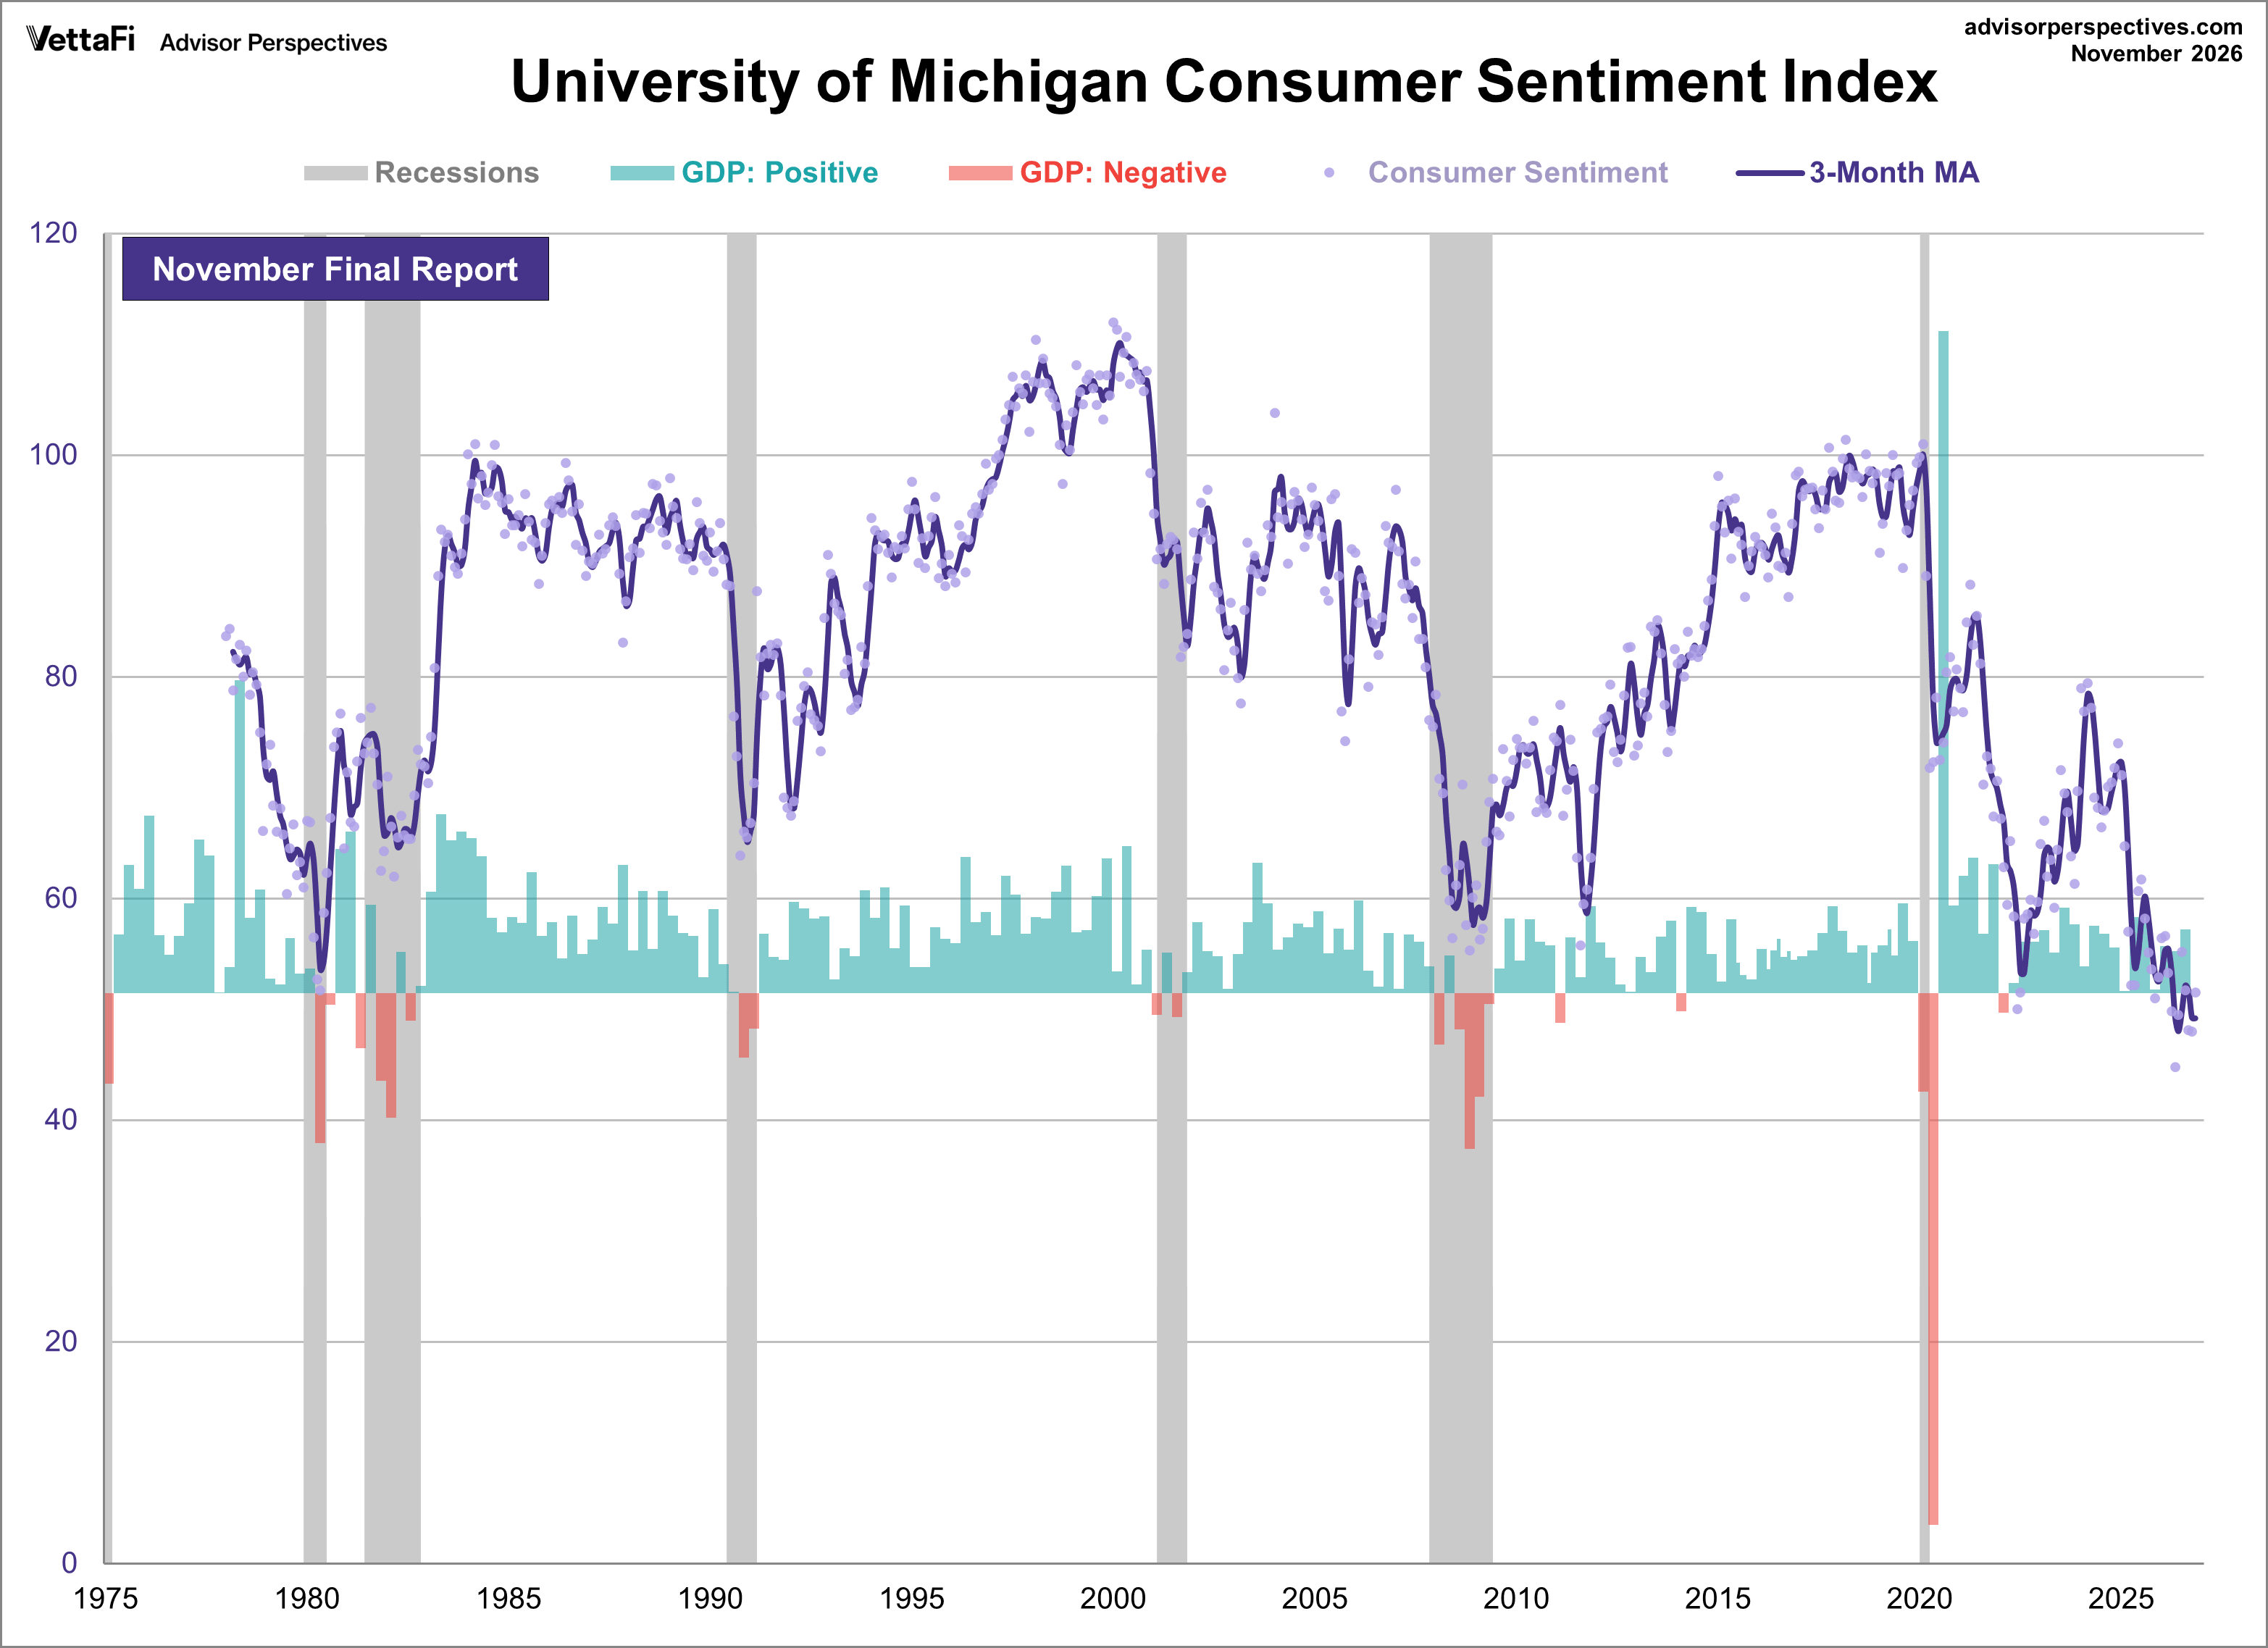
To visualize the volatility and its impact on the broader economy, the following chart includes a three-month moving average and real GDP. Historically, prolonged periods where the moving average remains at these depressed levels have closely correlated with negative GDP growth (the red bars below).
The Political and Presidential Lens of Consumer Sentiment
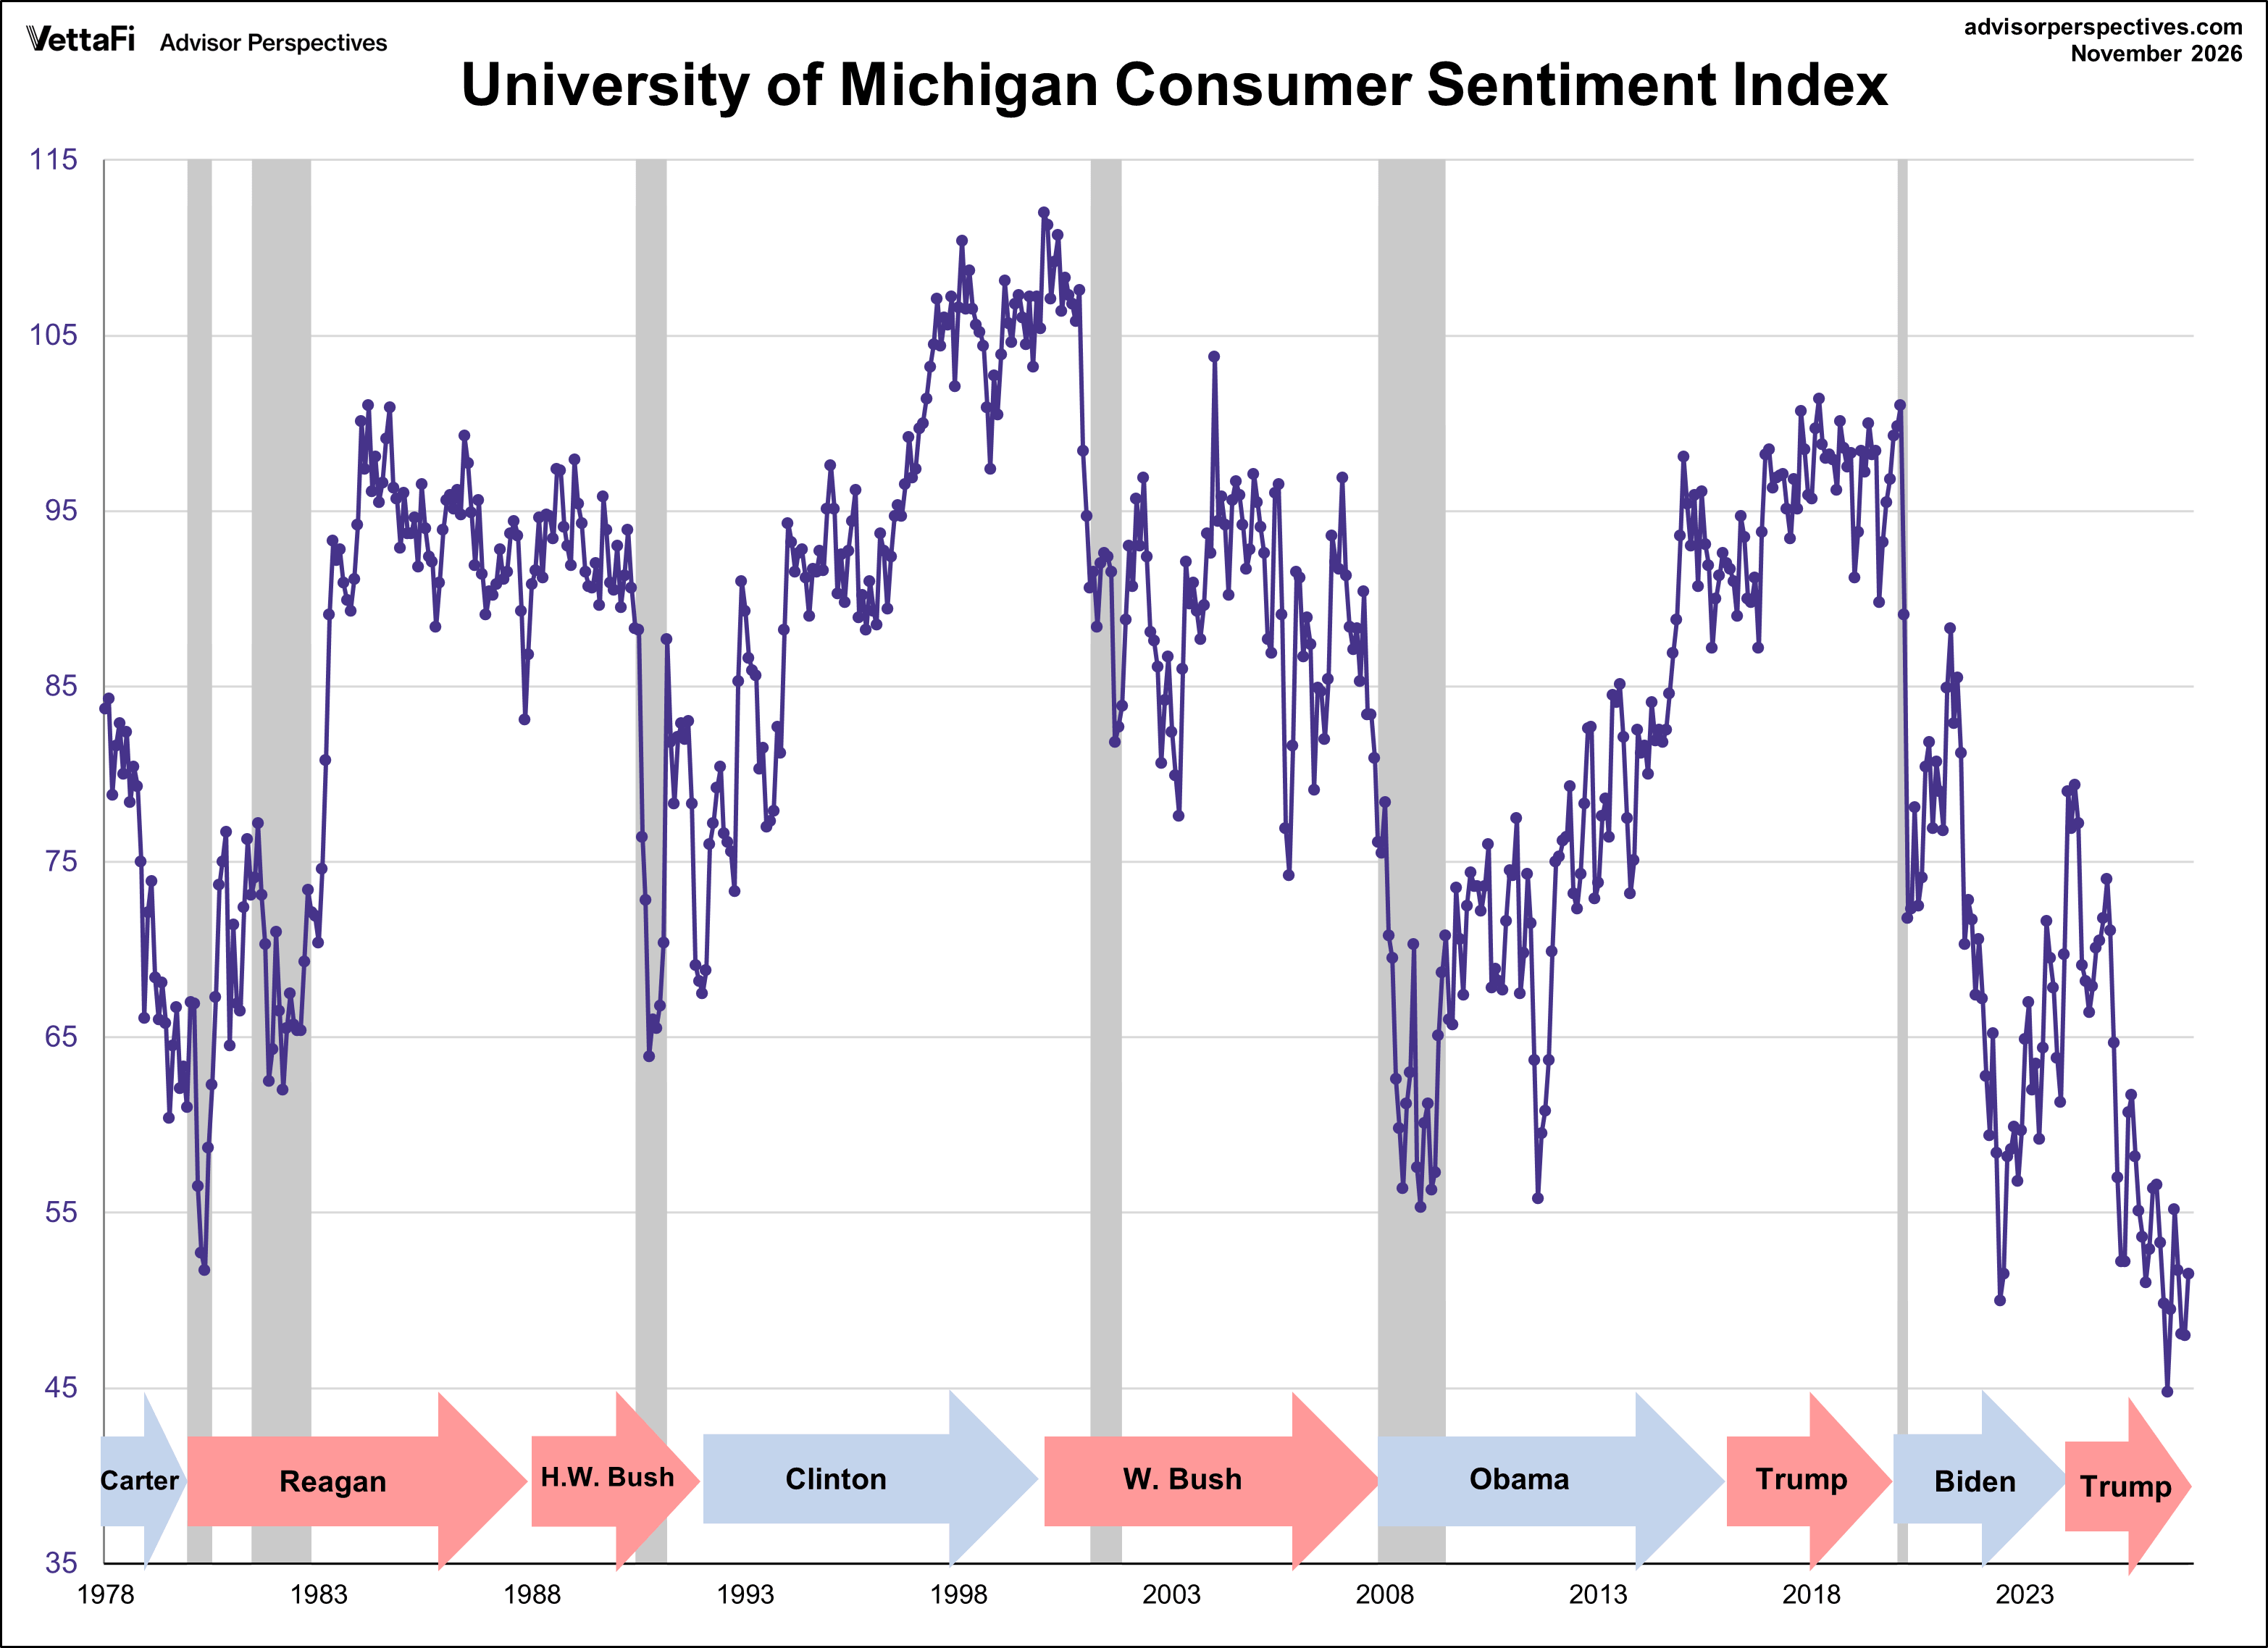
Each month, the survey results highlight sentiment within each political party. Sentiment is often viewed through a partisan lens, but the data shows that sentiment has fluctuated both positively and negatively under both Republican and Democratic administrations. As the chart below illustrates, the current "plunge" is a rare moment of bipartisan agreement, with declines seen across the political spectrum as energy costs hit every household.
University of Michigan Consumer Sentiment Index: Components
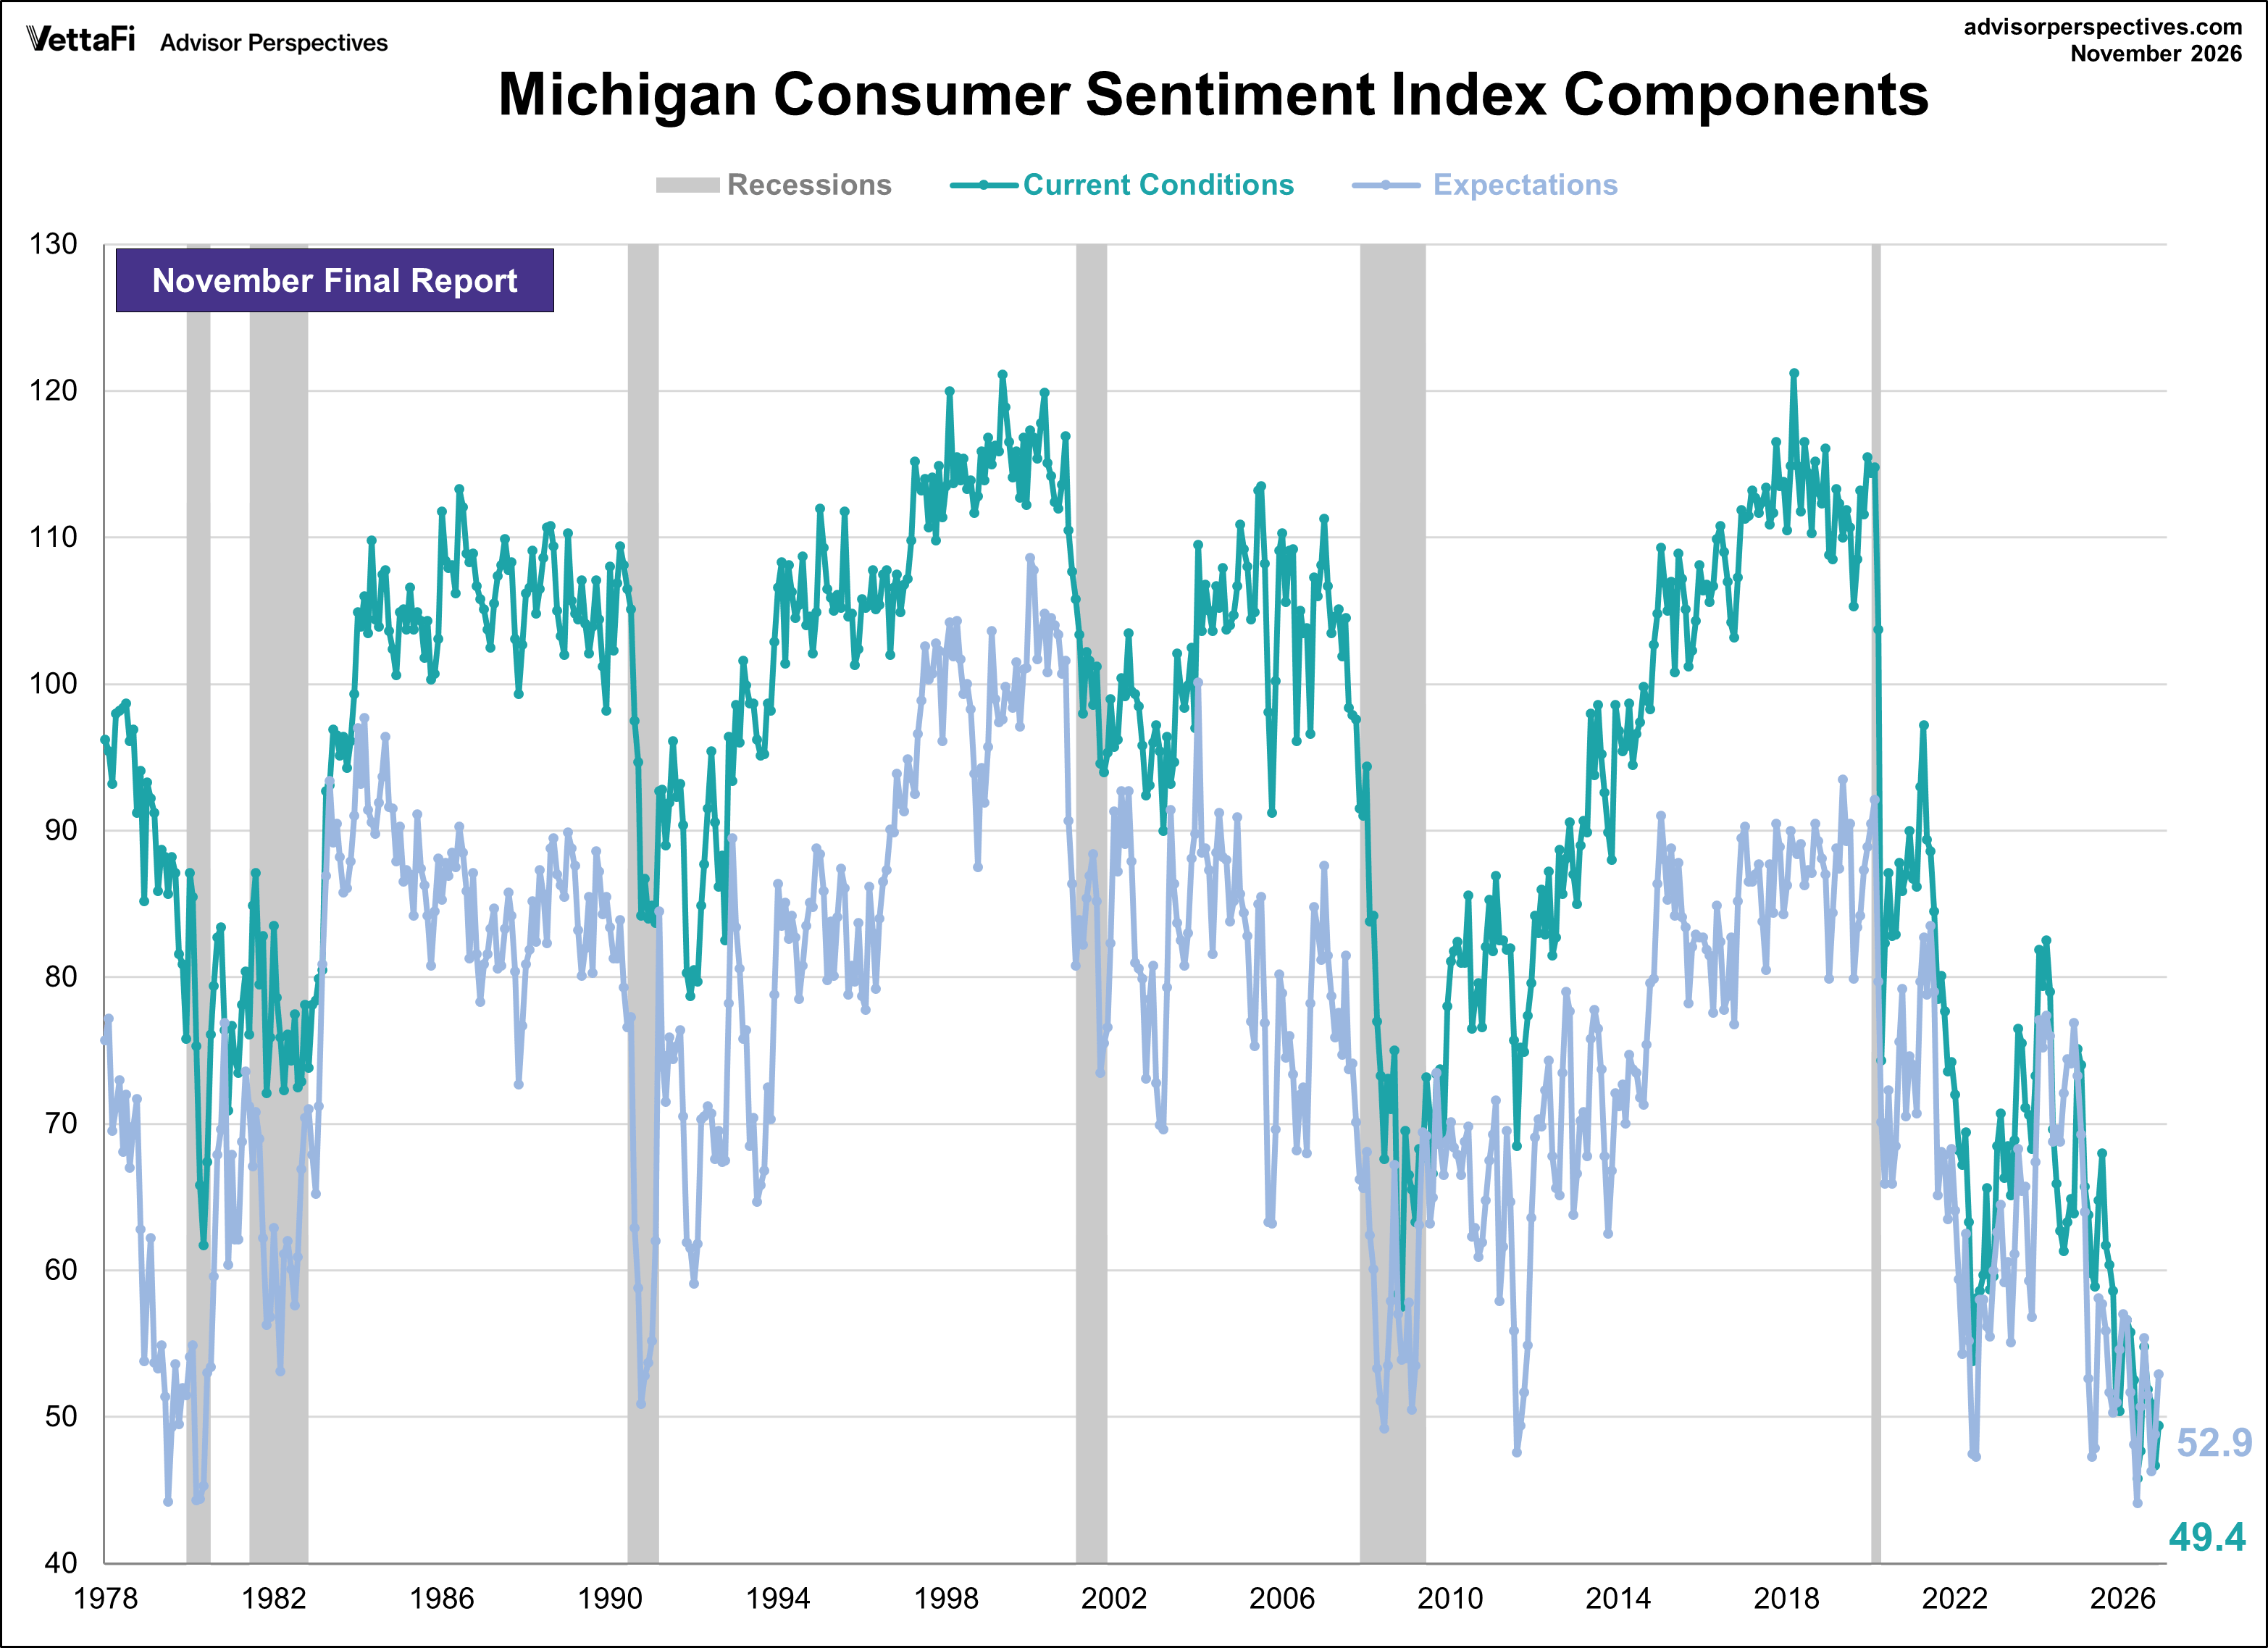
The Michigan Consumer Sentiment Index consists of two sub-indexes: the Current Economic Conditions Index (CECI) and the Consumer Expectations Index (CEI). The CECI reflects consumers' views of their current financial situation and the overall economy, while the CEI gauges their outlook for the future.
Current Economic Conditions Index (CECI)
The Current Economic Conditions Index fell to 49.4. This represents a 5.8 increase from the previous month and a 3.3% drop from a year ago. The latest reading was lower than the forecast of 51.0.
Consumer Expectations Index (CEI)
The Consumer Expectations Index fell to 52.9. This represents a 8.4% increase from the previous month and a 3.7% increase from one year ago. The latest reading was higher than the forecast of 50.9.
University of Michigan Consumer Sentiment Index: Inflation Expectations
Median year-ahead inflation expectations plunged from 4.7% last month to 3.7% this month. Still, it remains meaningfully above the 3.4% seen in February before the Iran conflict began, along with all 2024 readings. Long-run inflation expectations ticked down from 3.5% in October to 3.3%, higher than their 2024 range of 2.8% to 3.2%. Despite the softening in inflation expectations, consumers continue to report overwhelmingly that inflation—rather than unemployment—will cause greater hardship for consumers in the next one or two years.
The next update to this report will be published on December 4th.
Other Sentiment Indicators
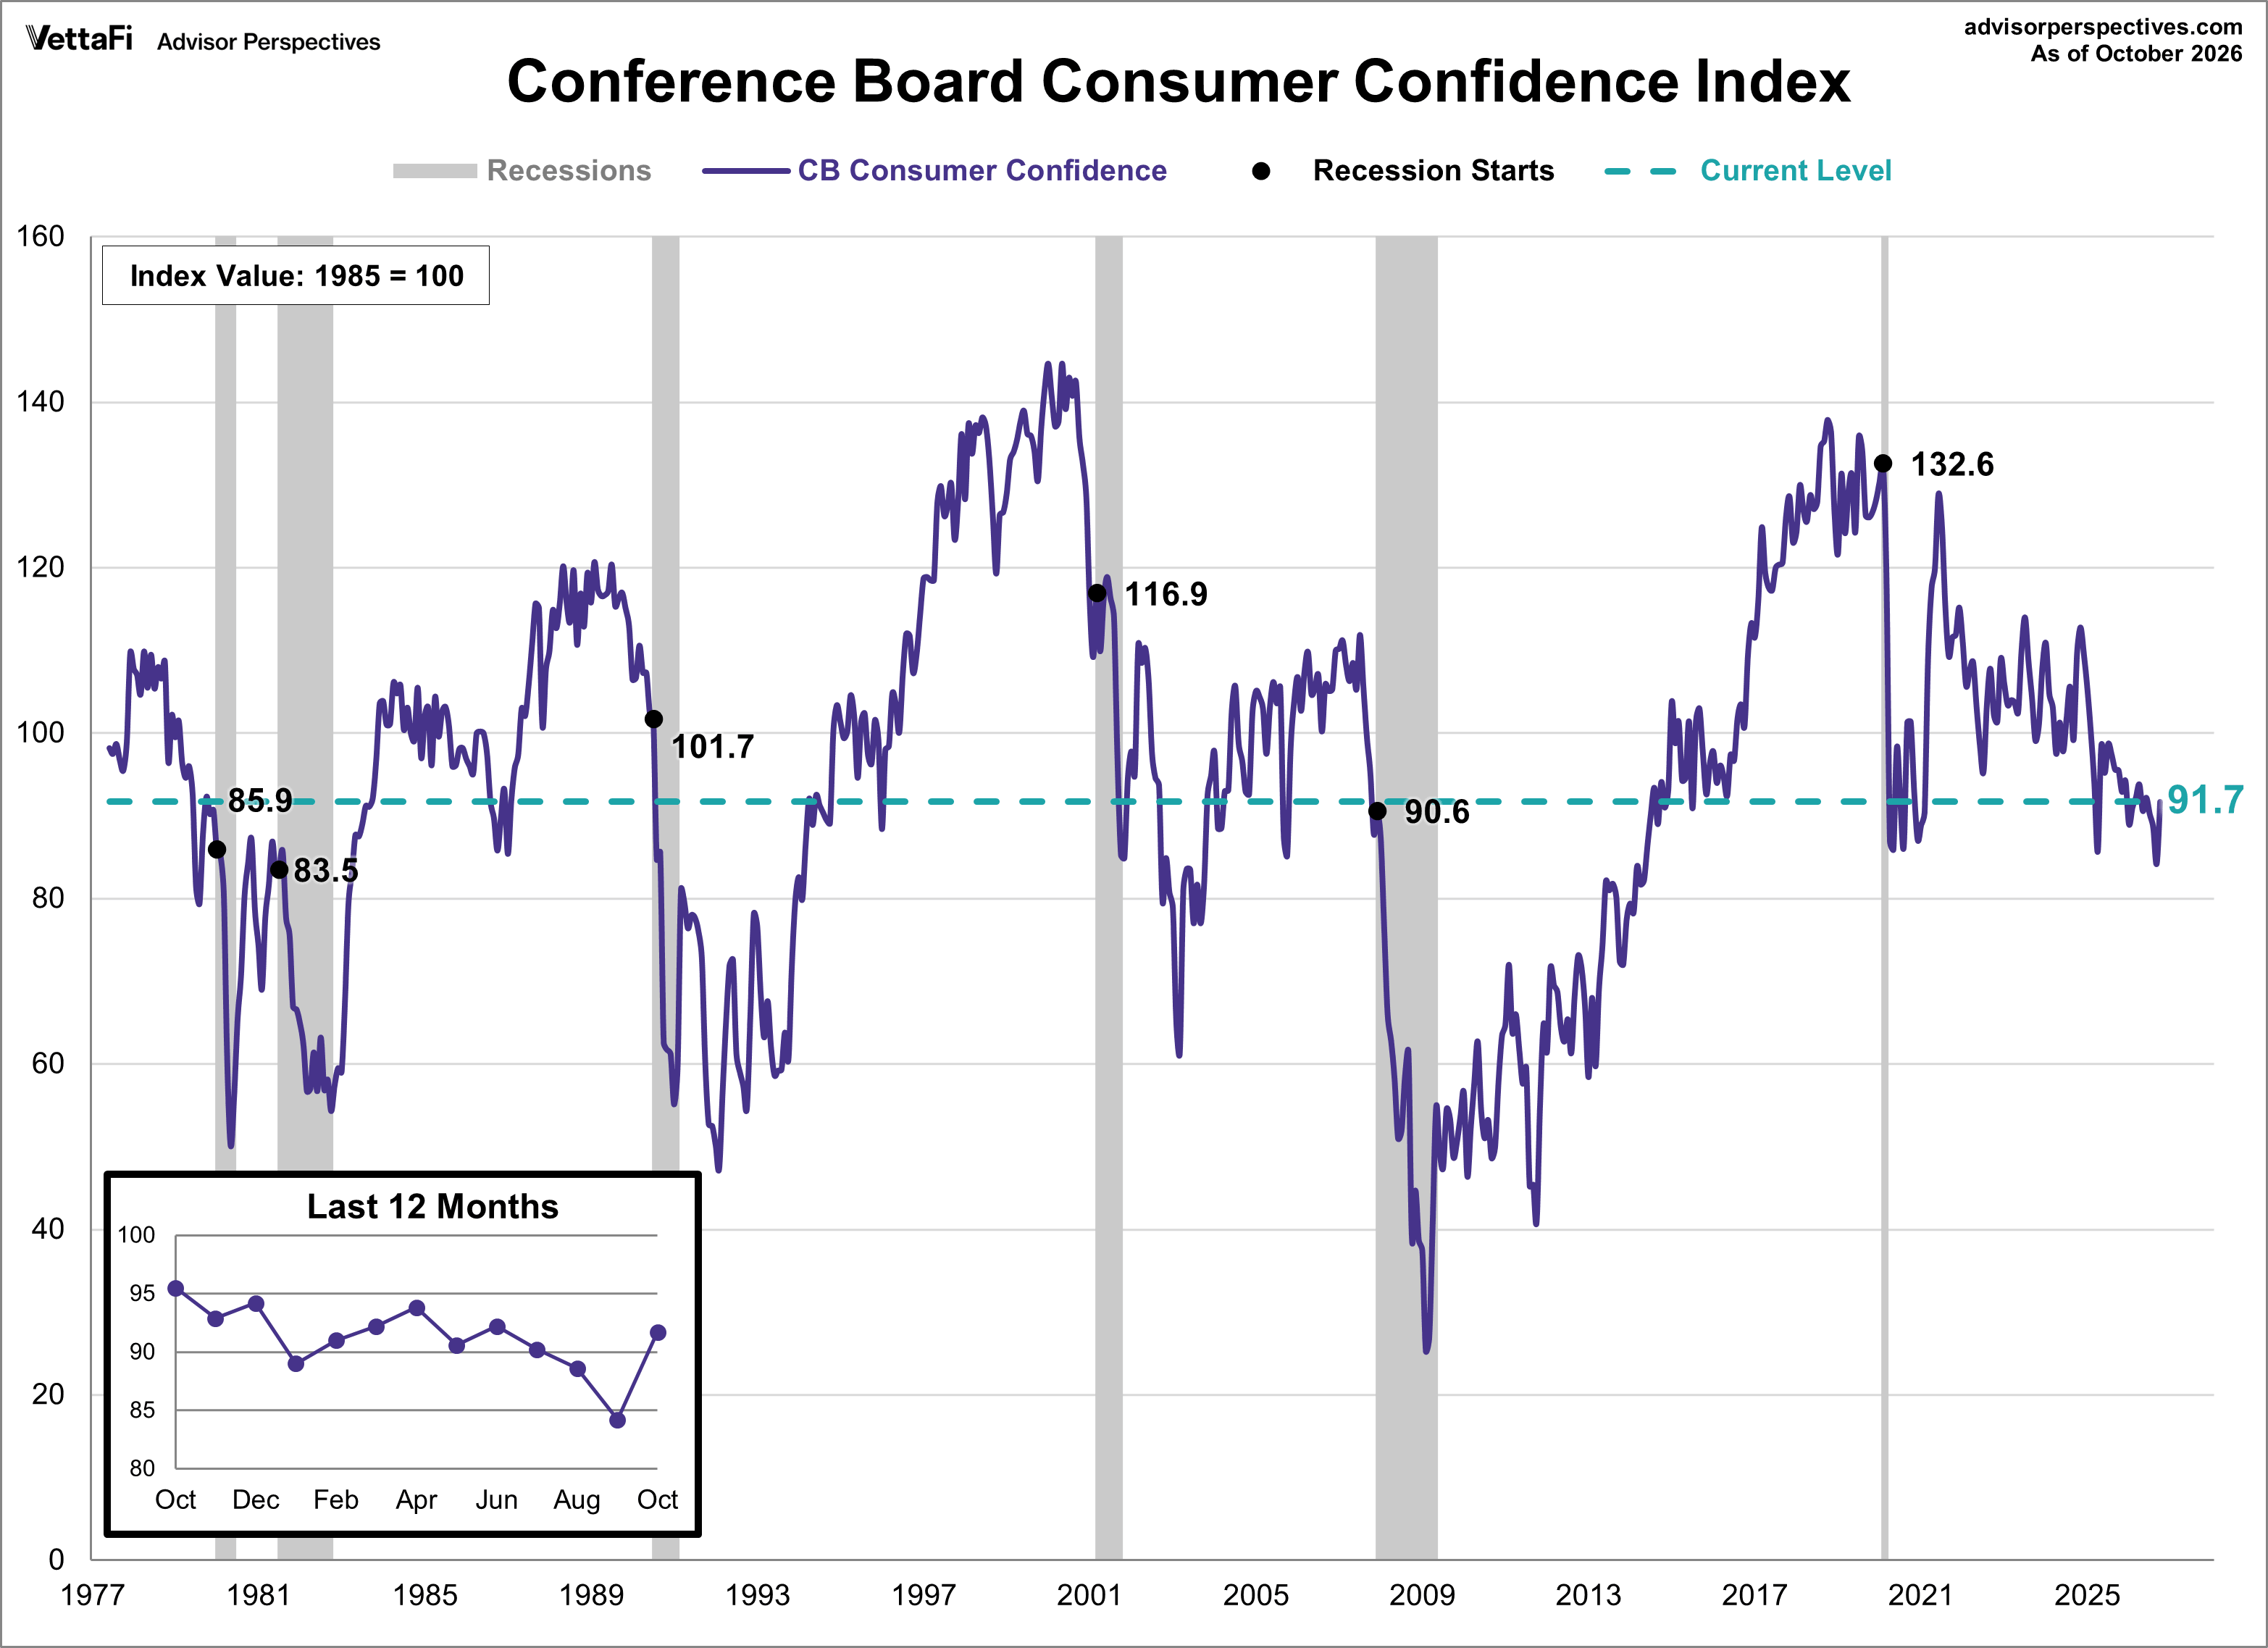
For an additional perspective on consumer attitudes, see the most recent Conference Board's Consumer Confidence Index. Both indexes gauge consumer attitudes toward the current and future strength of the economy. However, the Consumer Confidence Index is more influenced by employment and labor market conditions while the Michigan Sentiment Index is more focused on household finances and the impact of inflation.
The Conference Board index is the more volatile of the two, but the broad pattern and general trends have been remarkably similar to the Michigan index.
And finally, the prevailing mood of the Michigan survey is also similar to the mood of small business owners, as captured by the NFIB business optimism Index (monthly update here).
ETFs associated with sentiment include: Consumer Discretionary Select Sector SPDR Fund (XLY).
More Income Topics >