A week filled with hotter inflation readings brought growing concerns about the sustainability of the pace of AI spending. Despite rising inflation, bond yields ended the week lower. While the S&P 500 Index of large-cap stocks fell 1.95 percent for the week, the decline was largely driven by its heavy weighting to technology stocks, which faltered by 6.37 percent.
While don’t think of myself as being old, I can’t call myself young anymore. When I go to the gym, it takes me longer to stretch than to work out. People my age debate the best vitamin supplements, not the best burger joints. When I am asked for identification at the market, it isn’t to confirm I am old enough to buy beer; it’s to see whether I am eligible for a senior discount.
Earnings now have become the central market focus this week. Bank results have been somewhat mixed, and the market will need confirmation that profits outside the largest technology companies are strengthening. I still do not believe the overall equity market is excessively valued, but investors should expect continued volatility between growth and value as expectations for AI spending shift.
Predicting the direction of interest rates is challenging enough when economic conditions are relatively stable. Add persistent inflation, a resilient economy, a cooling labor market, geopolitical uncertainty, and an expanding supply of Treasury debt, and the challenge becomes considerably greater.
The AI agent catalyst. Meta's September launch of Muse, a personal artificial intelligence (AI) agent designed to act on a user's behalf across digital workflows, crystallized the market's latest disruption narrative.
Fed rate hikes could climb further than markets expect, according to T. Rowe Price Capital Markets Strategist Tim Murray.
The US Treasury market is entering a new era. Financing government debt is becoming less about capital availability and more about the yield required to attract it.
Narratives are almost always wrong: clever stories that explain the past and say nothing about the future. One may be right. AI may become the dominant technology of the century and render much of the present economy obsolete.
This year, the software sector has been one of the worst-performing pockets of the leveraged loan market amid fears that AI would severely disrupt existing business models. The sector’s underperformance has also weighed on the leveraged loan asset class as a whole, given its more than 10% weight in the overall Morningstar LSTA US Leveraged Loan Index.
Chris Galipeau and Taylor Topousis discuss high-conviction insights that go beyond media headlines.
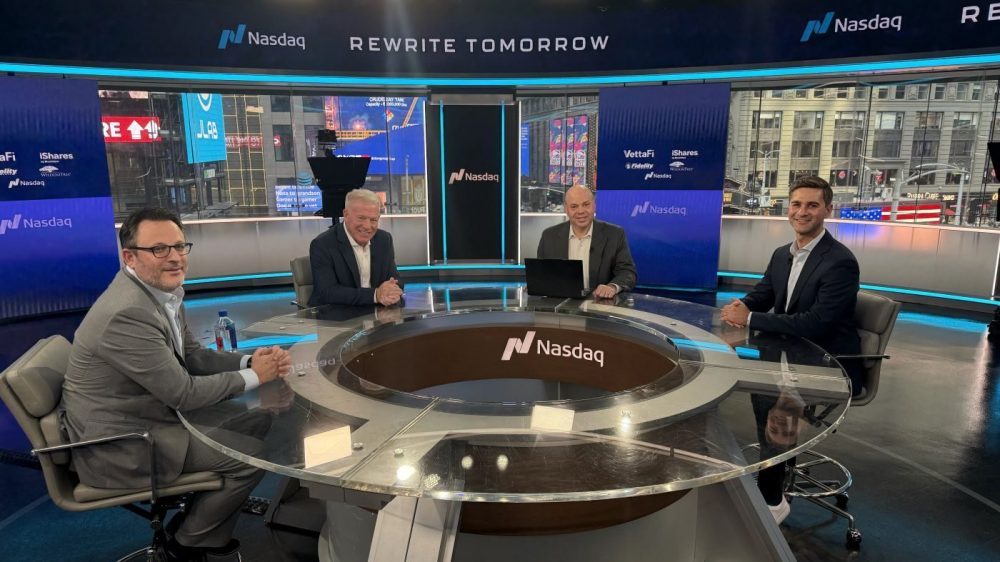
The Nasdaq-VettaFi Asset Allocation Summit this week included insights from leaders at key asset managers discussing the major decisions that advisors are facing. With costs rising and many investors at or near retirement, fixed income and income ETFs, specifically, took up a big part of the conversation. Leaders from BlackRock, WisdomTree, and Fidelity Investments all shared their views on both the fixed income outlook and the use cases for fixed income ETFs right now.
The link between AI capex and earnings carried roughly half of this year’s profit growth, and that support fades once spending stops accelerating, even at a record level. The earnings bill doesn’t arrive when the spending stops. It arrives when the spending stops growing.
Third-quarter earnings season kicked off this week and expectations are high. Despite the headwinds of higher oil prices and interest rates, economic growth has remained resilient, while the AI investment boom continues to gain momentum. As a result, the S&P 500 is expected to deliver 29% year-over-year earnings growth, marking a third consecutive quarter of 25%+ gains.
Plenty of story-stocks and recent alpha generators are outside AI glamor companies. Absolute and relative strength have ticked up in real-economy sectors that were beaten up as investor dollars flowed to tech. Macro conditions, such as ebbing Treasury rates and the upcoming U.S. midterm elections, are wildcards. Still, traders and portfolio managers should listen up for commentary in perhaps unusual places this earnings season.
Artificial intelligence (AI) and the Federal Reserve rate hike have dominated headlines recently—and investors might be wondering how these things will affect them.
Fall is officially underway, heralding a season of change — and what a difference three months makes. The past quarter brought a dramatic Federal Reserve policy pivot and notable shifts in market sentiment and ETF trends. But within equities, the most striking reversal occurred inside the AI trade itself.
We believe the combination of AI, robotics, space technology, and quantum computing will be primary drivers of future economic growth.
Discover how strong corporate earnings, AI capex cycles, and 5%–10% fixed income yields outweigh midterm election and Fed rate uncertainties.
There is a general framework to inflation, and it is older than any of us. Prices can rise because buyers are bidding for scarce goods with money they’ve actually earned. Or prices can rise because the cost of producing something has jumped for reasons unrelated to demand.
The third quarter of 2026 emphasized an increasingly divided macro regime for financial advisors and institutional allocators alike. On one end, broad market hopefulness drove steady capital deployment into broad-market beta, while on the other end, raised rate volatility and geopolitical tension forced strategic pivots across fixed income, real assets, and systematic strategies, according to BlackRock’s Q3 earnings call, released October 14.
Over the last decade, a series of policy decisions in DC support the reindustrialization of the United States. Key policy movers include investments in infrastructure, tax policy that allows significant tax benefits for corporate capital expenditures (capex) and domestic research and development, the CHIPS & Science Act and tariff policies, especially the sector-specific 232 tariffs.
In this commentary, we look at three themes shaping our thinking: a shift in who is leading the market, the return of income as a meaningful source of return, and an economy that, in our view, is growing steadily rather than heading toward either extreme.
Corporate bond yields are high, but spreads are low. Low spreads are supported by strong corporate fundamentals, and high yields might help offset potential price declines.
Matthew Bielski, founder and CEO of Defiance ETFs, recently joined Scarlet Fu and Eric Balchunas on Bloomberg’s ETF IQ to discuss the Defiance Autism Impact ETF (ASD) and the personal family experience that helped inspire its development.
As we enter the final quarter of 2026, the investment backdrop remains constructive but increasingly differentiated. Economic growth and corporate earnings have remained resilient, while continued investment in artificial intelligence (AI) and other productivity-enhancing technologies has supported capital spending and market sentiment.
Today, we are going to look at some of the cracks which are becoming visible in the AI space. It will change the nature of index investing, the economy and portfolio management for the next decade. And generally, not in a good way as far as current AI investors are concerned.
In more normal periods like today, hiring broadly matches the labor force growth, and unemployment holds steady. Labor force growth has slowed to about 0.5% a year, so payroll gains have slowed too. Payrolls rose only 29,000 in September and averaged about 45,000 a month over the past year, yet unemployment is still a low 4.2%.
We agree that the economy has appeared remarkably resilient at the aggregate level, and that modest further rate increases may not put overall growth at risk. But the more important question for portfolios is not the level of inflation; it is its sensitivity to rates.
Panic is never a good investment strategy—nor is greed. Here's how disciplined investing helps navigate through volatile environments.
In the AI-led markets of recent years, companies with distant profit potential have been favored. But higher interest rates could change the equation and create a new advantage for value stocks, whose businesses tend to have more visible cash flows in the shorter term.
An income projection can provide an important starting point for year-end tax planning. Explore key 2026 tax brackets and income thresholds that may help inform planning decisions before year-end.
Learning how to value stocks starts with a question you already understand: What am I getting for the price I’m paying?
Central banks are tightening, and stocks are still within reach of their highs. The Fed hiked on September 16 for the first time since 2023, and the 10-year Treasury yield touched 5.34% this month, its highest level since 2002. Even so, the S&P 500 sits within roughly 2.5% of its record, and Japanese equities recently set fresh all-time highs.
As we round the three-quarter pole and head into the final stretch of 2026, the prevailing investment narrative has, of course, been AI, along with its pros and cons. Since March, when the Iran conflict began, there has been a secondary drumbeat that continues to get louder and louder: the narrative surrounding bond prices, interest rates, inflation, and the economy.
In light of accelerating global fragmentation and geopolitical conflict, many governments and businesses are investing in resilience. That imperative has coincided with the emergence of AI, a technology that can expand the frontier of what is possible. As a result, technology security is becoming a pillar of national economic security strategy.
Q3 was a period of transition in the bond market thanks to Federal Reserve changes, a surge of AI-driven debt issuance, and rising interest rates.
As AI in wealth management becomes more prevalent, recent research from Vanguard suggests that technology may actually increase investors’ appreciation for human expertise.
BlackRock, WisdomTree, and Fidelity Investments had representation at the recent Nasdaq VettaFi Asset Allocation summit.
In a recent webcast, Ari Polychronopoulos, TMX VettaFi’s head of RAFI Indices™, and Brent Leadbetter, TMX VettaFi’s head of RAFI Distribution, discussed growing market concentration risk.
Last week, the NEOS Nasdaq-100 High Income ETF (QQQI) crossed $15 billion in assets under management. This major milestone was the result of investor demand. In the first nine months of 2026, the tax-efficient options-based ETF had $7.0 billion in net inflows. With the help of the $13 billion NEOS S&P 500 High Income ETF (SPYI), NEOS has firmly established itself as a premier manager for enhanced income ETFs.
We are often asked to predict interest rates, typically because investors hope to invest at the most opportune moment. The motivation is understandable, but the ability to consistently identify that moment is questionable. Voluminous economic data, geopolitical events, shifting monetary policies, and ever-changing economic conditions make forecasting interest rates an unrealistic exercise.
Inflation, geopolitical fragmentation and concentrated, AI-driven markets have put a premium on investors’ ability to navigate directional moves across asset classes. We think systematic trend-following strategies can help chart a course. But how they’re designed matters.
Many investors underestimate the AI exposure already embedded in diversified portfolios. Michael McNurney explains how to evaluate AI enablers, creators and beneficiaries while balancing long-term opportunity against short-term valuation and concentration risks.
While redemption pressure in nonlisted BDCs (funds that invest in small and midsize private U.S. businesses) has eased from its peak, it remains materially above the industry standard 5% quarterly redemption threshold. As a result, capital continues to leave the asset class, forcing managers to look to preserve liquidity, moderate deployment, and, at the margin, tighten financing conditions.
One of the hallmarks for the U.S. economy over the last few years has been its resiliency. This calendar year has been no exception as the war in the Middle East led many a market prognosticator to pencil in the potential for a recession stemming from the effects of the Middle East war.
In a week marked by continued concerns about rising interest rates, the bond market found some relief after two large Treasury auctions of 10- and 30-year securities were well received by investors. The week’s most significant development came Thursday, when questions emerged about OpenAI’s revenue. Reports suggested revenue was running at a $50 billion annual pace, well below the $70 billion investors had expected.
In this article, Russ Koesterich discusses how tech strength is hiding broader market weakness, as higher rates begin to weigh on rate-sensitive sectors.
Gold and silver finally put a winning week on the board. But the more revealing development is what happened while prices were falling: investors poured billions into gold-backed funds, and China stepped up its purchases of physical gold.
Every time I clean out my wardrobe, I find items I have not worn in years but cannot quite bring myself to give away. Maybe they will come back into fashion. Maybe they’ll fit again one day. Or maybe getting rid of them simply feels harder than buying them did.
Sound and stable money promotes long-term economic growth. And “independent” central banks are more likely to deliver it. For most of the 1800s, the US was on the gold standard, which meant policy was insulated from political interference. But once the Federal Reserve was created in 1913, it became susceptible to political pressures.