VettaFi is the index provider for NUKZ, for which it receives an index licensing fee. However, NUKZ is not issued, sponsored, endorsed, or sold by VettaFi. VettaFi and its affiliates have no obligation or liability in connection with the issuance, administration, marketing, or trading of NUKZ.
You do get rewarded for pushing duration out, with a steep increase from 30 days to one year, and a more moderate — but still substantial — increment in return for going out to five years.
Politicians, particularly when they’re on the winning end of the deal, often say “elections have consequences.” It’s true. And it’s wisdom that advisors and muni bond investors need to remember.
Many investors are reliving that experience with AI. Buffett, who stepped down as chairman of Berkshire Hathaway Inc. earlier this year, and Munger, who died in 2023, won’t be active examples, obviously. But there are useful lessons in the way they weathered the previous tech revolution — and in how their decisions turned out all these years later.
In this article, I explain what credit spreads are and why they matter to stock investors. I also examine what they are signaling today by reviewing key spreads across the credit curve, historical percentiles, and relative value metrics.
Hedge funds dumped technology stocks at one of the fastest paces on record last week, and the momentum crash that followed was the biggest in about 40 years. Even so, few on Wall Street are ready to call time on the AI boom.
A client considering a passive ESG fund may associate “passive” with the low-cost, diversified market exposure familiar from broad-market index funds. But understanding how the fund tracks its index is different from understanding the sustainability judgments that index expresses.
Morgan Stanley struck a deal to buy a fintech to bring a key technical aspect of handling corporate stock plans in house, further beefing up the bank’s massive wealth-management arm.
I try not to write about politics in this letter. I’d rather focus on economics and investments. But this week, politics impacts economics so we need to address it. Let me see if I can express what I think many voters were feeling.
The most important number in October’s inflation reports wasn’t the one that made the headlines. Everyone watched the Consumer Price Index print 3.7%. Far fewer noticed the Producer Price Index for final demand. It jumped 1.3% in a single month, the largest gain since March 2022, and the annual rate hit 6.3%.
The big message from the midterms is that Americans are struggling with the cost of living. In case anyone missed it, they need relief now. This will put even more attention on the Federal Reserve: Will Chair Kevin Warsh do all he can to bring down inflation or placate the White House, which wants lower interest rates?
In a recent letter to investors, Paul Singer’s Elliott Investment Management predicted a substantial bear market ahead. There might be an abrupt change from fear of missing out, or FOMO, to fear of getting obliterated, or FOGO, the $80 billion manager wrote.
What will protect portfolios when U.S. stocks tank, especially when inflation is also a concern? I think real assets like commodities and real estate (especially farmland) will hold up, as will Treasury Inflation-Protected Securities (TIPS).
The magnitude of the Democratic victories in both the Senate and gubernatorial races was surprising and exceeded what many market participants appeared to be pricing. While the outcome is politically significant, investors should resist the temptation to view it as an immediate economic regime change.
A will can name guardians for minor children, designate an executor, and direct certain assets after your death. A trust serves a different role, including managing assets during your lifetime and controlling how they pass to beneficiaries. Understanding the distinction can help you build an estate plan that reflects your family, assets, and wishes.
In this educational video, Chuck Carnevale, Co-Founder of FAST Graphs, explores the fundamentals of stock valuation and demonstrates how investors can use earnings, growth rates, and historical valuation references to make more informed investment decisions.
The strong October nonfarm payrolls report has effectively settled the debate over what the Federal Reserve (Fed) is likely to do at its December Federal Open Market Committee (FOMC) meeting. We expect the Fed to raise the federal funds rate by another 25 basis points. Beyond December, however, the outlook remains far less certain. We continue to expect the Fed to remain on hold throughout 2027.
A global tech rout continues to remind investors that volatility can strike at any time. That’s especially true in today’s market environment, where stretched megacap technology valuations and broader equity indices have elevated concentration risk.
Domestic demand for gold bars and coins tends to rise modestly under Democratic administrations. However, elections have not historically had a significant impact on gold’s global performance over the long haul.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
Portfolio Manager Denny Fish explains why the market was justified in assigning a higher level of regulatory risk to the AI ecosystem after the midterm elections. But in his view, the secular strength of this theme, along with the massive bottlenecks and geopolitical implications, mean that this historic investment cycle will likely continue.
Franklin Templeton Institute’s Stephen Dover and Larry Hatheway opine on the US stock market’s recent volatility in the wake of the US midterm elections and the path forward for investors.
The Federal Reserve held short-term interest rates steady last week. If it does so again at its next meeting in December, it’ll need a better explanation.
Traditionally speaking, when one is choosing to lean into a particular sector of the equity market, they’re going to want to lean into the one that’s offering the best performance.
The big story last week? The Federal Reserve paused despite stronger growth and persistent inflation. It was a hawkish pause, with a December hike still the base case, according to Franklin Templeton Fixed Income. Third-quarter gross domestic product showed the US economy's resilience, but also its growing dependence on artificial intelligence investment, and household purchasing power took a hit.
In recent years, getting tech exposure was easy. You bought an index fund, whether a mutual fund or an ETF, and let the biggest names carry the portfolio. Now, those names make up such a significant share of large-cap indices that advisors are getting nervous. Indeed, many are looking elsewhere for the next stretch of compounding growth typically associated with the tech sector.
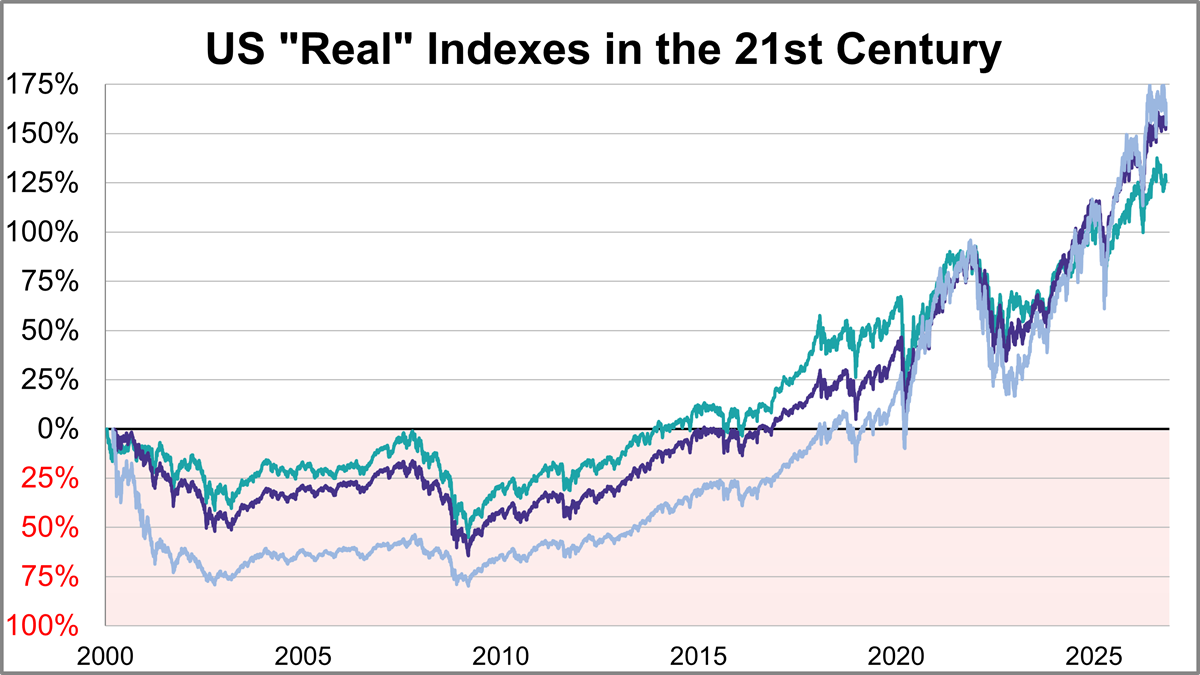
Here is a look at real (inflation-adjusted) charts of the S&P 500, Dow 30, and Nasdaq composite since their 2000 highs. We've updated this through the October 2026 close.
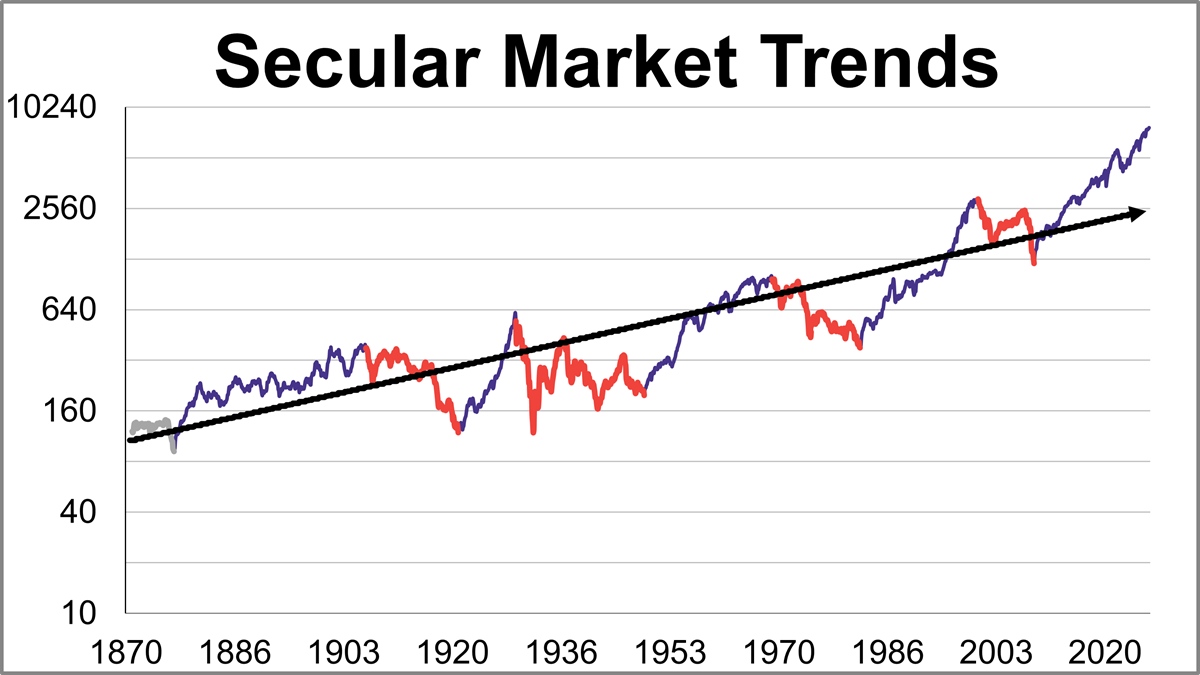
The S&P 500 real monthly averages of daily closes reached a its all-time high in October 2026. Let's examine the past to broaden our understanding of the range of historical bull and bear market trends in market performance.
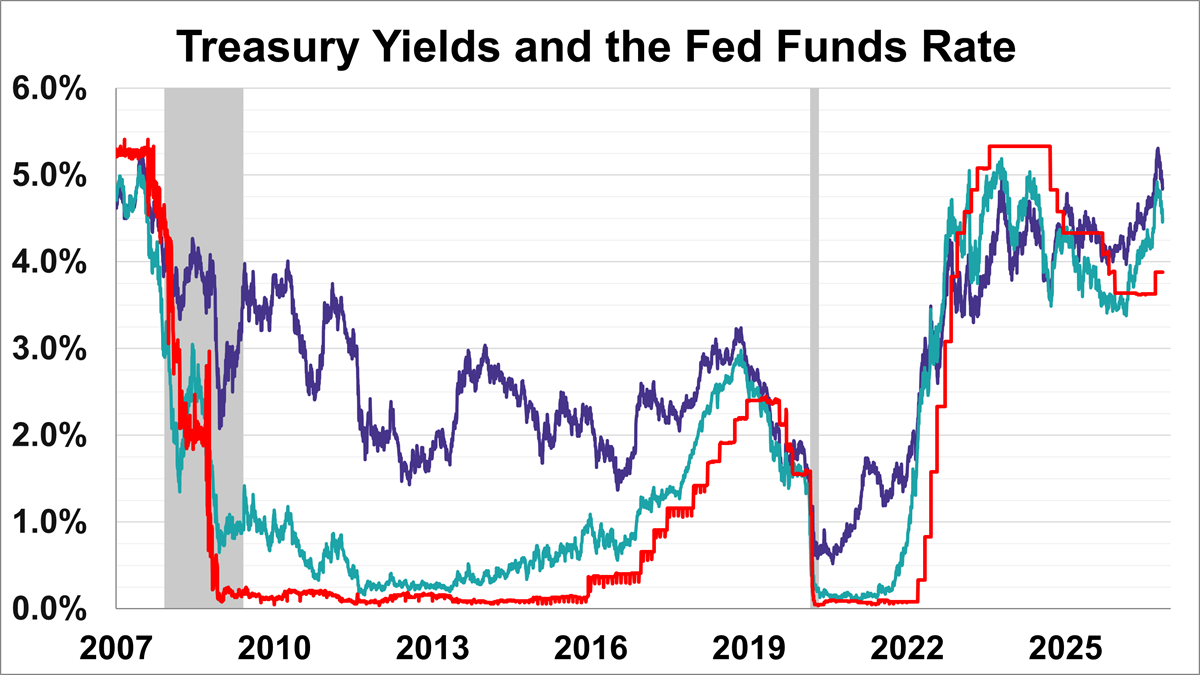
The yield on the 10-year note finished November 6, 2026 at 4.86% while the 2-year note ended at 4.51%.
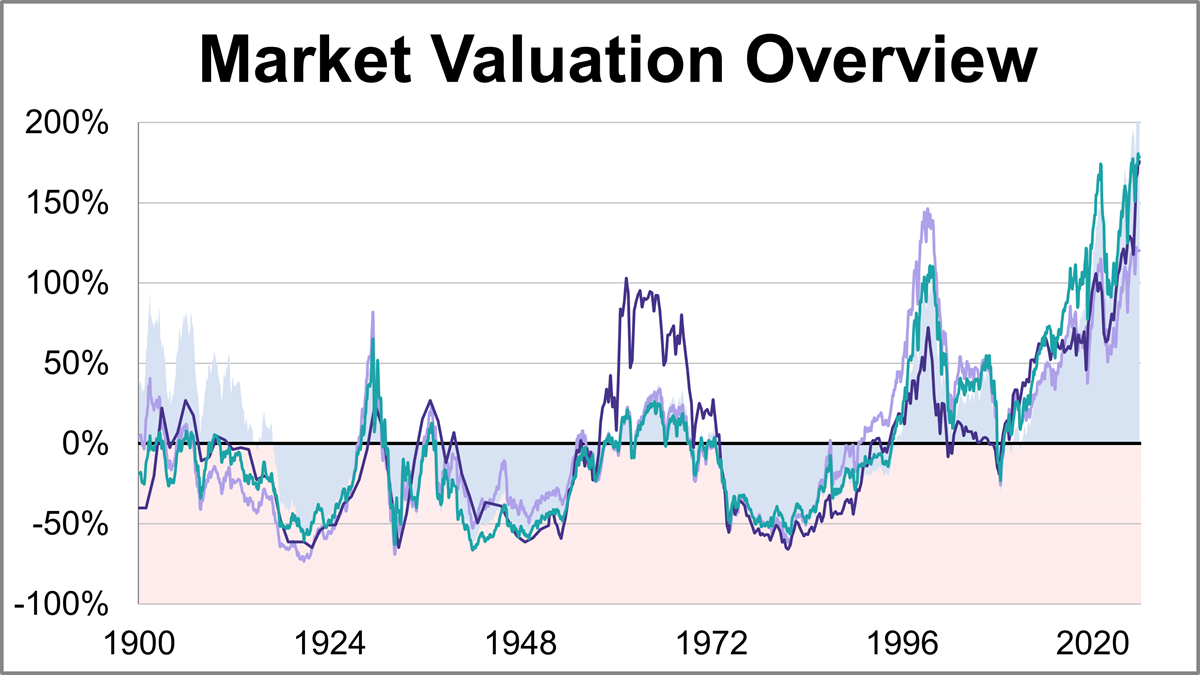
Here is a summary of the four market valuation indicators we update on a monthly basis.
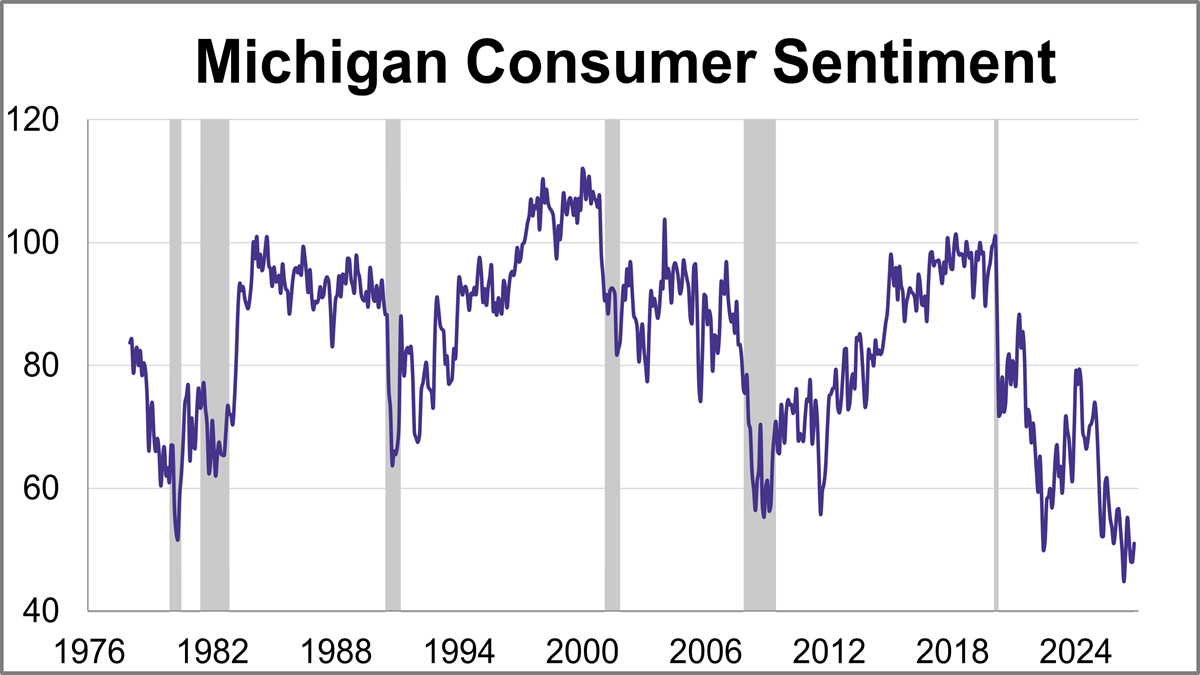
Consumer sentiment rises in November to the highest level in three months. The preliminary November reading for the University of Michigan Consumer Sentiment Index came in at 51.0. This marks a 6.3% (3.0 points) increase from October.
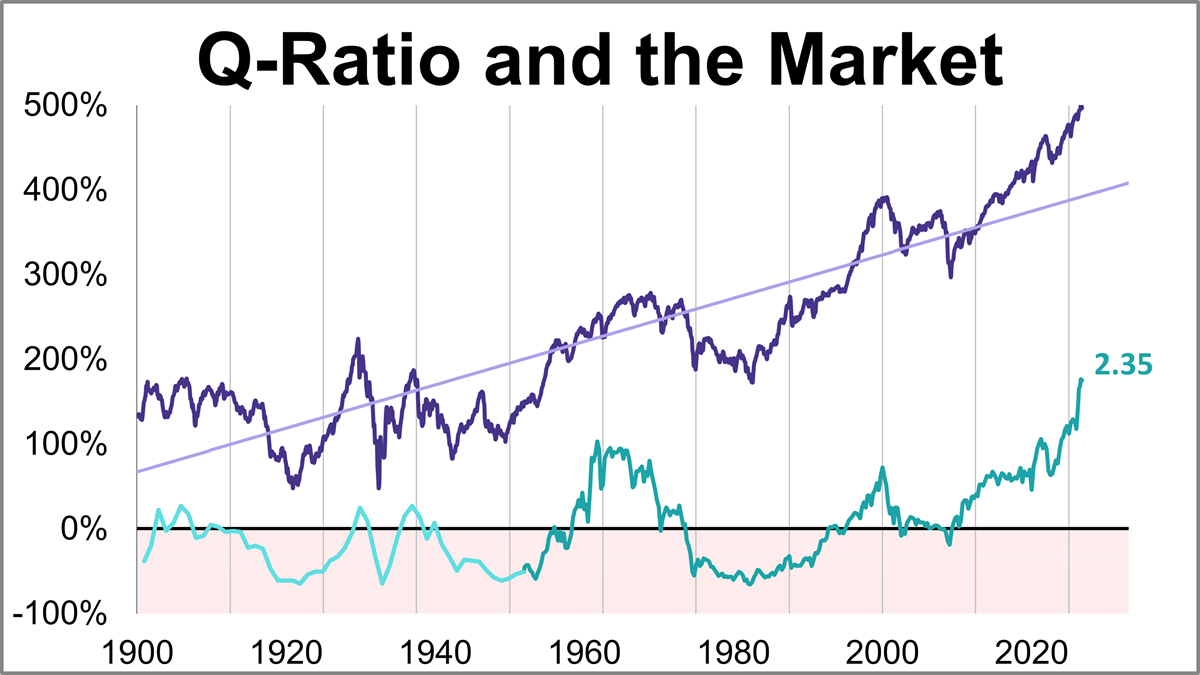
The Q Ratio is the total price of the market divided by the replacement cost of all its companies. As of October 2026, the latest Q-ratio is at 2.35.
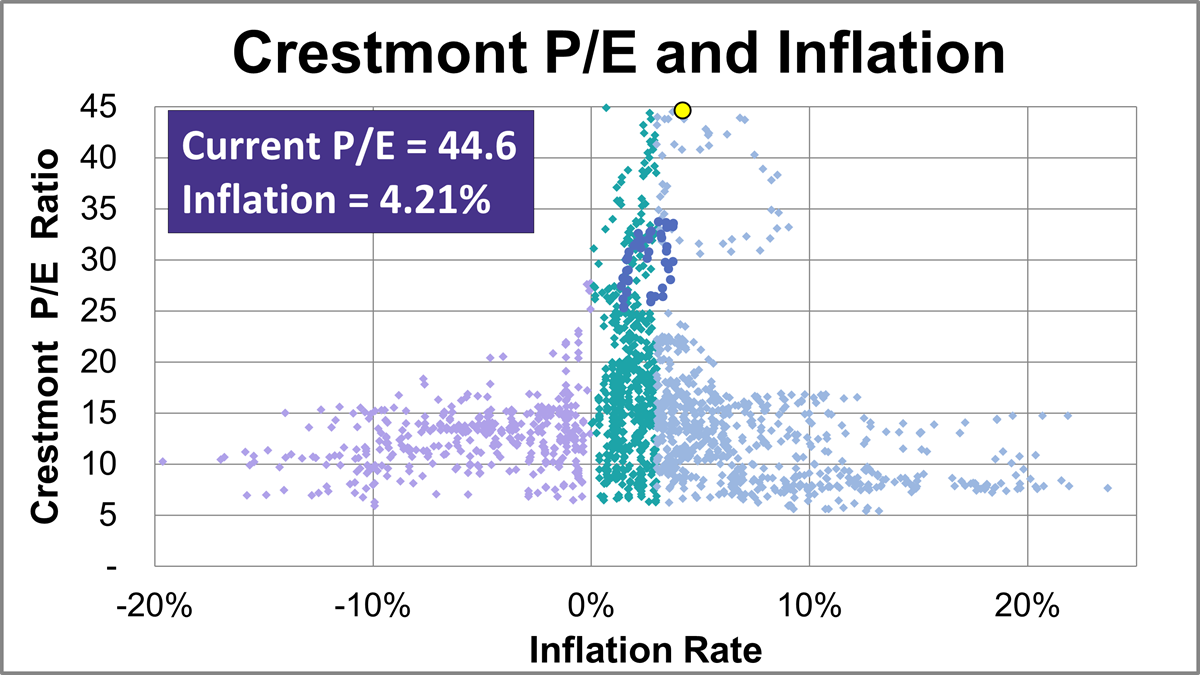
Based on October's S&P 500 average of daily closes, the Crestmont P/E of 44.6 is 189% above its arithmetic mean, 217% above its geometric mean, and is in the 100th percentile of this 14-plus-decade series.
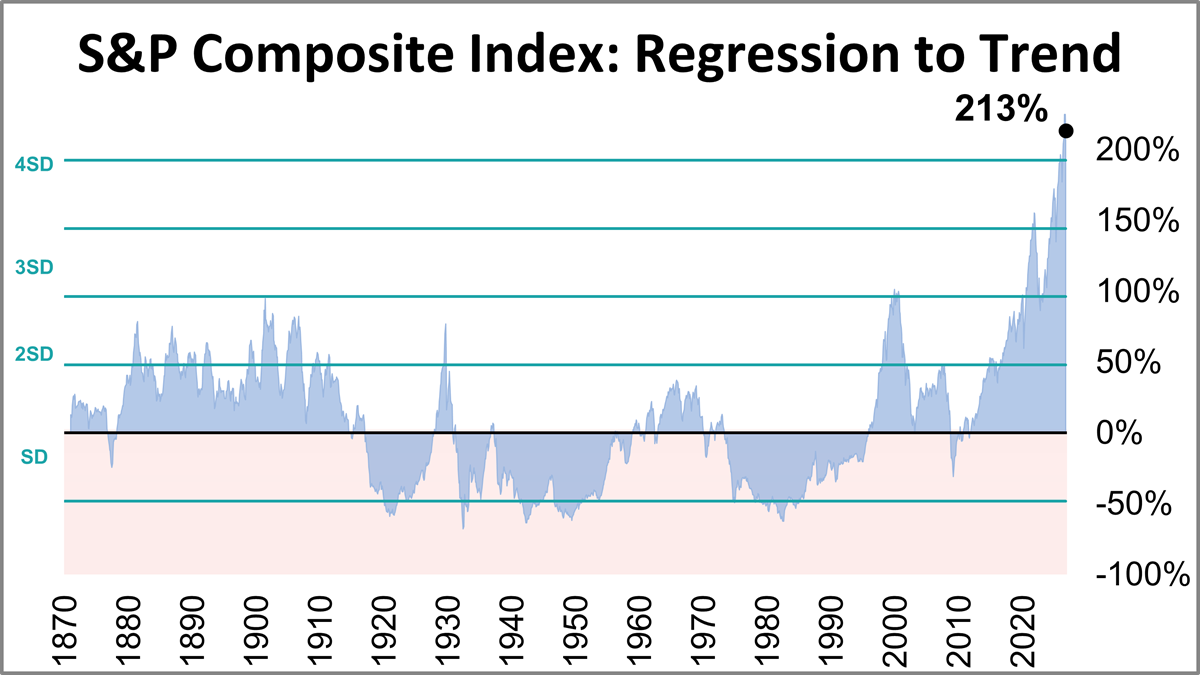
The inflation-adjusted S&P Composite Index was 213% above its long-term trend at the end of October.
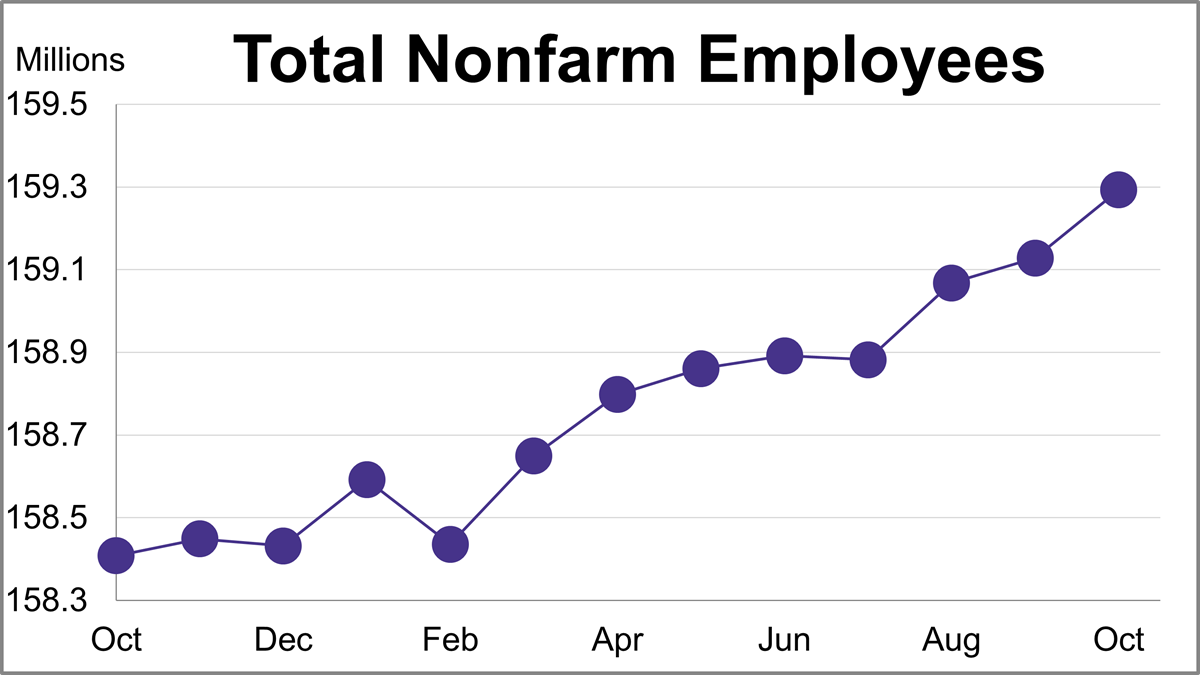
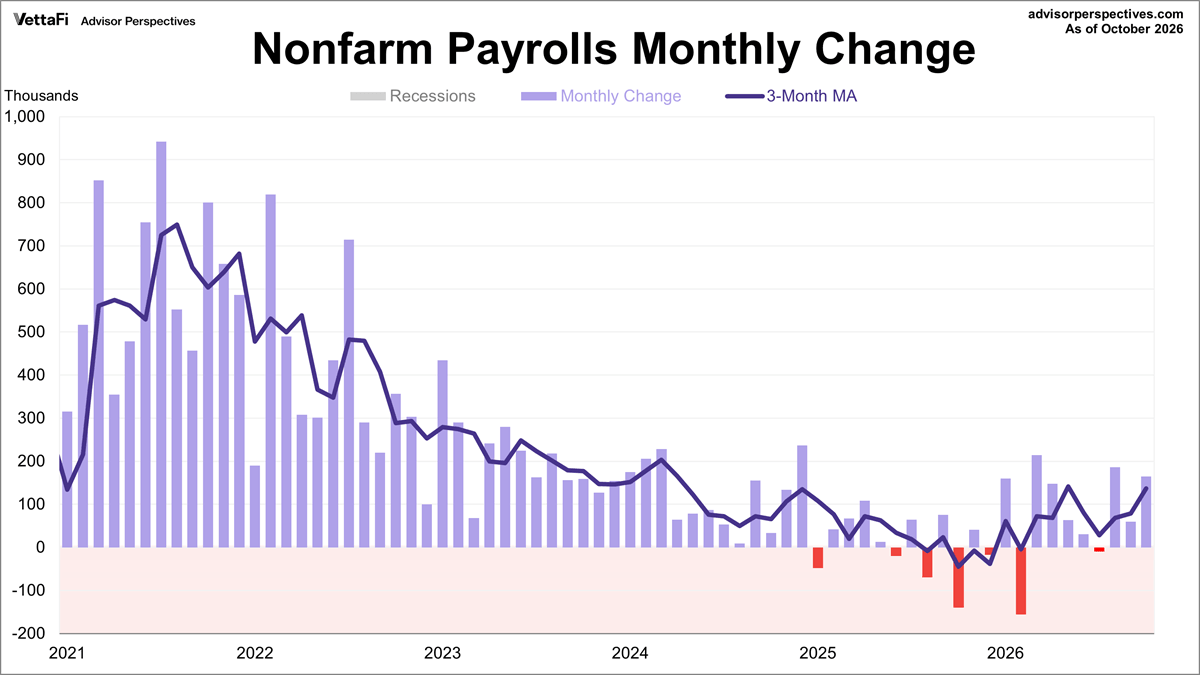
There is a general belief that there are four big indicators that the NBER Business Cycle Dating Committee weighs heavily in their cycle identification process. This commentary focuses on one of these indicators: nonfarm employment. In October, total nonfarm payrolls increased by 165,000 while the unemployment rate decreased to 4.1%
The latest employment report showed that 165,000 jobs were added in October, compared to September's 60,000 gain. This figure was significantly higher than the projected addition of 65,000 jobs. Meanwhile, the unemployment rate decreased slightly from 4.2% to 4.1%.
Treasuries dipped after an unexpected surge in US job growth led traders to add to wagers that the Federal Reserve will raise interest rates when officials next meet in December.
Fears of the worst-case scenario for the AI trade kicked in after the US midterm elections on Tuesday, in which Democrats secured majorities in the Senate and House of Representatives and won control of state houses and governor’s mansions across the country. Many of the winning candidates ran on anti-AI platforms, raising the possibility that the development of data centers could grind to a halt in many places.
The most-read stories in October for Advisor Perspectives were mainly focused on two key topics: retirement and TIPS. The most-read stories in October for Advisor Perspectives were mainly focused on two key topics: retirement and TIPS.
The unprecedented investment boom to build out the infrastructure for artificial intelligence is projected to reach more than $10 trillion, if all current plans are realized. The money is coming from many sources, including corporate cash flows, public equity and debt issuance, private debt issuance, off-balance sheet lease obligations and guarantees to AI data center developers from so-called hyperscalers and the leading chip provider, Nividia Corp.
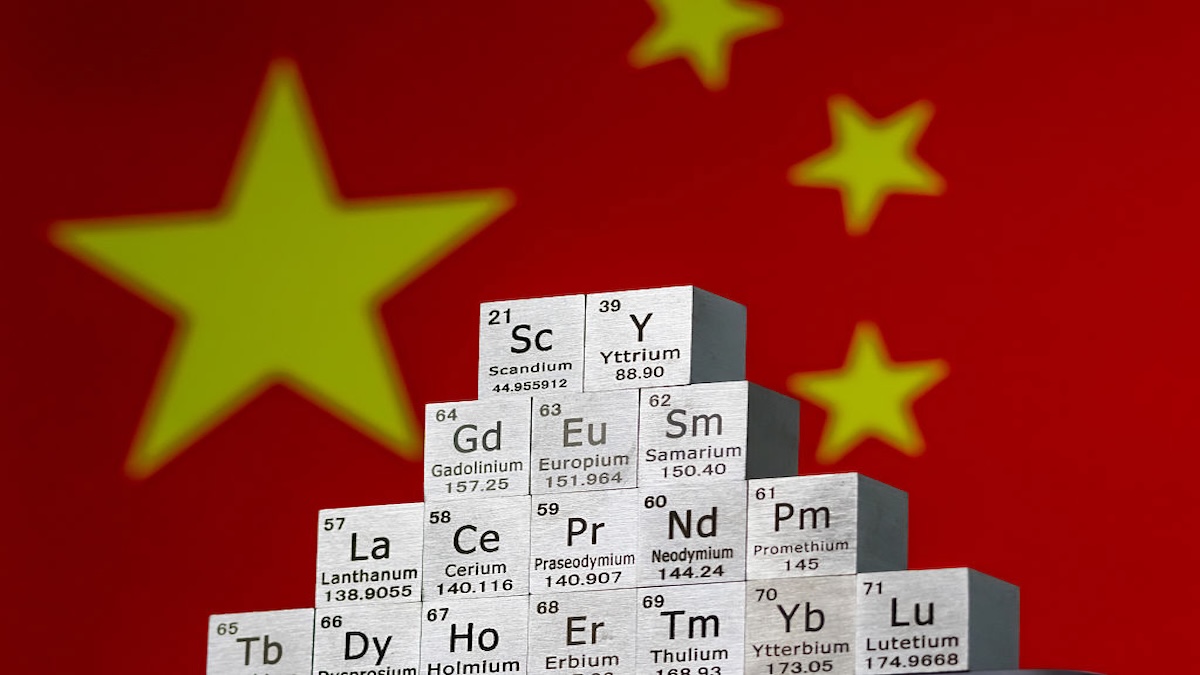
For years, companies trying to mine or process the rare elements vital to the performance of electric vehicles, drones, medical devices, LEDs, jet engines and computer chips had to fight for every cent.
Democrats won control of both the House and Senate in Tuesday’s midterm elections, according to The Associated Press. The results set up a divided government for the final two years of President Donald Trump’s term. This could have repercussions when it comes to healthcare stocks.
Investors are grappling with an evolving set of risks as 2026 draws to a close. The scale of the AI build-out is influencing more sectors and industries. Rising interest rates are reshaping market dynamics as inflation threats linger.
US state and local government debt is on track to notch its strongest October in more than four decades, as a relief rally follows one of the worst months for the bond market in years.
Understanding the FAFSA process can help families navigate college financial aid. Bill Cass, director of US Wealth Planning, explores five important considerations, from income and assets to application timing and aid offers.
A stock trading at half its former price is not necessarily a bargain. Perhaps its earnings power has halved or its balance sheet can no longer support the business. Maybe its generous dividend is being financed with borrowed money. A low valuation ratio tells us what we are paying relative to one measure of fundamentals. It does not, by itself, tell us what the business is worth or whether those fundamentals will endure.
The 2026 midterms may have changed Washington, but they haven’t changed the macro regime. Tariffs, geopolitics, and deficits remain key forces for investors.
The votes have been cast. While control of the House and Senate has been decided, now we wait for the final tallies (and celebrate the end of the political ads — at least for another 20 months or so). We’re not political strategists, but policy does move markets, so it’s important to pay attention.
Amid a rapidly changing world, where China’s rise as an industrial powerhouse has nations around the globe on alert, we believe that American reindustrialization will be an important driver of investment returns in the decade ahead.
We have been writing extensively about the rapid evolution of crypto ETFs, and recent data reinforces why digital assets remain top of mind for wealth managers. According to CoinShares, financial advisors hold roughly 55% of Wall Street’s total bitcoin ETF stake at the end of the second quarter, cementing their role as primary drivers of long-term digital asset adoption.