Royce Investment Partners: Co-CIO Francis Gannon details why recent volatility looks like the typical pattern of a US small-cap leadership cycle.
Investors may be overlooking one of the most established drivers of long-term wealth creation: dividend yield. In his October insight, Richard Bernstein, Global Head of Macro & Customized Investing, examines the broad availability of dividend opportunities, how income-focused stocks have performed relative to growth stocks, and why dividend yield may help investors balance portfolios increasingly geared toward capital gains and higher risk.
After overshooting projections for years, AI capex is slowing down. The shift doesn’t spell the end of the AI trade but a move to a more mature, predictable cycle that favors higher-quality borrowers.
New charitable deduction rules may affect year-end giving strategies. Bill Cass examines the changes for 2026 and considerations for taxpayers looking to align charitable goals with tax planning.
Milton Friedman famously said, “inflation is always and everywhere a monetary phenomenon,” emphasizing that sustained inflation occurs when money expands persistently faster than real output.
The Federal Reserve decided to wait for more data rather than raise rates at its October meeting. Two policymakers dissented, favoring a rate hike of a quarter percentage point.
Investors were thoroughly unimpressed with Alphabet Inc.’s third-quarter earnings on Wednesday evening. Shares tumbled nearly 11% after the company missed sales and profit expectations. It was a sign, Bloomberg News reported, that Wall Street wasn’t satisfied that Google is seeing enough of a return on its artificial-intelligence bets.
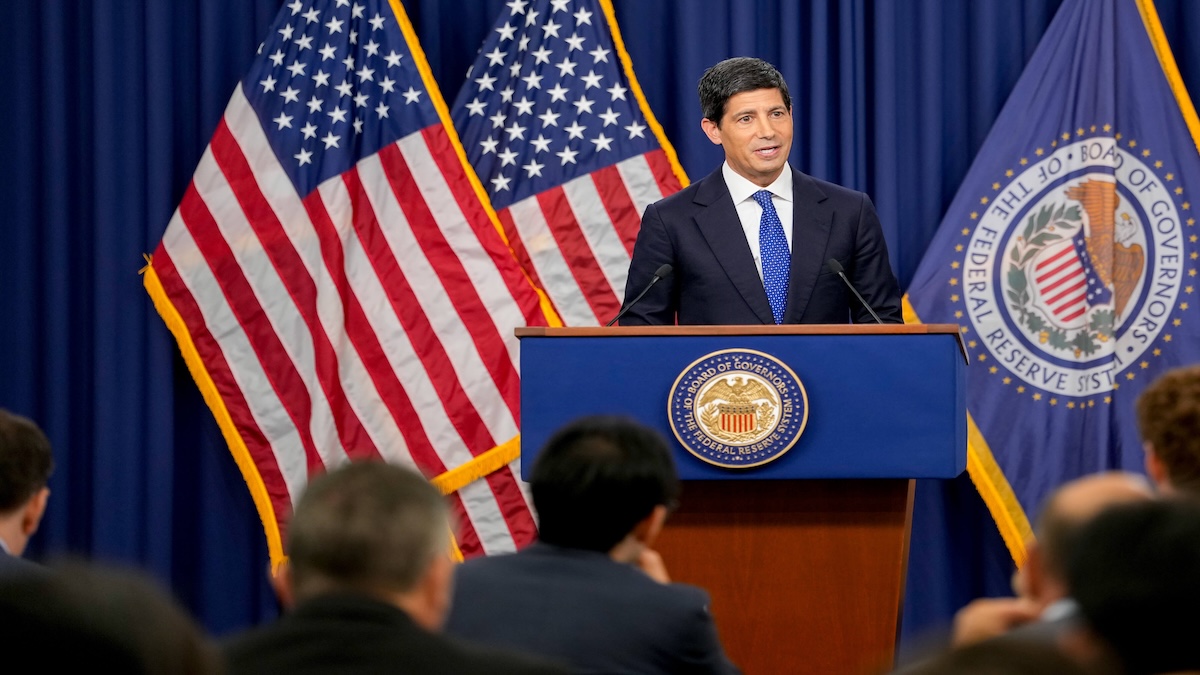
Federal Reserve Chair Kevin Warsh champions parsimony in central bank communications and loathes so-called forward guidance. But he’s said plenty about the future of artificial intelligence: He’s an arch optimist on the technology who thinks it will help him vanquish inflation.
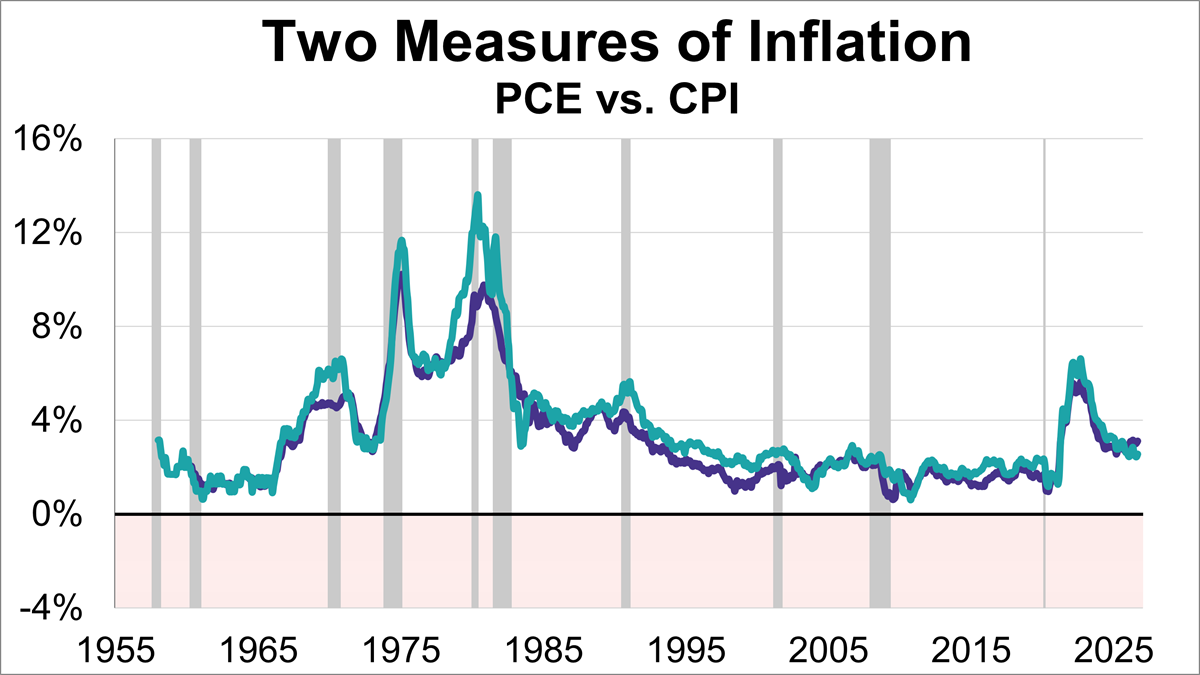
Inflation remains a hot topic, directly impacting everything from your grocery bill to interest rates. As of the latest data, two key inflation gauges — the Personal Consumption Expenditures (PCE) Price Index and the Consumer Price Index (CPI) — show that prices are still above the Federal Reserve's 2% target, with the core PCE at 3.1% and core CPI at 2.6%.
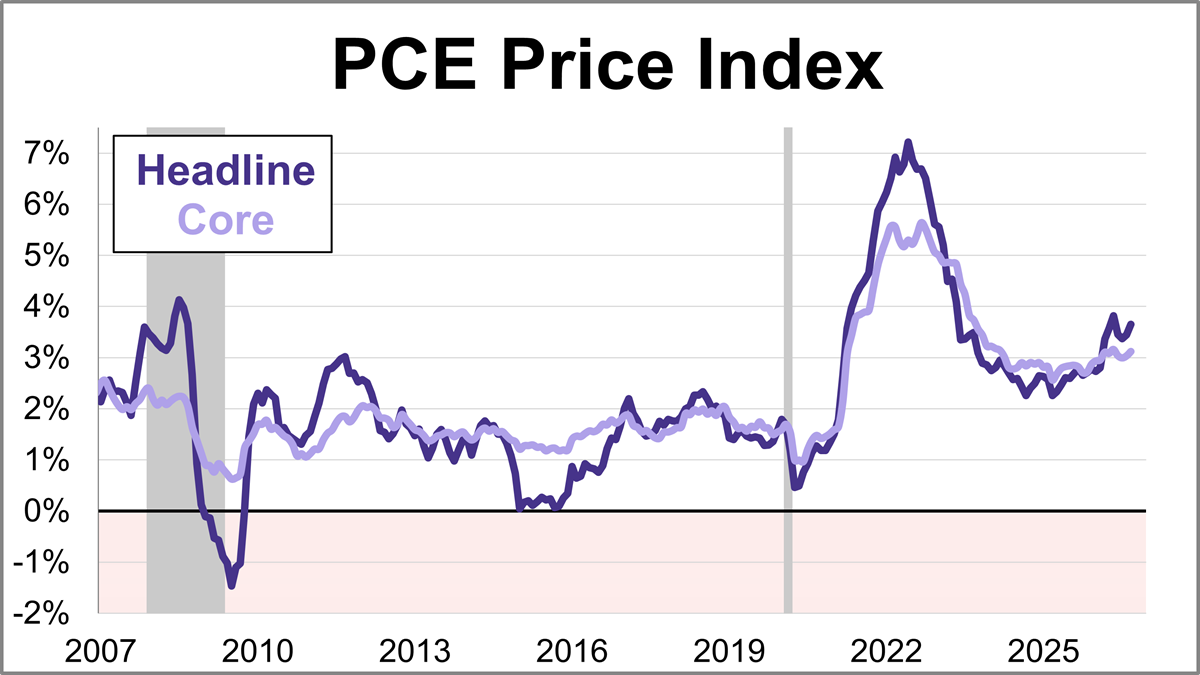
The Federal Reserve’s preferred inflation gauge, the core PCE price index, climbed 3.1% year-over-year in September. This marks a slight uptick from August's 3% reading. On a monthly basis, core prices rose 0.3%.
Join leaders from Victory Capital for an educational webcast that explores how FCF can work across the style box as a quality-oriented diversification lens that can be especially relevant in today’s market environment.
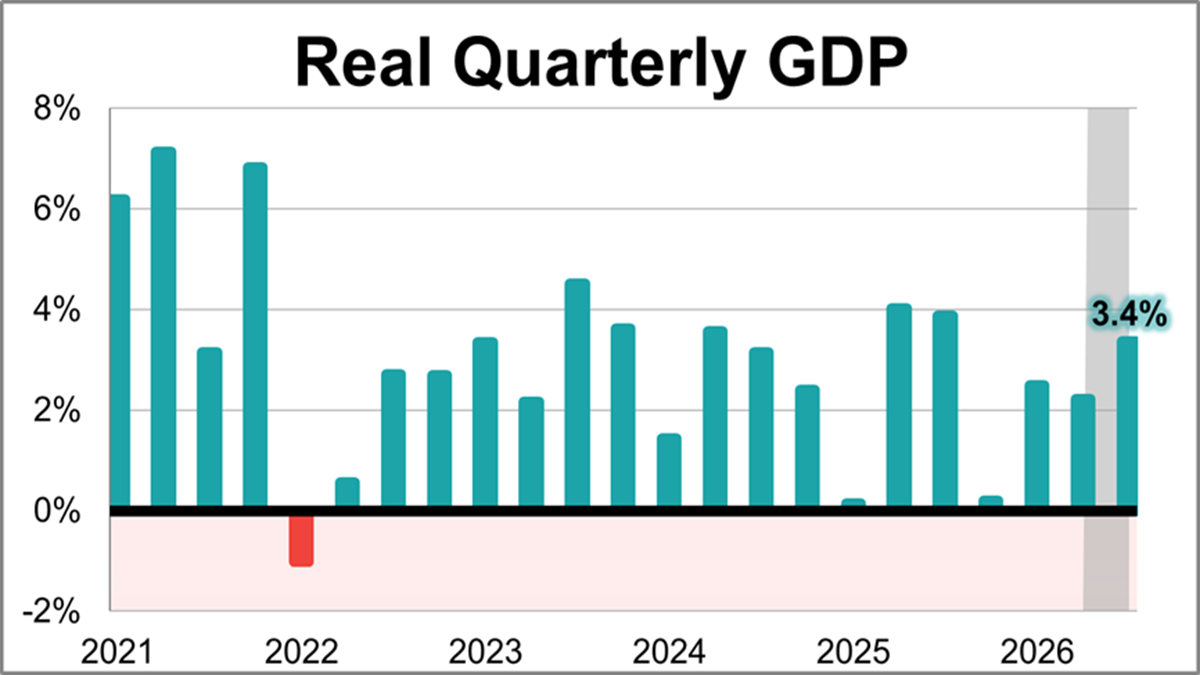
Real GDP rose 3.4% in Q3 for the advance estimate from the U.S. Bureau of Economic Analysis.
Could the near to medium term finally see value ETFs take the starring role back from growth? Value indices have provided some steady returns this year, but the question is, can they accelerate into the new year? Economic headwinds and concentration risk for the AI hyperscalers could see value stocks outperform. The American Century U.S. Quality Value ETF (VALQ) presents a strong candidate to do well if value stocks do.
Wall Street’s recent risk aversion toward stocks may have created an opening for a sharp rebound, particularly in technology shares, if Anthropic PBC’s planned initial public offering reignites enthusiasm for artificial intelligence.
Blistering cloud growth sent Amazon.com Inc. shares soaring after its last earnings report. Now with more than half those gains gone, the firm needs to deliver a repeat performance in order to reignite its faltering stock.
Many long simmering tensions boiled over in France’s protests and riots. Rising borrowing costs for the government proved a crucial pressure point — a message from bondholders grown impatient with a lack of pension reform and the country’s enormous welfare state. Americans would do well to pay attention.
How many eyeball-grabbing headlines can we stuff into the next few weeks? For tech investors, AI concerns mount, with rising credit default swap prices among the hyperscalers and sagging neocloud equities.
With the recent movements in both the stock and bond markets, there was some noteworthy news that got kind of lost. Indeed, the U.S. government posted a $1.99 trillion budget deficit for fiscal year (FY) 2026. While technically it is not a record amount of red-ink, it represented the largest non-COVID-related shortfall ever recorded in modern history.
It’s extremely hard for a chief executive officer to get investors to turn positive about her company when it has posted annual net losses since 2020 and likely won’t make money until 2028. JetBlue Airways Corp.’s Joanna Geraghty made a good start on Tuesday.
The credit market had become more discerning. Companies with greater leverage, more uncertain cash flows, or business models requiring enormous amounts of capital appeared to be more scrutinized.
LPL Research examines three keys to earnings season: broader profit growth, margin pressures, and high expectations amid continued AI investment.
Gold has traditionally been one of the most popular ways for investors to gain commodity exposure, but its recent weakness highlights the differences across various commodities. While precious metals have struggled, energy and certain agricultural commodities have seen stronger returns. Existing diversified strategies are also giving investors more ways to access commodities beyond traditional gold funds.
Founded in 2019 with backing from Japanese investment holding company SoftBank, SB Energy began as a U.S.-based utility-scale renewable energy developer. Today, SB Energy has three lines of business—power, data centers, and solutions.
Welcome to open enrollment season, when millions of Americans are yet again wracked with anxiety over the sizable chunk of their paychecks being sucked up by healthcare costs.
Reasonable minds can disagree about the ideal scope of government, but no one argues against nations providing for their defense. As conflicts emerge and tensions rise, defense spending will take a larger role in all nations’ budgets, with effects that will flow across the economy.
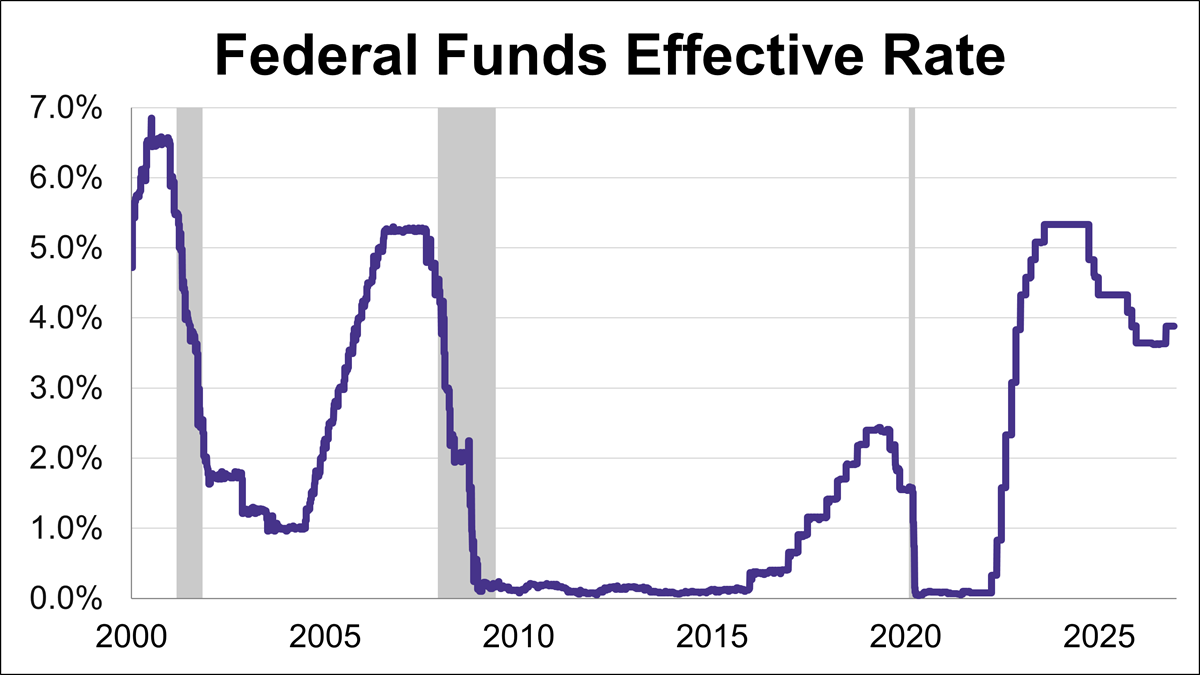
The Federal Reserve held rates steady at the last meeting before the mid-term elections, while setting the table for a likely rate move in December.
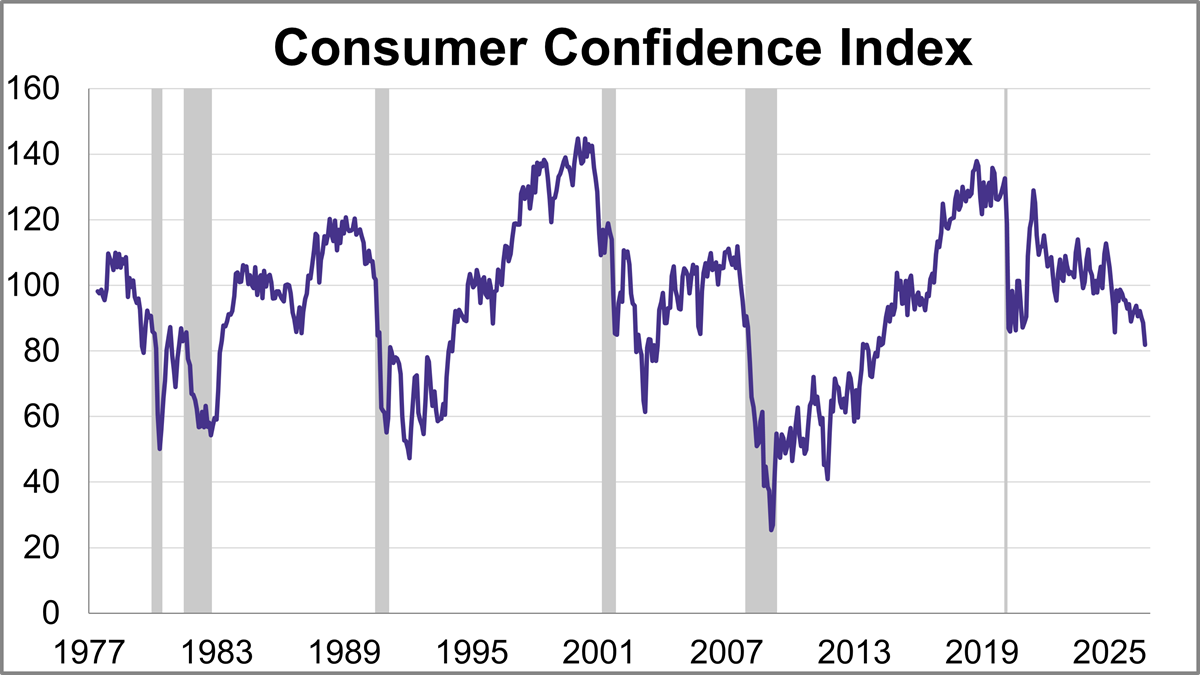
The Conference Board's Consumer Confidence Index® rose significantly more than expected in October, rising 7.5 points to 91.7. The index was far above the forecast of 81.2.
The Federal Reserve concluded its seventh meeting of the year by leaving the federal funds rate (FFR) unchanged, within the target range of 3.75%-4%.
Federal Reserve officials left interest rates unchanged and reiterated their commitment to containing inflation, but without offering a clear signal they might raise rates at their next meeting in December.
Join industry experts from CoinShares for an educational webcast exploring the future landscape of bitcoin mining enterprises.
Income ETF strategies have exploded in popularity in recent years. Historically, investors have looked to bond coupons to add durability to their portfolios. The explosion of ETF popularity, launches, and adoption, however, has seen some intriguing options join the fray. The Goldman Sachs Municipal Income ETF (GMUB), which hits its three-year ETF milestone next year, represents just such a strategy.
Microsoft Corp. and Alphabet Inc. shares have gone separate ways since the companies’ last earnings reports as Wall Street increasingly digs in on the way heavy artificial intelligence spending is weighing on corporate bottom lines.
Investing giant Pacific Investment Management Co. helped supercharge the artificial intelligence debt boom with billions of dollars in lending in 2025 — and has cut positions just in time to skirt losses and eke out a profit.
Hungary unveiled an inter-governmental agreement with the US on nuclear energy, a lucrative area that may bolster ties with Washington following the ouster of Viktor Orban.
These shifts in theatrical and ad strategies show that Netflix is willing to evolve, so there’s no reason its approach to releasing shows should be the exception. If, to borrow Sarandos’ phrase, the company’s bespoke release pattern for certain films means considering the audience, the filmmaker, and the film itself, every title deserves that kind of attention.
Anybody who has lived through the past quarter century or so is familiar with the concept of a debt doom loop. Big government deficits, say, cause higher interest rates, making the government pay more to borrow and also bail out the banks that own its sinking bonds, driving it even deeper into debt. Rinse, repeat.
Investors concerned about market turbulence don’t have to sacrifice return potential to reduce risk. Historically, short-duration high-yield bonds have delivered returns neck-and-neck with those of the broader high-yield market but with substantially less volatility. The recent rise in yields makes today an especially compelling entry point.
Gallup estimates that 70% of a team’s overall success lies with the leader of the team. Here are five takeaways from this year’s class that might be helpful, whether you are firmly in a leadership role, leading without formal authority, or presently climbing the ladder at your firm.
What many firms initially adopted as AI meeting assistants are now evolving into end-to-end AI operating systems. These platforms are becoming a new operating layer for advisory firms, coordinating work across existing technology and helping advisors move from insight to execution.
As information and AI-powered insights become more accessible, experience, judgment, and discernment are becoming increasingly valuable. The advisor's role is evolving from simply providing answers to helping clients interpret complexity, evaluate trade-offs, make decisions with confidence, and execute those decisions effectively.
Economic data that continued to show a strong U.S. economy, housing aside, took a back seat this week as investors once again focused on potential risks to future growth: rising energy prices, sticky inflation, and most importantly, questions about the sustainability of the artificial intelligence (AI) boom.
There was very little macroeconomic news last week, but there was certainly no shortage of action in the markets. We saw an extraordinarily sharp rotation out of growth and into value, with both the Russell Value Index and the S&P Value Index reaching all-time highs even as the Nasdaq suffered one of its largest recent selloffs. That is a dramatic divergence, but historically it is not unprecedented.
The human brain has a remarkable ability to adjust what it considers to be normal, oftentimes very quickly. Experiencing or achieving something that might have previously seemed like a long shot can quickly shift our mindset to expect that outcome over and over again. While yields have been very attractive for the past few years compared to the past several decades, we recently experienced a spike even higher across a range of fixed income products.
US midterm elections take place on Tuesday, November 3. Currently, the Republican party is in control of the House and the Senate. This vote will essentially be a referendum on the Republican party’s body of work. It’s likely the composition of either the House or the Senate will change.
Keynes’ influence is still very much alive. As one point of evidence, Robert Hall of Stanford University and Michael Woodford of Columbia University, champions of what is now known as “The New Keynesian Theory,” were recognized with this year’s Nobel Prize in Economics.
Higher yields do not automatically make longer-duration bonds attractive, as persistent inflation, resilient growth, and heavy debt issuance could maintain upward pressure on yields in the near term.
Geopolitical tensions are already driving demand for energy exposure through rising oil and gas prices. Combining this cyclical strength with long-term AI momentum creates a strong potential for noticeable returns.
Clients want to understand how the advisor thinks, what they value, and what guides them when hard decisions arise. Your clients want to hear a familiar voice, not another generic, institutional message that could have come from any firm in the country.
Family offices do not need to choose between ignoring AI entirely and adopting it everywhere at once. A practical middle path exists, and it starts with controlled experimentation. By protecting sensitive information, choosing a well-defined use case, and confirming that the underlying data can actually support it, family offices can see significant benefits from AI without introducing significant risks.
Record ETF launches are compressing product shelf lives and raising closure risks. Learn the real costs for advisors and clients.