US stocks were higher after the market opened as Americans headed to the polls on Election Day, with control of both chambers of Congress at stake and investors weighing mounting risks to the artificial intelligence trade.
The Bank of Japan’s decision to accelerate sales of exchange-traded funds could boost its payments to the government, potentially helping Prime Minister Sanae Takaichi finance her costly policy agenda.
Technology took us out of our homes. It gave us a boss, office politics and an alarm clock — and it was awful. We got used to it; we made it work. Now technology might take those jobs away. But perhaps it will also restore the autonomy and flexibility that once defined work.
In spite of all the angst, the economy keeps growing, with real GDP growth clocking in at a 3.4% annual rate for the third quarter, led by strong consumption and business investment, with much of both powered by the expansion of AI and data centers. In addition, it looks like the economic momentum will carry into the end of the year, with the Atlanta Fed’s GDP Now model starting off projecting Q4 growth at a 3.2% rate.
A few years back, I compared two island-nations whose leaders came to power in 1959. At the time, Cuba was by far the wealthier of the two—rich in sugar, tobacco and tourism—while Singapore was a sleepy former colonial outpost with almost no natural resources.
Last week, the AI trade began to crack further with Alphabet’s release, missing on both the top and bottom lines. Mirroring Meta’s print from the prior week, massive AI capex turned free cash flow negative, alarming investors.
While the bulls certainly have control of the narrative, there is a problem with treating that scoreboard as the end of the argument. The bears weren’t wrong about the inputs. They were wrong about ONE variable. Which one matters is important because it will decide whether the case still stands today.
As the days grow shorter and the nights longer, Americans will turn their clocks back, shifting from daylight saving time to standard time. But the clocks won’t be the only thing changing. Americans will also head to the polls, with the potential to reshape Congress in the 2026 midterm elections.
With the one constant being that gold fell again, this time by 6.6%, October’s price action is a mirror image of what happened in markets in September. In September, tech and momentum led the charge higher, with anything value- or rate-related leading the selloff. October was the exact opposite.
Innovation takes time—very often years—and can be expensive. For example, it wasn’t so long ago that Nvidia was considered to be just a gaming company. Today, it is one of the largest companies in the world with a dominant position in hardware and software tools powering the artificial intelligence (AI) revolution.
I spent the majority of my time in the retail bond business during the zero-rate period. The problem during that time was fairly simple. A bond would yield about 1.5%, while a retiree would need about 5%. There had to be a solution, and Wall Street was quick to provide it.
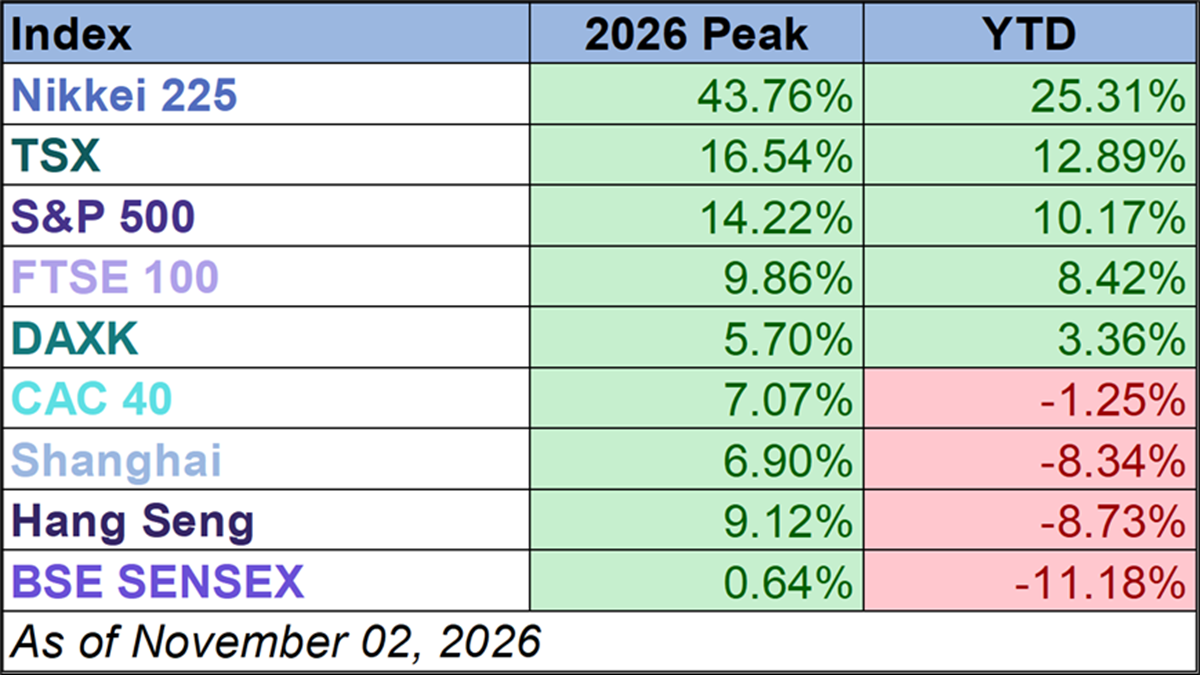
Five of the nine indexes on our world markets watch list posted year-to-date gains through November 2, 2026.
Medicare's annual enrollment period gives advisors an opportunity to revisit healthcare coverage with clients. While advisors needn't become Medicare experts, they can help identify issues that warrant a closer look or consultation with a qualified Medicare professional.
Join industry-leading experts from T. Rowe Price for a product due diligence session exploring the expanding digital asset ecosystem, the potential benefits of active management, and how crypto investments may complement traditional portfolios.
The prolonged impact of raising the Fed Funds rate, coupled with the recent surge in long-term bond yields, is exactly the kind of over-restrictive policy mistake the bond market may be worried about, helping explain the recent decline in long-term yields.
Instead of making defensive, fear-driven claiming choices, financial planners are urged to stress-test retirement plans against a baseline 78% benefit level to ensure essential expenses remain covered.
Investors who own bonds are seeing losses in their accounts. Many are not happy, and many just want out. The losses over the past five years are significant. After the biggest decline in the history of the bond market in 2022, bonds stabilized until this year, when the decline resumed. Here’s why I tell clients that they should be thrilled.
The runup in Apple Inc. shares in recent months has left the iPhone maker little room for disappointment when it reports earnings after the bell on Monday.
When Elon Musk pledged to give a share of SpaceX to each child in the US, the proclamation was met with a certain amount of skepticism. Regardless of Musk’s motivation or whether his promise comes to fruition, he has — inadvertently or not — hit on a worthwhile idea.
Anthropic PBC reported third-quarter revenue of nearly $17 billion as of Sept. 30, a twelve-fold increase versus the same period a year ago that’s set to stoke anticipation for the artificial intelligence lab’s potentially record-breaking IPO.
As gold heads toward its worst annual loss in more than a decade, investors are gauging the odds a political shift in the US will restore the precious metal’s haven allure.
Marvell Technology Inc. has reached a deal to buy data center optics maker Lumentum Holdings Inc. at an enterprise value of $115 billion, one of the biggest tech tie-ups ever, in a race to capitalize on the artificial intelligence boom.
US manufacturing activity picked up in October, supported by the strongest production growth in nearly five years.
The stock market doesn’t wait for GDP. The ratio of consumer discretionary stocks to consumer staples has fallen about 19% from its late-2025 peak, suggesting the so-called “smart money” has been quietly moving out of what people want and into what people need for most of this year.5
Credit problems in the AI space are not going to be contained to just the AI space. It is going to have impacts all throughout the economy and global markets. I guarantee you central banks are paying attention as it is affecting what they have to charge for sovereign debt.
Despite the fact that digital tools such as AI advisors are becoming increasingly available, investors are still seeking out human financial advisors.
Rising U.S. Treasury yields have added fresh strain to the U.S. housing market. The average 30-year mortgage rate, which generally tracks the 10-year U.S. Treasury yield plus a mortgage spread, rose to 7.5% in October 2026, according to Mortgage Bankers Association data, worsening an affordability crunch that remains a top concern among U.S. households.
Starting December 6, 2026, Nasdaq and NYSE Arca will officially launch extended trading sessions, expanding U.S. stock trading to up to 23 hours a day, five days a week.
In today’s modern financial landscape, market-capitalization-weighted indices dominate the investment ecosystem with trillions of dollars tracking broad market indices such as the S&P 500 and the Russell 1000. However, a research article by RAFI Indices™, adapted from the CFA Institute Research Foundation series The Active Side of Indexing, exposes flaws within cap-weighted benchmarks.
Large-cap stocks may be better built for 5% Treasury yields than their smaller rivals, according to State Street Investment Management’s quarterly outlook. The 10-year yield climbed 0.81 percentage points last quarter to 5.28%, a near 20-year high.
The strength of the US economy during the third quarter was hardly a surprise. We expected economic growth of 3.5%, and the first estimate came in only slightly below that at a 3.4% quarter-over-quarter, seasonally adjusted annualized rate. Consumer spending and investment tied to the AI and data center buildout remained the primary drivers of growth.
Infrastructure has long been valued for its defensive characteristics, income potential and ability to protect against inflation. Essential assets such as electricity networks, pipelines, railways, airports and toll roads typically benefit from high barriers to entry and predictable revenues.
Chuck Carnevale analyzes seven stocks using FAST Graphs, showing how earnings, cash flow, and valuation charts reveal the business behind the stock price—and why a popular stock is not always an attractive investment.
Today I want to tell you about the city of Shenzhen. Unless you are in global manufacturing, you may not have heard of this Chinese city of 18 million people. As recently as 1979, the area had only 30,000 residents, living in small fishing villages. Today, it is one of the most modern cities in the world. It is also quite wealthy.
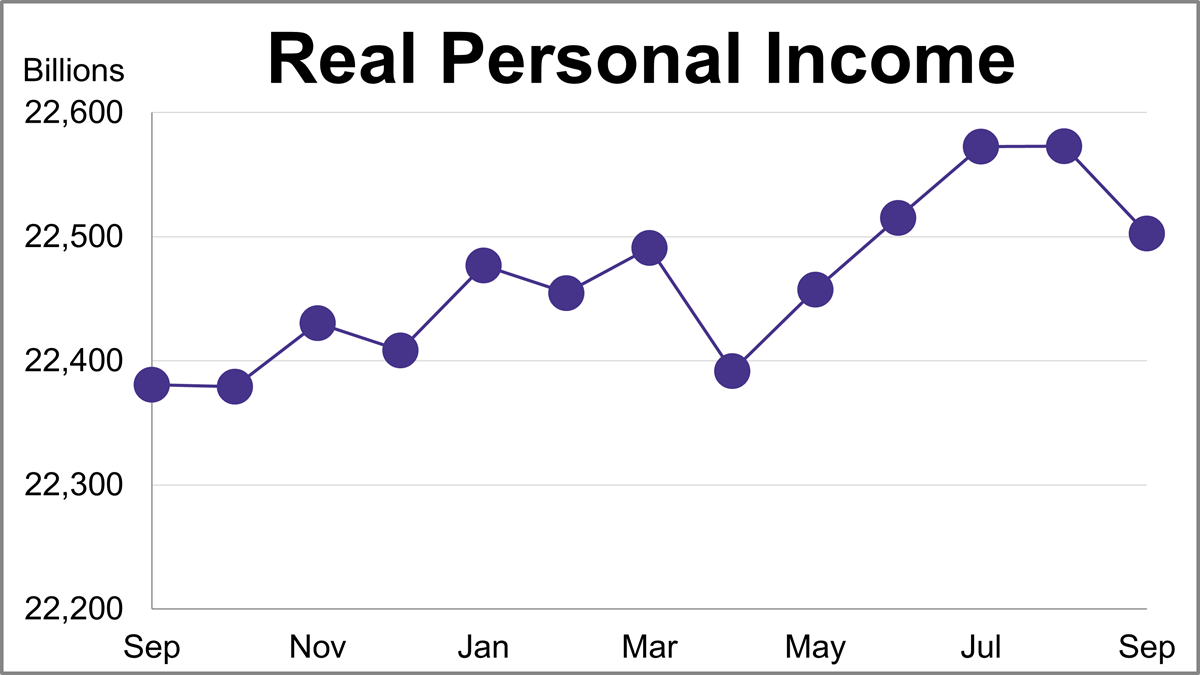
Personal income (excluding transfer receipts) was up 0.18% in September and was up 4.21% year-over-year. However, when adjusted for inflation using the BEA's PCE Price Index, real personal income (excluding transfer receipts) was down 0.31% month-over-month and up 0.54% year-over-year.
The Fed held rates steady at its October meeting but kept the door open to further tightening, with two dissenting votes and hawkish rhetoric signaling that the pause is a skip, not a stop.
In this episode of the Money Metals Midweek Memo, host Mike Maharrey considers how artificial intelligence could affect trust, cybersecurity, and investors’ access to their money. He also discusses silver’s sharp correction, the long history of gold jewelry, and ways listeners might use precious metals as a physical store of value.
Consumer staples are behaving (in a good way) like their technology counterparts. It may be the latter that’s helping the former. There are currently renewed fears about AI bubbles and hefty spending by hyperscalers. So some investors are trimming tech exposure and heading to more docile pastures, including staples.
The economy appears to be settling into a new equilibrium. Economic growth has moderated to a sustainable pace. While inflation has picked up over the last few months, there does not seem to be a fundamental shift in the underlying trend.
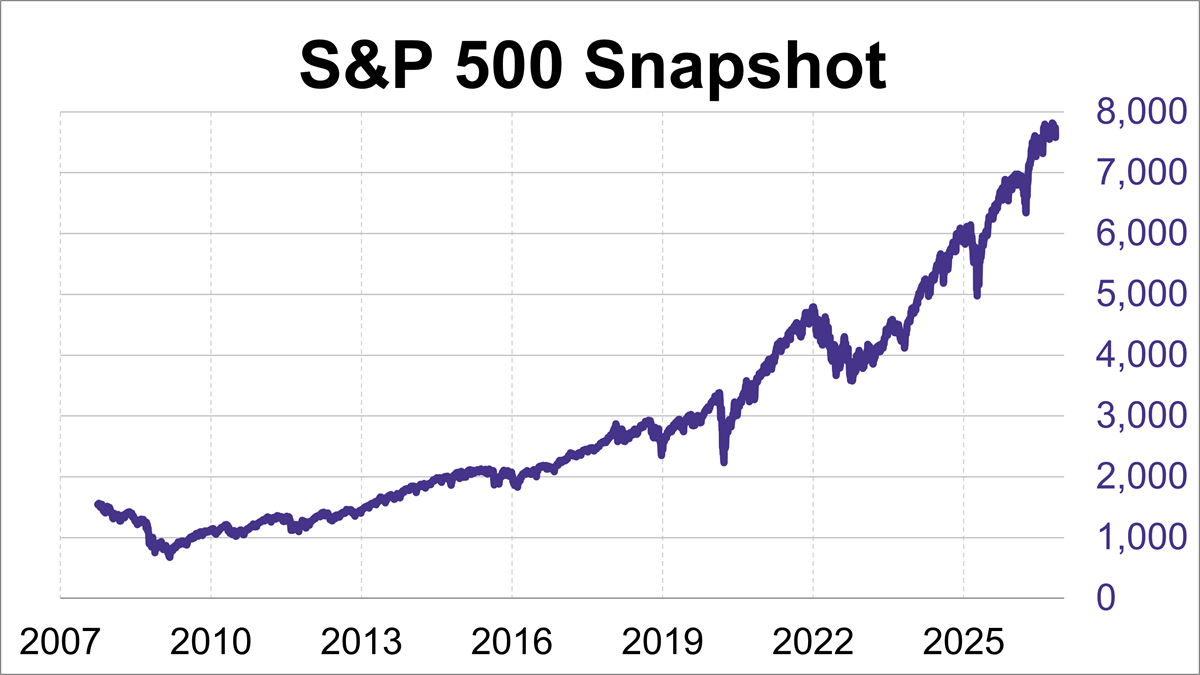
The S&P 500 fell 0.57%, capping off its third straight weekly loss.
The new SPYM ETF mutual fund share class, SPYMX, may yet pick up some strong new flows with its appeal to institutional investors.
Valid until the market close on November 31, 2026
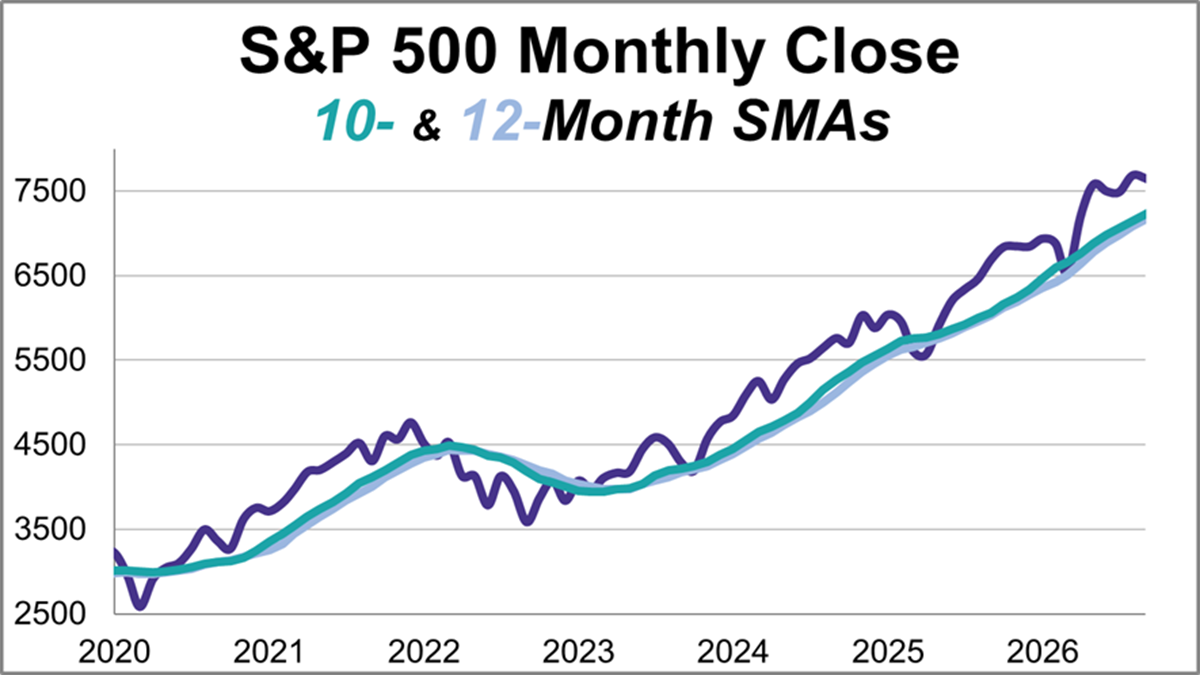
This article provides an update on the monthly moving averages we track for the S&P 500 and the Ivy Portfolio after the close of the last business day of the month.
Investors often treat growth and dividends as opposing camps, but in practice, this means the two can complement each other.
Wall Street expects Democrats to win at least one of the houses of Congress in the US midterm elections on Tuesday, setting the stage for a potentially volatile ride in the stock and bond markets with artificial intelligence oversight, defense spending and crypto legislation on the table.
Equity investors are meting out some of the harshest punishments ever for companies that miss expectations, just as strategists sound the alarm that earnings growth has likely peaked.
ExxonMobil Holdings Corp. plans to invest more than $100 billion over the next few years to help augment global energy supplies, Chief Executive Officer Darren Woods told CNBC after the supermajor posted blockbuster quarterly results.
Advisor Perspectives is launching a new website in January 2027. Learn what’s changing, and what to expect from the updated experience.
The AI investment boom has become one of the largest sources of demand in the U.S. economy. Announced annual capital spending across large U.S. technology companies points to more than $1 trillion in desired investment, up dramatically from only a few years ago.
The Federal Open Market Committee (FOMC) decided to keep rates unchanged, maintaining the fed funds trading range at 3.75% to 4.00%. After some early back and forth on the chances for a rate hike at this gathering, this result was largely expected. In fact, fed funds futures were pricing in more than a 90% chance that the fed funds target would remain unchanged.
Franklin Templeton plans to launch two ETFs Thursday that use stock dividends to buy bitcoin instead of more shares.